Integra Reports Third Quarter 2026 Results from Florida Canyon: Increase in Quarterly Gold Production and Strengthened Financial Position; Provides Operational Update
Output guide cut 17% just 20 days after management publicly reaffirmed it
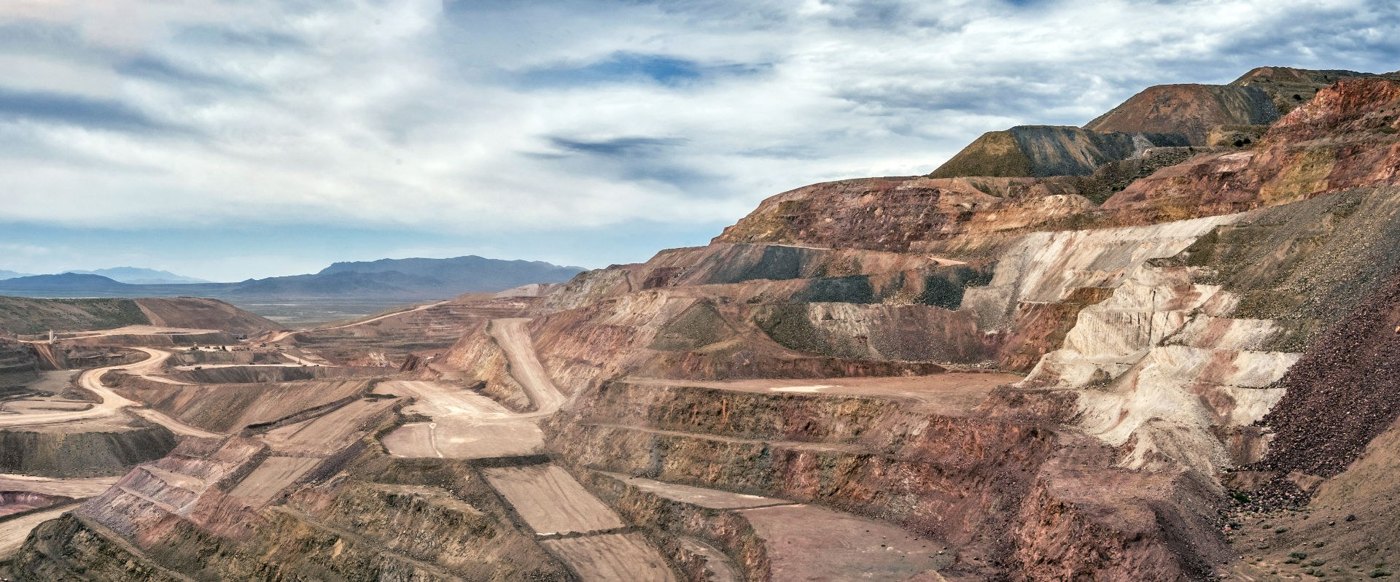
This is Integra's Q3 2026 earnings release (quarter ended September 30, 2026), and it carries three distinct messages of very different quality:
- A guidance cut. Full-year 2026 Florida Canyon production goes from 70,000-75,000 oz to 59,000-62,000 oz — a reduction of 11,000-13,000 oz, or 16.6% at the midpoint (72,500 oz to 60,500 oz). The stated cause: "recent leaching rates have not kept pace with increased mining rates," so mining rates are being reduced for the remainder of 2026 "to maintain effective blending and long-term heap leach pad performance."
- A headline "increase" that is really a year-over-year decline. Q3 production of 17,652 oz is +8% vs Q2 (16,379 oz) but -14.5% vs Q3 2025 (20,653 oz). Ounces sold fell -17.3% to 16,760 oz.
- A stronger balance sheet and a profitable quarter. Net earnings of $12.9M ($0.06/sh) vs a $8.2M net loss in Q3 2025; cash of $119.5M; working capital $159.5M; no corporate debt.
Milestones restated (no new data): DeLamar NEPA scoping complete, EIS/Record of Decision anticipated H2 2027; GenCap Mining Advisory engaged to structure DeLamar financing; Wildcat EPO fully approved with exploration drilling started August 2026; 31,364 m of the 42,500 m Florida Canyon program drilled year to date.
The release text was truncated at 40,000 characters, so the tail of the non-GAAP reconciliation and any closing commentary are not visible; all figures below come from the visible portions or the as-reported statements.
The guidance cut is genuinely new information. On October 22, 2026 the company stated in writing that full-year guidance "remains 70,000 to 75,000 ounces"; nothing in that release disclosed a leach shortfall. Today's cut therefore removed 11,000-13,000 oz of expected 2026 production that the market had been told to expect three weeks earlier.
The mechanism matters more than the headline. Integra deliberately traded grade-mix quality for volume: run-of-mine ore placed on pads rose to 3,318 kt in Q3 versus 1,165 kt a year earlier, while crushed ore fell to 1,889 kt from 2,003 kt. ROM now represents 64% of stacked tonnage versus 37% a year ago. Blended recovery fell to 52.5% from 60.7% (and from 59.9% in Q1 and 57.8% in Q2 — a straight-line deterioration). The company mined and stacked far more rock than it could leach, then cut mining rates to let the pad catch up. That is a design/sequencing error, not a weather event.
Quantifying the scale: Q3 stacked 5.207 Mt at 0.25 g/t, or roughly 41.8 koz of contained gold stacked in a single quarter, against 17,652 oz produced. The honouring of those ounces is now pushed into future periods, and the cost of mining them has already been paid. Nine-month free cash flow of $23.5M on $204.9M of revenue, in a year when realized gold averaged $4,487/oz, is weak conversion.
Market context into the print: the stock closed at $3.61 on the prior earnings release (August 11, 2026) and $3.00 on November 11 — -16.9% — and is -53% from its $6.38 January high. Some of that de-rating reflects a softer gold price (realized $4,272/oz in Q3 versus $4,426/oz in Q2 and $4,854/oz in Q1) and the earlier cost-guidance resets. The cut itself was not previously disclosed. The loss of roughly 12,000 oz of high-margin production at ~$4,200/oz realized is on the order of $30M-$35M of revenue at a cash margin above $1,800/oz — meaningful against a company that generated $23.5M of free cash flow in nine months.
Integra Resources is a Great Basin precious metals producer, listed on the TSXV (ITR) and NYSE American (ITRG), that transformed from developer to producer via the late-2024 acquisition of the Florida Canyon Mine in Pershing County, Nevada (about 45 miles southwest of Winnemucca). Florida Canyon is currently the sole source of revenue: a conventional open-pit, heap-leach operation with a newly updated eight-year mine life and 1.19 Moz of reserves.
The development pipeline consists of the past-producing DeLamar gold-silver heap-leach project in Owyhee County, Idaho (feasibility study complete, effective December 8, 2025; in federal NEPA review with a Record of Decision targeted H2 2027), and the Nevada North project (Wildcat and Mountain View deposits, about 26 miles west of Florida Canyon), which is at pre-feasibility stage.
The company reports approximately 6.9 Moz AuEq Measured & Indicated and 3.1 Moz AuEq Inferred across the three assets (March 2026 corporate presentation). Management: George Salamis (President, CEO and Director), Clifford Lafleur (COO), Andrée St-Germain (CFO), James Frost (Director, Technical Services and Qualified Person), with Anna Ladd-Kruger as Board Chair.