Urion Investments Holdings Sarl Files Early Warning Report in respect of Atico Mining Corporation
Trafigura files to formalise a 19.9% diluted stake in Atico with no new operating news reported.
Urion Investments Holdings Sárl, acting on behalf of the Trafigura Group, filed a regulatory Early Warning Report with Atico Mining Corporation (ATY), disclosing a significant acquisition of the mining company’s securities. The filing details transactions executed on October 15, 2026, involving both equity and debt instruments issued by Atico.
Trafigura acquired 16,149,870 common shares at a deemed price of approximately US$0.1548 per share. These shares were issued in settlement of US$2,500,000 (C$3,524,250) owed under a credit agreement dated February 8, 2022. In addition to the equity stake, Trafigura acquired a secured convertible debenture with a principal amount of US$16,400,000. This debenture was issued via a non-brokered private placement, comprising an advance of approximately US$12.48 million and the conversion of approximately US$3.52 million of existing debt from the credit agreement. The aggregate consideration for the debenture was approximately US$16 million (C$22,555,200), after accounting for an original issue discount.
The debenture carries a conversion price of US$0.22 per share and matures five years and one day from the date of issuance. Interest is payable quarterly at a rate of 7.0% if paid in cash, or 10.0% if paid in shares. Full conversion of the principal would result in the issuance of up to 74,545,454 shares; however, absent approval from the TSX-V and disinterested shareholders, the number of shares issuable upon conversion is capped at 27,323,116.
Prior to the closing of these transactions, Trafigura held no beneficial interest in Atico’s shares. Following the acquisition, Trafigura beneficially owned 16,149,870 shares, representing approximately 8.1% of the 199,119,767 shares outstanding on a non-diluted basis, and approximately 19.9% on a partially diluted basis. The report states that the investment was made in connection with the refinancing and settlement of Atico’s indebtedness. Trafigura retains the right to increase or decrease its holdings, including through forced conversion or the acceptance of interest payments in shares. The filing contains no production, cost, reserve, guidance, or financial information regarding Atico’s operations.
Atico Mining Corporation (ATY) filed an early warning report detailing the ownership stakes of Trafigura following the closure of a US$111.4 million financing package. The transaction, which included a US$95 million La Plata project finance facility and a US$16.4 million convertible debenture, was announced on September 29, 2026, and closed on October 15, 2026. The filing confirms that Trafigura held no shares prior to the transaction and now holds an undiluted ownership of 8.1% and a partially diluted ownership of 19.9%.
The stock’s market reaction to the financing was muted. Atico Mining closed at $0.21 on September 28, $0.22 on September 29, $0.24 on September 30, and $0.21 on October 22, following the closing and the early warning filing. The company’s market capitalization stands at approximately C$41.8 million, or about US$30 million, which is significantly smaller than the US$111.4 million in committed financing.
The transaction converts a lender relationship into a significant equity position for Trafigura. The convertible debenture provides a path to 19.9% ownership and potentially 74.5 million shares upon full conversion, against a current share count of 199.1 million. The deal marks a major global commodity trader as both a material equity holder and the sole project financier for the La Plata asset, signaling validation of the project’s offtake and financing capabilities while concentrating the company’s exposure to a single counterparty.
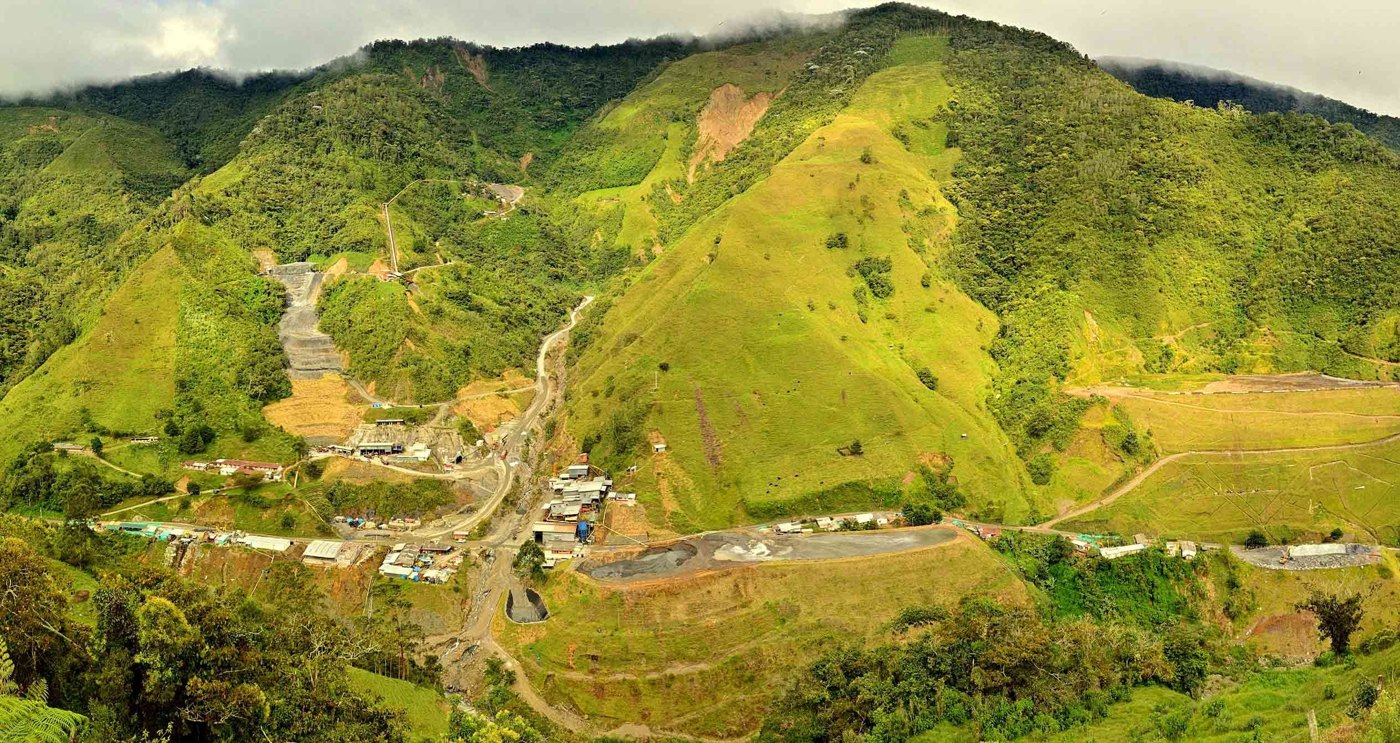
Atico Mining Corporation (ATY), a Vancouver-headquartered, TSX-V listed copper and gold producer reporting in US dollars, operates assets in Latin America. The company’s sole source of current revenue is the El Roble mine, a 90%-owned underground copper-gold volcanic-hosted massive sulphide operation in the Chocó department of Colombia. El Roble sits on a 6,355-hectare contiguous land package and utilizes a nominal 1,000 tonnes per day processing plant featuring grinding, milling, and flotation capabilities. The project is projected to produce approximately 10 million pounds of copper and 8,500 ounces of gold annually. However, trailing four-quarter actual output from Q3 2025 to Q2 2026 reached only approximately 9.0 million pounds of copper and 8.0 thousand ounces of gold, running below the projected rate.
Atico also owns the La Plata project, a 100%-owned, 2,300-hectare mafic-type VMS property located near Quito, Ecuador. The project is at the pre-construction stage, having completed a definitive feasibility study in 2024. Planned annual production at 850 tonnes per day includes 10 million pounds of copper, 13 million pounds of zinc, 16 thousand ounces of gold, and 227 thousand ounces of silver, positioning the asset to become Ecuador's second medium-scale mine. Regional exploration upside includes a 10-kilometre prospective stratigraphic contact at El Roble controlling VMS mineralisation, over 21 prospective drill targets across the property, and the Guatuza and Q. Romero targets at La Plata, where Guatuza returned 6.8 metres at 7.0% copper and 1.0 grams per tonne gold.
The company’s stated strategy is to build a mid-tier producer through organic growth and the disciplined acquisition of small-to-medium advanced-stage projects in Latin America. Geography remains a live risk, with both Colombia and Ecuador exposing the company to permitting, social, regulatory, and currency challenges. The MD&A explicitly flags regulatory and political risk in Ecuador, including constitutional court appeals.