Atico Announces US$95 Million Project Finance Facility and US$16.4 Million Convertible Debenture Private Placement for a Total of US$111.4 Million
Trafigura funds the La Plata project build-up as El Roble reserves near expiry.
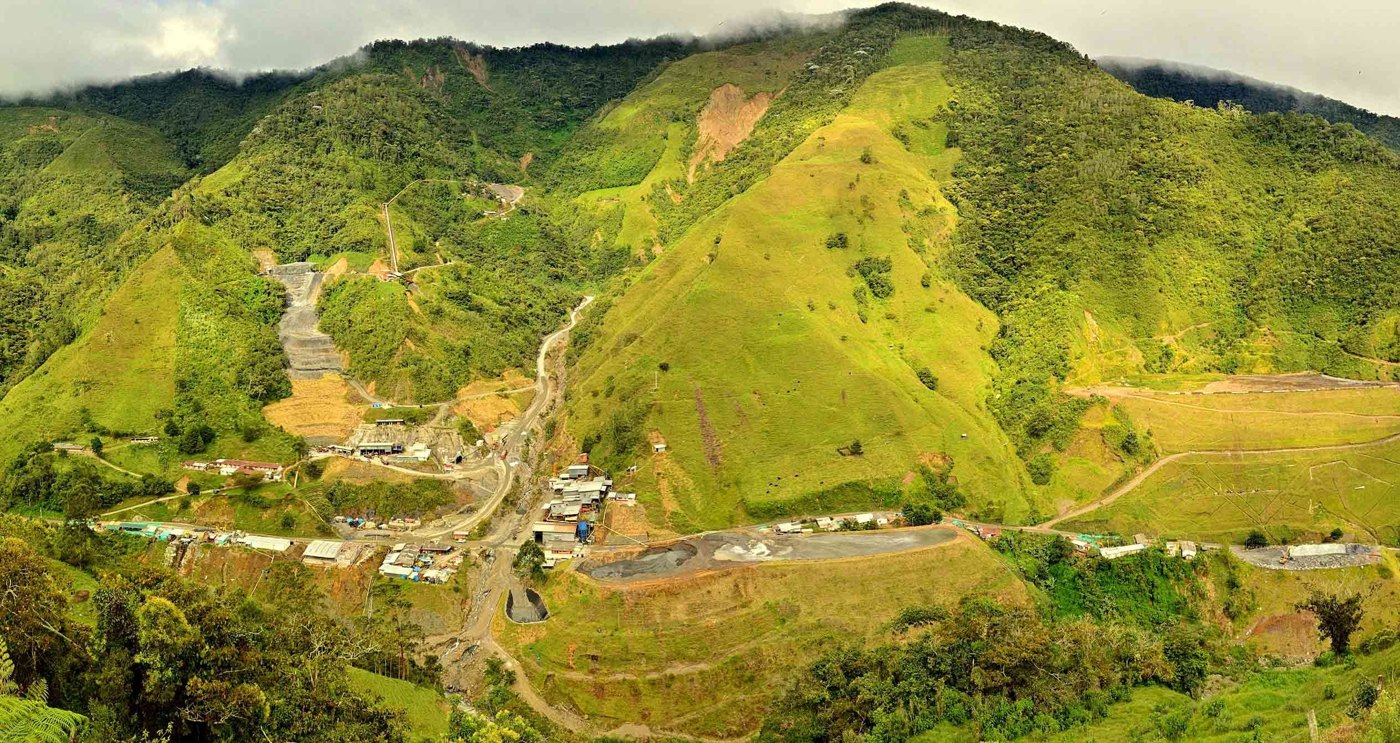
Atico Mining Corporation (ATY) announced a US$111.4 million financing package to fund the construction of its La Plata VMS project in Ecuador. The capital structure comprises a US$95 million secured project finance facility and a US$16.4 million secured convertible debenture, both provided by Trafigura PTE. Ltd. or its affiliate.
The US$95 million project finance facility is borrowed by Compañía Minera La Plata S.A. (CMLP), with Atico Mining Corporation and Toachi Mining Inc. serving as guarantors. Drawdowns are available for approximately 2.5 years following the earlier of the commencement of construction or March 31, 2027, with maturity occurring seven years thereafter. Interest is set at Adjusted Term SOFR plus 7.5% per annum, secured by all La Plata project assets. The parent guarantee is released once La Plata achieves completion.
The convertible debenture carries a face value of US$16.4 million and net proceeds of US$16.0 million. It matures in five years and one day, with a conversion price of US$0.22 per share, representing a 40% premium to the 20-day VWAP on September 28, 2026. The instrument carries a 7.0% coupon if paid in cash or 10.0% if paid in shares. Early redemption fees are 3% in year one, 2% in year two, and 1% thereafter. Atico Mining can force conversion of up to 25% of the principal on four occasions at escalating VWAP thresholds of 130%, 140%, 150%, and 160%. Underlying shares carry a four-month-and-one-day hold period.
Proceeds from the debenture will be used to repay approximately US$3.5 million of the Existing Trafigura Credit Agreement (of which approximately US$6.0 million remains outstanding), repay all outstanding Dundee Corporation debenture debt (approximately US$6,980,551), initiate La Plata pre-construction activities, and fund general corporate purposes. Additionally, 16,149,870 common shares were issued to Trafigura at a deemed price of approximately US$0.1548 to settle US$2.5 million of the Existing Trafigura Credit Agreement. Combined with the US$3.5 million cash repayment, no further amounts will be owing under that facility.
Ventum Financial acted as advisor. Fees include 0.75% (US$712,500) in cash on the credit facility and 3.5% on the convertible debenture, of which 2% (US$328,000) is paid in cash and 1.5% is satisfied with 1,589,147 shares at approximately US$0.1548. Closing is expected on or about October 13, 2026, subject to TSX-V approval, with the first advance under the facility expected sometime thereafter.
The release does not specify a final investment decision (FID) date for construction, describing only "pre-construction activities." No offtake, marketing, or streaming terms are disclosed. The capex estimate remains unchanged from the US$91 million initial capex cited in the August 2024 feasibility study, and no production or cost guidance is updated. The quoted prices of US$0.22 for the conversion price and US$0.1548 for the deemed issue price are deal prices, not market prices; the last close was C$0.22.
Atico Mining Corporation (ATY) has disclosed the specific terms of a US$111.4 million funding package for its La Plata project, providing details on size, structure, and pricing that were previously undisclosed during a competitive review process. The package is approximately 3.8 times the company’s entire equity market capitalization. The financing consists of project-level, secured, largely non-recourse debt, with the Atico parent guarantee released upon project completion. This structure contrasts with the deeply dilutive equity raises the market had anticipated, such as the July 2025 rights offering and LIFE offering, both struck at C$0.11.
The transaction clears approximately US$13.0 million of legacy high-coupon debt, including the 12% Dundee debenture, and extends the maturity wall by roughly a decade. Trafigura serves as the counterparty for the facility. The deal removes the primary uncertainty regarding how the La Plata project will be built, though it does not constitute a tier-one discovery, takeover, or reserve expansion. The asset base and net asset value remain unchanged by this release.
The financing carries significant costs and dilution. The coupon is set at SOFR plus 7.5%, resulting in an all-in rate of approximately 11–11.5% at current rates, which equates to roughly US$10.9 million in annual interest once fully drawn. This interest expense is substantial relative to El Roble’s trailing four-quarter operating cash flow of US$13.1 million, as reported in the investor presentation. The deal also introduces near-term dilution of 17,739,017 shares, comprising 16,149,870 shares-for-debt and 1,589,147 fee shares, representing approximately 9.8% of the 181.35 million shares outstanding. Additionally, a convertible instrument with 74.5 million underlying shares (US$16.4 million / US$0.22) represents a further approximately 37% of the current share count if fully converted.
The US$95 million facility is a project-level construction loan secured only on La Plata assets, though the parent guarantee means Atico’s consolidated balance sheet stands behind the debt until completion. Consequently, the facility should not be directly compared against El Roble’s company-wide cash flow. The initial capital expenditure of US$91 million and after-tax net present value of US$93 million are figures from an August 2024 feasibility study. These figures are prior-period context and have not been restated; they are likely stale given two years of cost inflation and higher metal prices.
The price series ends on September 29, 2026, the date of the release at 15:14, before the market close. There is no post-announcement price data available to determine how the market received the information.
Atico Mining Corporation (TSX-V: ATY | OTCQX: ATCMF) is a Vancouver-headquartered copper-gold company focused on Latin America, positioning itself as a "growth-oriented" junior seeking mid-tier status through organic growth and acquisitions.
The company operates the El Roble mine, a 90%-owned underground copper-gold VMS property in Carmen de Atrato, Chocó, Colombia. The facility has a nominal processing capacity of 1,000 tpd and is currently running at approximately 740–790 tpd. Reserve life extends to Q1 2027. The property package comprises 6,355 hectares with more than 21 prospective drill targets, and a regional drill programme is planned for 2026–27 over a 2km trend.
The La Plata project, located near Quito, Ecuador, is a 100%-owned high-grade mafic-type VMS deposit on a 2,300-hectare land package. An August 2024 NI 43-101 definitive feasibility study defined the project with an initial capex of US$91M, an after-tax NPV of US$93M at 8%, an IRR of 25%, a payback period of 3.4 years, an 8.1-year initial mine life, and an estimated AISC of US$1.68/lb CuEq. The planned throughput is 850 tpd. The project holds an Environmental Licence, water use permit, waste generator registry, and chemical substances registry, with permitting at the final auxiliary-permit stage. The MD&A notes ongoing constitutional court appeals. La Plata would be Ecuador's second medium-scale mine.
Management includes CEO Fernando E. Ganoza, who has over 25 years of Latin American mining experience and is a former Fortuna Silver executive; CFO Matias Herrero; Director Luis D. Ganoza, former Fortuna CFO; Chairman Jonathan Goodman, co-founder of Fortuna Silver and Executive Chairman of Dundee Corporation; Director Mario Szotlender; and Igor Dutina in Corporate Development. The board's overlap with Dundee is notable given the Dundee debenture being retired in this transaction.
Not disclosed in the provided materials are any production, cost, or capex details for La Plata beyond the August 2024 study, any mine plan update, any offtake or marketing agreement terms, or any ESG metrics despite a "Mining Responsibly" section heading.