Thor Explorations Announces Third Quarter 2026 Financial and Operating Results, for the Three Months Ending September 30, 2026
Thor Explorations reports cash-rich Q3 results despite a 31% output drop and further delays to the Douta permit.
Thor Explorations Ltd. (THX) has released its audited financial results for the third quarter ended 30 September 2026, serving as the financial companion to the operating update published on 14 October 2026. The company reported gold sales of 19,000 oz at an average realized price of US$4,280/oz, generating revenue of US$81.3 million, compared to US$69.9 million in the same period last year. Net profit rose to US$47.3 million from US$43.1 million, while EBITDA increased to US$56.9 million from US$51.4 million.
Production metrics showed a decline, with gold poured falling to 15,515 oz from 22,617 oz in Q3 2025, a decrease of 31.4%. Ore processed totaled 249,607 t at a rate of 2,957 t/d, with a mill feed grade of 2.10 g/t compared to 3.11 g/t in the prior year period. Mill recovery was recorded at 92.8%, down from 94.3%. Ore mined amounted to 303,602 t at 1.69 g/t, compared to 386,558 t at 2.26 g/t in Q3 2025. The company holds a stockpile of 58,322 oz at 0.72 g/t, which it describes as approximately two years of process plant supply.
Cost metrics remained within guidance, with cash operating costs at US$754/oz sold and All-In Sustaining Costs (AISC) at US$993/oz sold, both below the bottom of the US$1,000–1,200/oz guidance band. Adjusted net cash increased to US$236.6 million from US$81.0 million in Q3 2025. Thor Explorations maintained its dividend policy at C$0.0125 per share quarterly and reported zero lost-time injuries.
The company has cut its 2026 production guidance to 70,000–72,000 oz from the previous range of 75,000–85,000 oz, citing severe rainfall at the Segilola mine in late August. AISC guidance for the full year remains at US$1,000–1,200/oz.
At the Douta project, reverse circulation drilling on Bousankhoba continued, with an updated Mineral Resource Estimate targeted for Q4 2026. The Mining Convention is reported to be in the final stages of discussions, though no specific date was provided. At Marahui in Côte d'Ivoire, the company reiterated six headline intercepts previously released on 15 September 2026:
- MRRC26-008: 6 m at 5.60 g/t
- MRRC26-012: 9 m at 5.40 g/t
- MRRC26-115: 6 m at 6.20 g/t
No new assays were introduced in this report.
Thor Explorations Ltd. (THX) saw its stock price decline following the release of updated production guidance. The shares closed at C$1.11 on 13 October, before falling 10.8% to C$0.99 on 14 October, the day the guidance cut was announced. The stock continued to slide, reaching C$0.86 by 3 November, before recovering slightly to C$0.91.
The company’s financial results confirmed strong cash generation. All-in Sustaining Costs (AISC) came in at US$993/oz, sitting 0.7% below the bottom of the guidance band. Net profit rose 9.7% year on year to US$47.3 million, despite selling 3.3% fewer ounces. Adjusted net cash increased 8.2% in a single quarter and 192% year on year, reaching US$236.6 million. Against a market capitalisation of CAD 606.6 million (roughly US$435 million at an assumed 1.39 CAD/USD rate), adjusted net cash represents more than half the equity value. Enterprise value stands at roughly US$198 million against nine-month EBITDA of about US$168 million.
The primary negative development concerns the Douta project. Management had previously stated it expected to reach a specific milestone at the project during Q3 2026, but this target was not met. Douta carries a pre-tax NPV5% of US$908 million at US$3,500/oz, a value more than twice the company’s entire market capitalisation. Management removed the Final Investment Decision (FID) date from its outlook while retaining the phrase "final stages," a move that suggests potential further slippage in the permitting timeline.
Financial results were substantially pre-released on 14 October. Drilling updates relate to September, and the delay on the Douta milestone is an undated miss.
Thor Explorations Ltd. (THX) is a West African gold producer listed on AIM and the TSXV, operating one producing mine and one advanced development project.
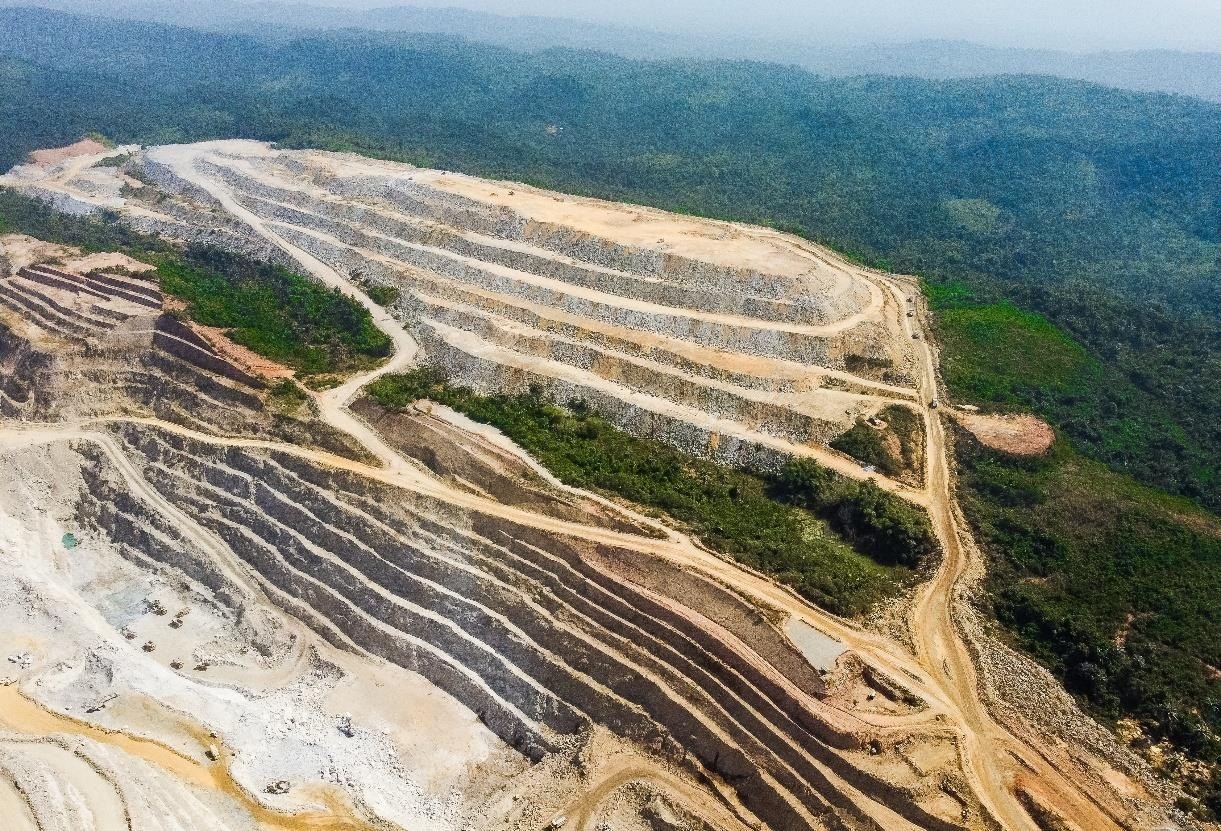
- Segilola (Osun State, Nigeria) — 100% owned, fully permitted, operating open-pit and CIL operation. Sole source of cash flow. Roughly 1.0 Mt/yr milled at a nominal 2,957 t/d. Exploration is testing depth extensions for a potential underground.
- Douta (south-eastern Senegal, Kéniéba Inlier, Demande 11618) — 100% economic interest, PFS complete, ESIA approved January 2026, Mining Convention outstanding, first production targeted early 2028. Senegal expected to hold a 10% free-carried interest.
- Douta-West and Bousankhoba (Senegal) — the remaining 30% of Douta-West was acquired for US$1.5 million at signing and US$3.5 million on a decision to mine plus a 1.25% NSR capped at US$7 million per the January 2026 release; Bousankhoba was described as a 65% initial interest in November 2025 and a 70% interest in April 2026. The discrepancy in the Bousankhoba figure and in the NSR cap (a US$60 million cap appears in the November 2025 release against US$7 million in January 2026) should be reconciled by an investor before relying on either.
- Côte d'Ivoire — Marahui (PR902, 250 km², northeastern Côte d'Ivoire), Guitry, Laoudiba and Boundiali. All early-stage; the 4 km Marahui shear corridor has been tested over roughly 30% of its trend.