Teck Reports Unaudited Third Quarter Results for 2026
Teck reports record copper grades but cuts its cost guidance, masking a third-quarter volume stumble that impacts its operational outlook.
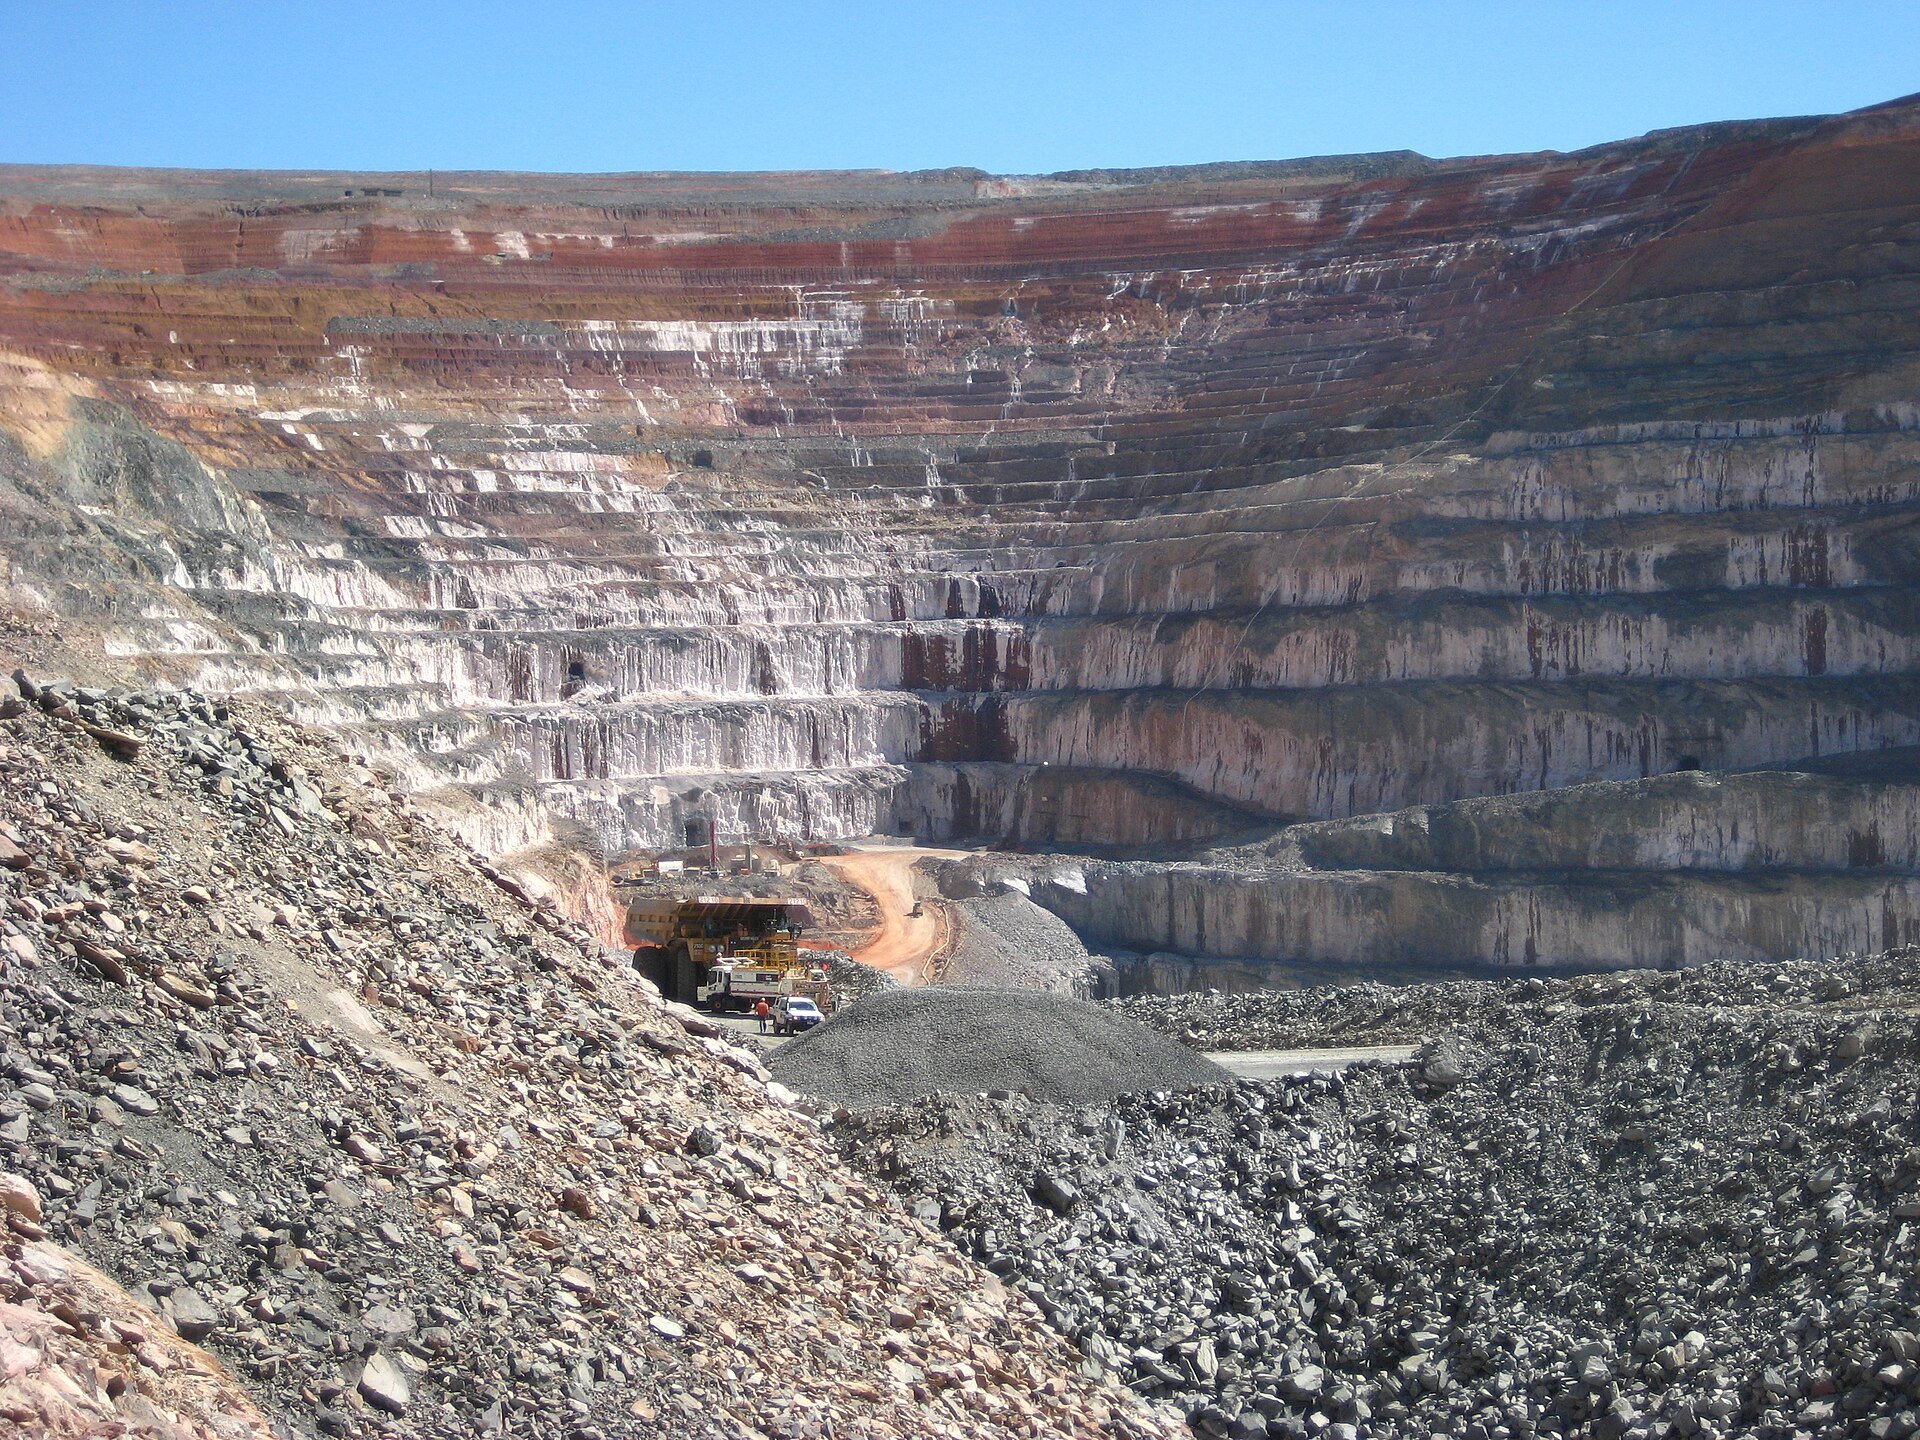
Teck Resources Limited (TECK) reported its third-quarter 2026 unaudited results on October 29, 2026, posting revenue of C$4.517 billion and gross profit of C$1.688 billion. The company reported gross profit before depreciation and amortization of C$2.220 billion, adjusted EBITDA of C$2.305 billion, and adjusted profit of C$923 million, or C$1.88 per share. Cash flow from operations totaled C$1.6 billion.
Profit attributable to shareholders was C$1.592 billion, or C$3.24 per share, a figure that included an C$888 million pre-tax impairment reversal at Trail Operations. After-tax, this reversal contributed approximately C$667 million, or C$1.36 per share. Management’s adjusted figures exclude this item.
Copper production reached 115,700 tonnes, an 11% increase year over year but a 14.9% decline from the 135,900 tonnes produced in the second quarter of 2026. Quarterback produced 47,200 tonnes, up 19% year over year but down 15.4% from the second quarter of 2026.
Copper net cash unit cost was US$1.77 per pound, compared to US$2.09 per pound in the third quarter of 2025, though this was higher than the US$1.64 per pound recorded in the second quarter of 2026. Quarterback’s net cash unit cost was US$2.48 per pound, versus US$1.83 per pound in the second quarter of 2026.
For the full year 2026, Teck maintained its copper production guidance range at 455,000 to 530,000 tonnes and zinc production at 410,000 to 460,000 tonnes. The company lowered its copper net cash cost guidance to US$1.80–2.00 per pound from US$1.85–2.20 per pound. Zinc net cash cost guidance was reduced to US$0.30–0.40 per pound from US$0.65–0.75 per pound, and zinc total cash cost guidance was cut to US$0.70–0.80 per pound from US$0.80–0.90 per pound.
Management stated that 2026 copper production is expected to fall at the low end of the guidance range due to weather impacts at Carmen de Andacollo, while HVC copper, Red Dog zinc, and Trail refined zinc are expected to perform toward the high end.
Capital spending is projected to increase, with sustaining capital expenditure expected in the top half of the C$1.3–1.5 billion range. Capitalized stripping is anticipated at the high end of C$455–560 million, driven in part by the Rock Bench 6 project at Quarterback and diesel costs.
The Anglo American merger remains on track for the original 12–18 month completion window, with the future executive team already named and US$800 million in pre-tax synergies targeted. No new merger economics were disclosed.
Management highlighted record copper prices, 97% growth in adjusted EBITDA, strong cash generation, lower cost guidance, Quarterback tailings management facility reliability, and merger progress. Conversely, the company did not emphasize the quarter-over-quarter decline in copper volumes, the increase in Quarterback’s costs, the low-end copper production outcome, the shift in capital spending to the top half of the range, the delay of the Quarterback tailings management facility’s steady-state timing into 2027, or the HVC strike risk disclosed in a separate October 21 release.
Teck Resources Limited (TECK) reported a 97% year-over-year increase in adjusted EBITDA to C$2.305 billion, while cash flow from operations of C$1.6 billion increased net cash by C$655 million. The company’s balance sheet strengthened, ending with net cash of C$1.899 billion at September 30, 2026.
The company also provided updated cost guidance, cutting the copper cost midpoint by 6.2%, the zinc total cash cost midpoint by 11.8%, and the zinc net cash cost midpoint by 50%. These reductions represent a change to forward earnings expectations, driven largely by by-product prices rather than pure operating improvements.
Despite the positive financial metrics, operating volumes and sales mix disappointed in the third quarter. Adjusted profit of C$923 million was down 2.6% from the C$948 million reported in the second quarter of 2026, even as copper prices rose from US$6.05/lb to a record US$6.40/lb. Q3 copper production fell 14.9% quarter-over-quarter, and Q3 net cash costs rose 35.5% quarter-over-quarter.
The company recorded a non-cash impairment reversal that excluded from adjusted profit but inflated reported earnings per share by C$1.36, bringing reported EPS to C$3.24.
Regarding the merger, the company reaffirmed the exchange ratio, approvals, executive team structure, and synergy targets. This update provided no new information, as the market was already aware of these details.
A material near-term risk involves the HVC strike. A separate release on October 21 indicated the union could strike as early as October 24, 2026. HVC production was expected to contribute toward the high end of the 2026 copper guidance, and a prolonged strike could invalidate that target.
Teck Resources shares had risen from C$84.18 on July 23 to C$99.25 on September 8 before pulling back to C$88.10 on October 28.
Teck Resources Limited (TECK) is a Canadian diversified miner focused on copper and zinc, currently navigating a pending merger of equals with Anglo American to form Anglo Teck. The company’s producing copper assets include Quebrada Blanca in Chile, Highland Valley Copper in British Columbia, Antamina in Peru, where Teck holds a 22.5% interest, and Carmen de Andacollo in Chile. Its zinc operations consist of Red Dog in Alaska and Trail Operations in British Columbia.
The company’s growth and optionality profile includes QB optimization and TMF work, HVC mine-life extension, Red Dog mine-life extension, Trail critical minerals expansion, San Nicolás, Zafranal, Galore Creek, Schaft Creek, and NuevaUnión. The merger would create a top-five global copper producer with more than 70% copper exposure, a primary London listing, and secondary listings in Johannesburg, Toronto, and New York. This context was reaffirmed but not newly negotiated in this release.