Sterling Extends Higher Grade Core of MEPS Copper Zone Intersecting 44.1m of 1.02% CuEq within 187m Near-Surface Interval of Continuous Copper Mineralization
Sterling extends the MEPS core west with a second hole that strays off the high-grade corridor.
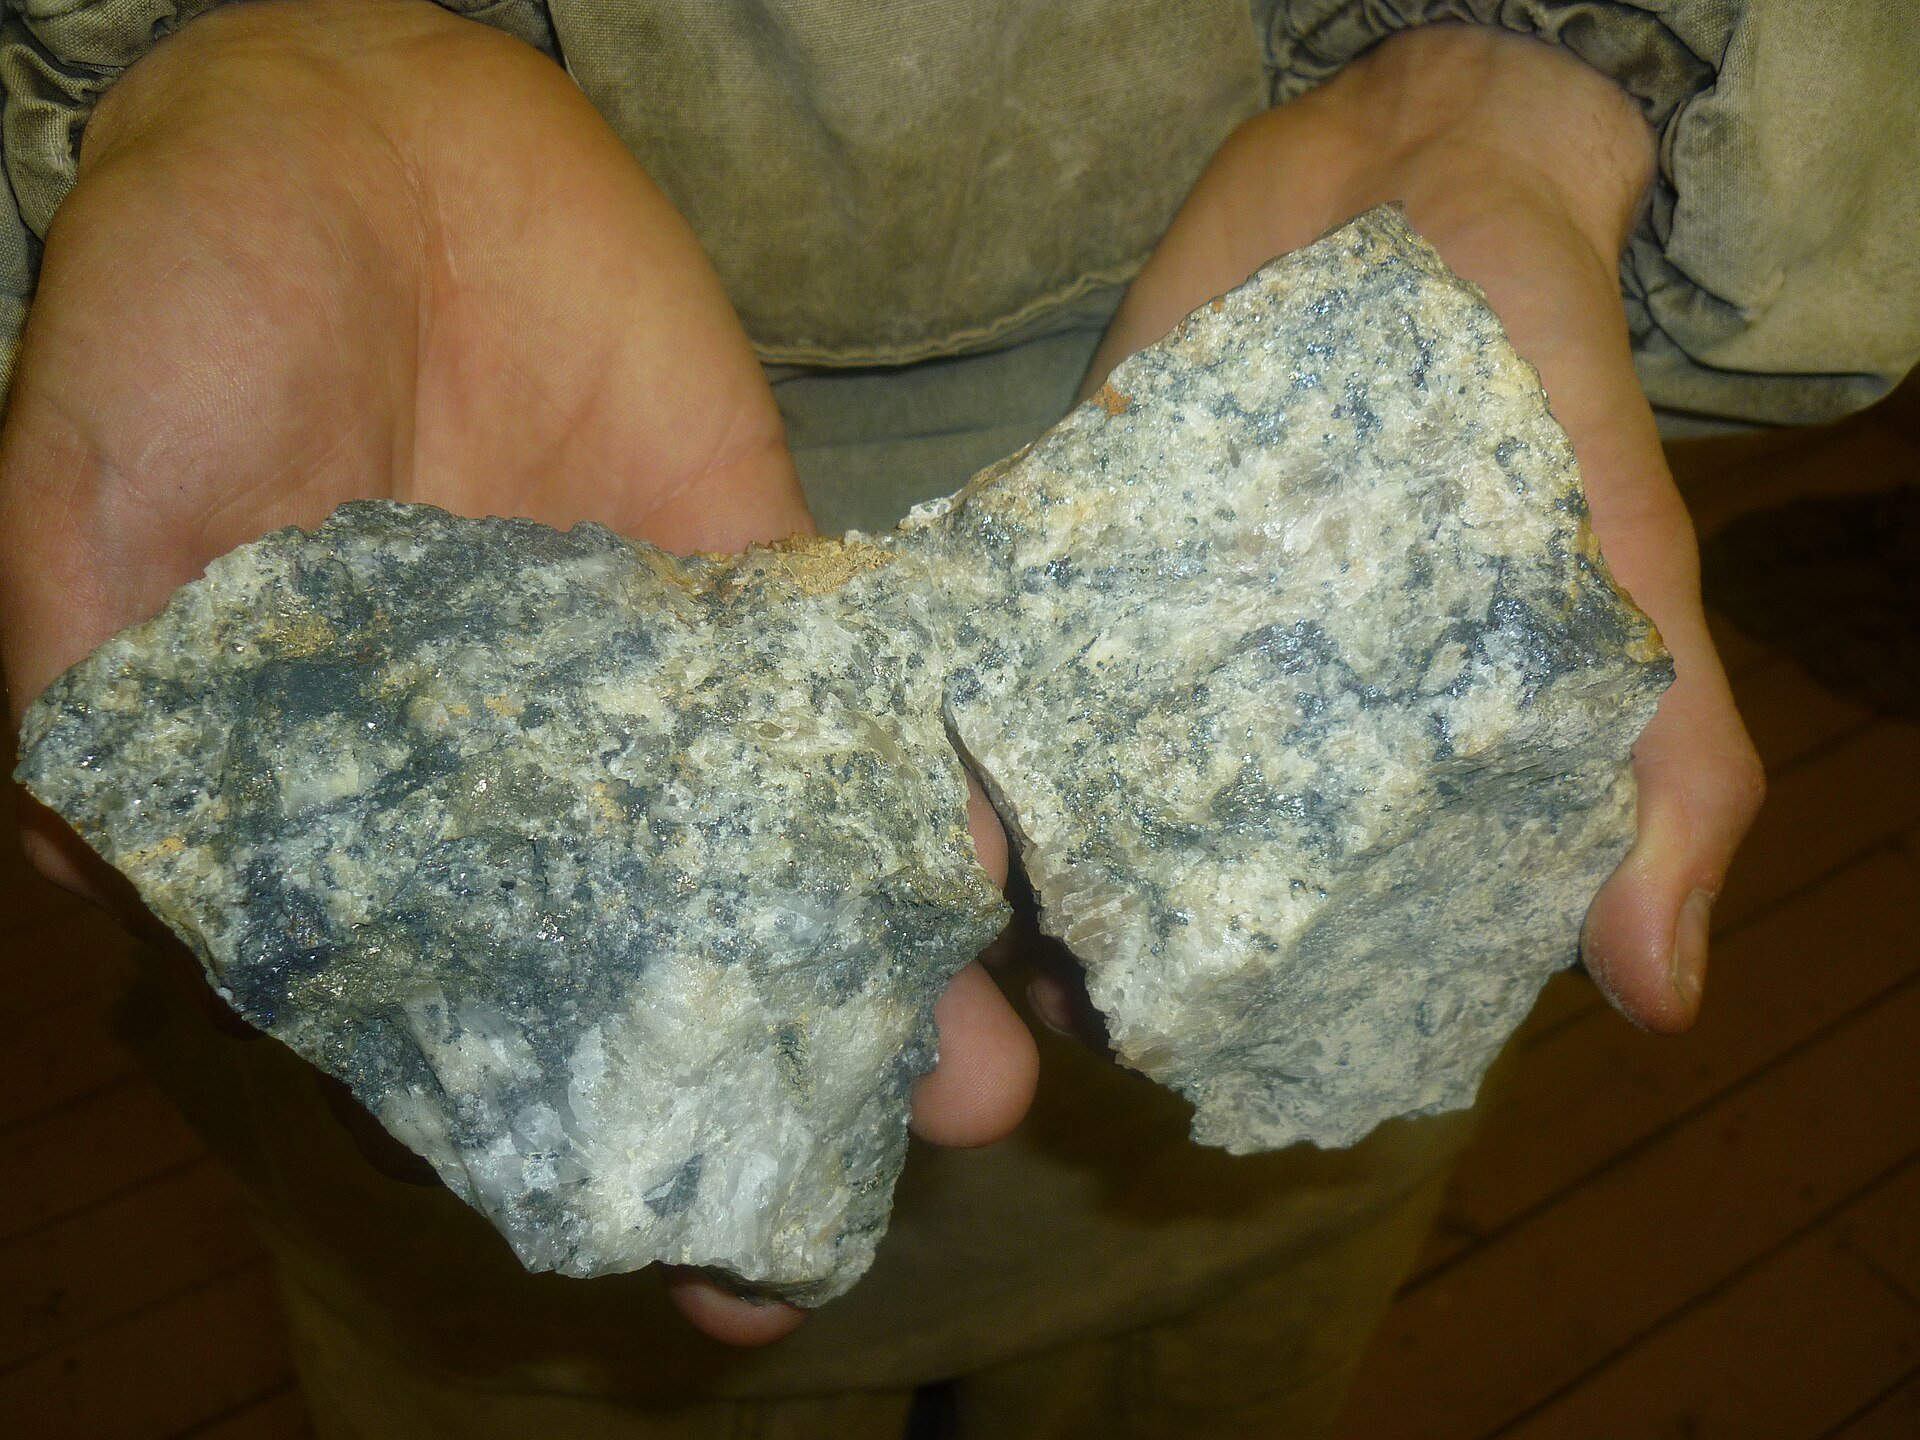
Sterling Metals Corp. (SAG) released assay results for two drill holes, SC-26-27 and SC-26-28, drilled from a single pad on the western side of the MEPS Zone at the Soo Copper Project in Ontario.
SC-26-27, drilled at a dip of -85° and azimuth 75° to a depth of 363m, returned 187.36m grading 0.34% CuEq (0.32% Cu, 0.01 g/t Au, 1.13 g/t Ag, 6 ppm Mo) from 18.64m to 206.0m. This interval includes 44.1m grading 1.02% CuEq (0.96% Cu) from 161.9m to 206.0m, and 18.2m grading 2.02% CuEq (1.92% Cu) from 162.8m to 181.0m. Discrete high-grade samples within SC-26-27 include 0.45m @ 5.64% CuEq (5.35% Cu) at 163.70m, 0.50m @ 6.65% CuEq (6.36% Cu) at 169.00m, and 0.35m @ 5.04% CuEq (4.8% Cu) at 169.50m, all associated with hydrothermal breccia.
SC-26-28, drilled at a dip of -50° and azimuth 30°, returned 271.0m grading 0.21% CuEq (0.19% Cu, 0.02 g/t Au, 0.42 g/t Ag, 7 ppm Mo) from 24.0m to 295.0m. The company noted that SC-26-28 encountered a greater proportion of gabbro, described as a tighter and less favorable host, and intersected the GFP sills where sulfide abundance is interpreted to be lower. Additionally, the shallow dip of the hole stepped it laterally away from the higher-grade copper corridor.
SC-26-27 is reported to extend the continuous higher-grade core zone of MEPS to the west, aligning with the same section as prior holes SC-26-26, SC-26-10, SC-26-13, and SC-26-16.
The 2026 drilling program has completed 53 holes and more than 22,000m, exceeding the stated 20,000m minimum. Drilling continues with no plans to stop. The company reiterated that the reported intervals may not represent true widths, that true widths are not yet known, and that capping has not been applied to grades.
Sterling Metals Corp. (SAG) is a grassroots, pre-resource explorer with no established mineral resource, reserve, or economic study. The company is pre-revenue, carries an explicit going-concern flag in its latest MD&A, and holds approximately C$10.2 million in working capital against a market capitalization exceeding C$56 million. At this stage, materiality is defined by results that grow the perceived system or de-risk it.
The recent drilling represents a modest westward extension of the previously identified higher-grade core on the already-drilled western section. This is an incremental finding that does not add a new zone, a new intrusive centre, or a step-change in vertical or along-strike extent. The overall scale of the system, characterized by an approximate 1.3km by 600m footprint and a 700m continuous core, remains unchanged by this hole.
The discovery hole MEPS-25-02, which returned 262.5m @ 1.05% CuEq, previously drove the stock to a 52-week high of C$3.06 in September and October 2025. Since then, the equity has declined approximately 64% to C$1.10, despite the 2026 programme delivering several larger intervals. The stock has not re-rated on the 2026 drilling, drifting down from approximately C$2.00 in January 2026 to its current level. Consequently, the price currently assumes little about repetition, and a materially better-than-demonstrated result would be a genuine positive.
Recent results show SC-26-27’s high-grade core of 18.2m @ 2.02% CuEq is competitive to slightly better in grade than SC-26-26’s sub-intervals, but materially weaker on width and the broad envelope. In a bulk system, interval length varies with collar position and hole orientation, so the shorter run is not, by itself, disqualifying. The result is neither materially better than anything previously demonstrated nor materially worse than the anchor, landing as routine, expected confirmation that slightly extends the western higher-grade core with real grade.
Key drill intercepts include: * MEPS-25-02: 262.5m @ 1.05% CuEq * SC-26-13: 445m @ 0.40% CuEq * SC-26-26: 397m @ 0.37% CuEq, including 200m @ 0.53% CuEq * SC-26-27: 18.2m @ 2.02% CuEq * SC-26-26 sub-intervals: 29.9m @ 1.08% CuEq; 13.25m @ 1.82% CuEq * SC-26-26 broad envelope: 397m @ 0.37% CuEq * SC-26-27 broad envelope: 187m @ 0.34% CuEq
Sterling Metals Corp. (TSXV: SAG / OTCQB: SAGGF), a Canadian copper-focused explorer, is the 100% owner of the 35,000+ hectare Soo Copper Project in the Batchewana Copper Belt near Sault Ste. Marie, Ontario, as well as the Adeline sediment-hosted copper-silver project in Labrador. The company completed the QcX Gold acquisition on Aug 31, 2026, which expanded its land package by approximately 40% and added the former QcX CEO to the board. The transaction involved the issuance of approximately 4.92 million shares and associated warrants/options, resulting in former QcX holders owning approximately 9.6% of the company.
The Soo Copper Project benefits from strong infrastructure, located 20 minutes from the Trans-Canada Highway, one hour north of Sault Ste. Marie, and 20km from rail and deep-water access, allowing for year-round drilling. In contrast, the Adeline project has been impaired to C$1 in the accounts with no near-term work planned. Additionally, the Sail Pond project was sold in exchange for 96,078 shares of the purchaser.
In prior-period context not disclosed in today's release, Sterling Metals reported a Q1-2026 net loss of C$233,243, compared to C$992,554 a year earlier. The company held working capital of approximately C$10.2 million and cash of C$11.13 million as of Mar 31, 2026, with no debt. The book value per share stood at C$0.54. The latest MD&A flagged an explicit going-concern uncertainty, and the company expects to incur approximately C$4.29 million in flow-through expenditure by Dec 31, 2026.