Capstone Copper Provides Update on Operations
Capstone cuts guidance floor to 195kt and delays Pinto Valley to mid-December as a Chile strike looms.
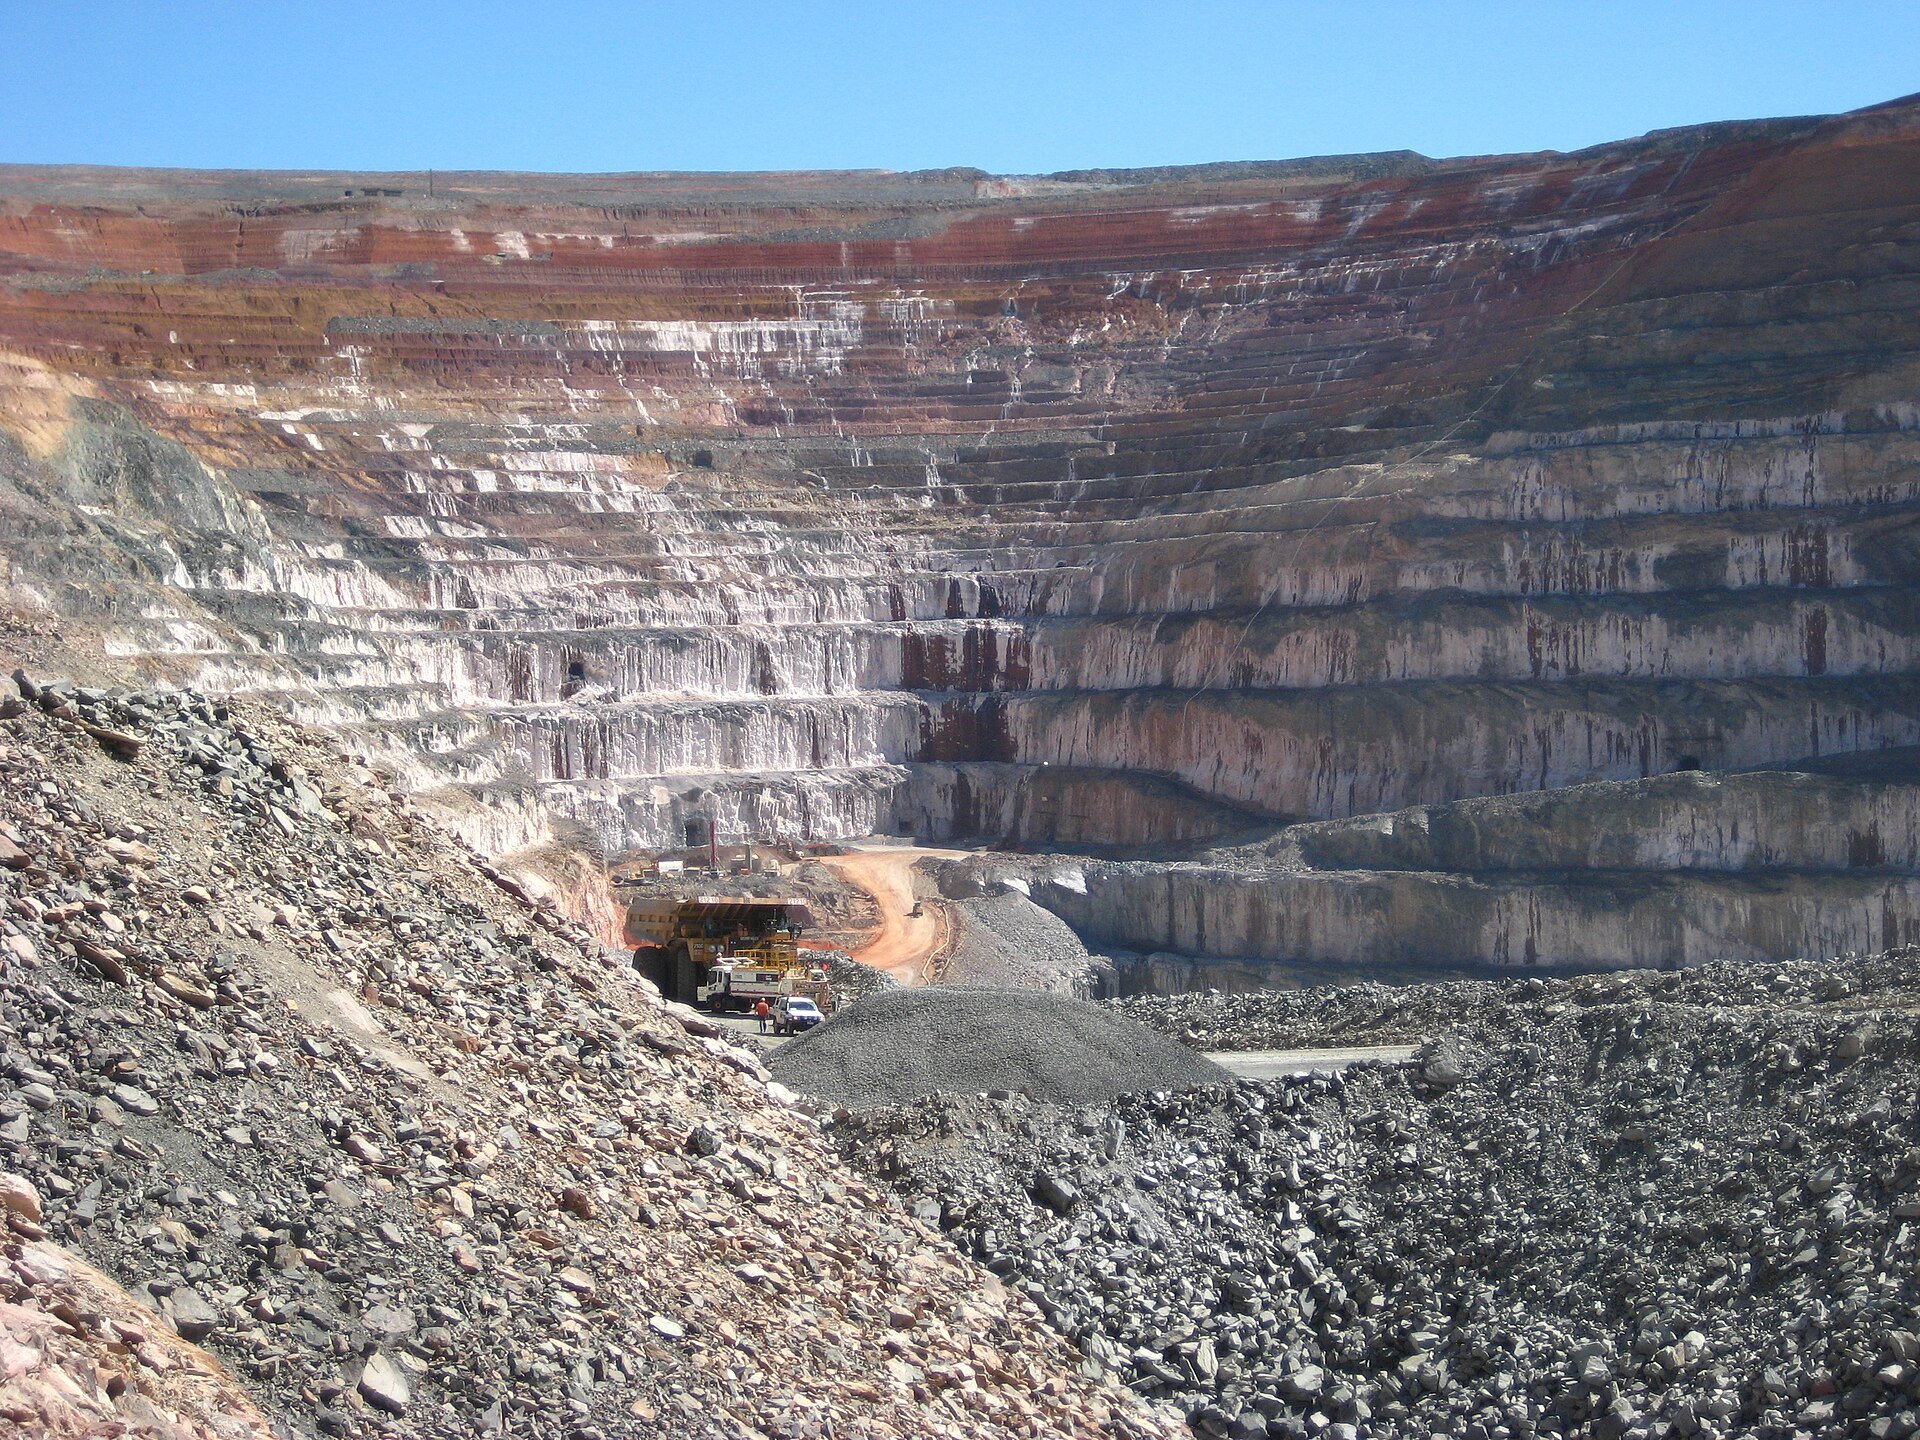
Capstone Copper Corp. (CS) has delayed the recommissioning of its Pinto Valley primary crusher to mid-December 2026, a shift from the previous expectation of an early November restart. The delay stems from the need for additional maintenance on major mechanical components identified during commissioning, with replacement parts currently being manufactured off-site by the original equipment manufacturer.
To mitigate the impact, the company is redeploying temporary mobile crushing equipment to allow a partial concentrator restart in mid-November. This interim configuration is expected to handle up to 40,000 tonnes per day, though no nameplate figure, recovery rate, or grade penalty has been quantified for this setup. Consequently, Capstone Copper estimates a production shortfall of approximately 5,000 tonnes of copper for 2026, a figure that depends on the timing of the interim restart and the eventual recommissioning of the primary crusher.
The company has adjusted its 2026 consolidated copper guidance, cutting the bottom end to 195,000 tonnes from 50,000 tonnes. Based on the third-quarter release, the guidance range is now 195,000–230,000 tonnes.
Management has also flagged risks associated with a national strike by Chilean trucking associations over fuel prices. The strike threatens to suspend concentrate and cathode shipments and disrupt the delivery of fuel and sulphuric acid. However, the Mantoverde and Mantos Blancos operations are currently unimpacted due to pre-strike preventative measures and on-site storage.
The 2026 guidance still includes a full year of production from Cozamin, which is pending sale to Luca Mining as announced on 21 September 2026. The release did not provide updates to C1 cash cost guidance, the $830 million capital expenditure budget, or the MV Optimized ramp. It also did not quantify the impact of the truckers' strike, revise quarterly phasing, or mention the criminal document demand served on the Cozamin subsidiary.
Capstone Copper Corp. (CS) reported a production shortfall of approximately 5,000 tonnes, representing about 2.3% of the original 215,000-tonne midpoint guidance. At the realized price of $6.61/lb in Q3, this volume loss equates to roughly $40–45 million in revenue. While this figure is small relative to the company’s C$8.8 billion market capitalization, the impact on the guidance range and the credibility of the production sequence is more significant.
The company has breached the low end of its production range for the second time in a month. Following Q3 guidance that pointed to the "low end," this release cuts that low end. The retained top end of 230,000 tonnes is arithmetically unreachable given that production in the first nine months of 2026 was 144,937 tonnes. Achieving 230,000 tonnes would require 85,063 tonnes in Q4, which is 46% above the all-time record quarter of 58,273 tonnes. Even hitting 195,000 tonnes would require 50,063 tonnes in Q4, an 11% quarter-over-quarter increase, during a period when the company’s second-largest sulphide mine was offline. Effectively, the guidance range is now approximately 195,000–202,000 tonnes.
The Chilean truckers' strike introduces new variables not previously modeled. Mantoverde and Mantos Blancos account for roughly 100,000–118,000 tonnes of the original 200,000–230,000-tonne guide, representing broadly half of group output and the large majority of group margin given Pinto Valley's cost position. A shipment and consumables interruption at these assets presents a larger swing factor than the 5,000-tonne shortfall in Arizona. Management quantifies the impact as zero, an assertion rather than a calculated number.
Cost transmission remains undisclosed. The company cut volumes at the mine with the highest unit cost without restating C1 costs. Q3 C1 was $2.95/lb against a $2.60/lb guidance midpoint, and the nine-month weighted average is approximately $2.81/lb. To land inside the $2.45–$2.75/lb range at 195,000 tonnes, Q4 would need to achieve roughly $2.58/lb, a 12% sequential decline, even as a high-cost mine operates on mobile crushers. The $2.75/lb ceiling now appears to function as a floor.
The stock has fallen from C$16.62 on 24-Aug-2026 to C$11.49, a 31% drawdown. It drifted from C$11.77 on the Q3 print to C$11.49 into this release, with an intraday low of C$10.73 on 5-Nov. While some operational slippage was clearly discounted, a sovereign-level logistics disruption in Chile layered on top of a guidance cut was not. This occurs in a company whose Q4 was explicitly presented to investors as the strongest quarter of the year.
Capstone Copper Corp. (TSX: CS, ASX: CSC) is a Vancouver-headquartered copper producer focused on operations across the Americas. The company’s portfolio includes the Pinto Valley mine in Arizona, a copper-sulphide operation transitioning from underground to open-pit methods that represents the group’s highest-cost and most technically challenging unit. In Mexico, the Cozamin copper-silver asset in Zacatecas is being divested to Luca Mining for up to $385 million. In Chile, the company operates the Mantos Blancos copper-silver sulphide and cathode facility in Antofagasta, alongside the Mantoverve copper-gold sulphide and cathode mine in Atacama, which serves as the flagship growth engine.
The company’s growth pipeline centers on consolidating its Chilean district to run at scale using shared infrastructure, a strategy funded in part by the divestment of the Mexican asset. Key projects include the Mantoverde Optimized brownfield expansion, featuring a $176 million investment and a 45,000 tpd design that targets approximately 20,000 tonnes per year of incremental copper and 6,000 ounces per year of gold. Additional initiatives include the MV Pyrite Augmentation project, costing $45 million, which aims to reduce acid production by approximately 20% and add roughly 3,500 tonnes per year of cathode production, with an estimated NPV of $200–320 million.
Further development includes the fully permitted Santo Domingo copper-iron-gold project, in which Capstone holds a 25% stake alongside Orion, with a final investment decision targeted for the first quarter of 2027. The company is also advancing the Sierra Norte project and has acquired San Pietro, a 16,000-hectare property that connects the Mantoverde and Santo Domingo districts.