Drill Results
Cosa Intersects Anomalous Radioactivity and Additional Prospective Geology at Darby Joint Venture with Denison Mines
Darby summer program returns structure only — zero assays, both trends missed by ~30 m
Executive Summary
- Program: four diamond holes, 2,741 m total, summer 2026 at the Darby JV (Cosa 70% / Denison 30%), 10 km west of Cigar Lake. Two holes at the Gamma trend, two at Bravo (helicopter-supported).
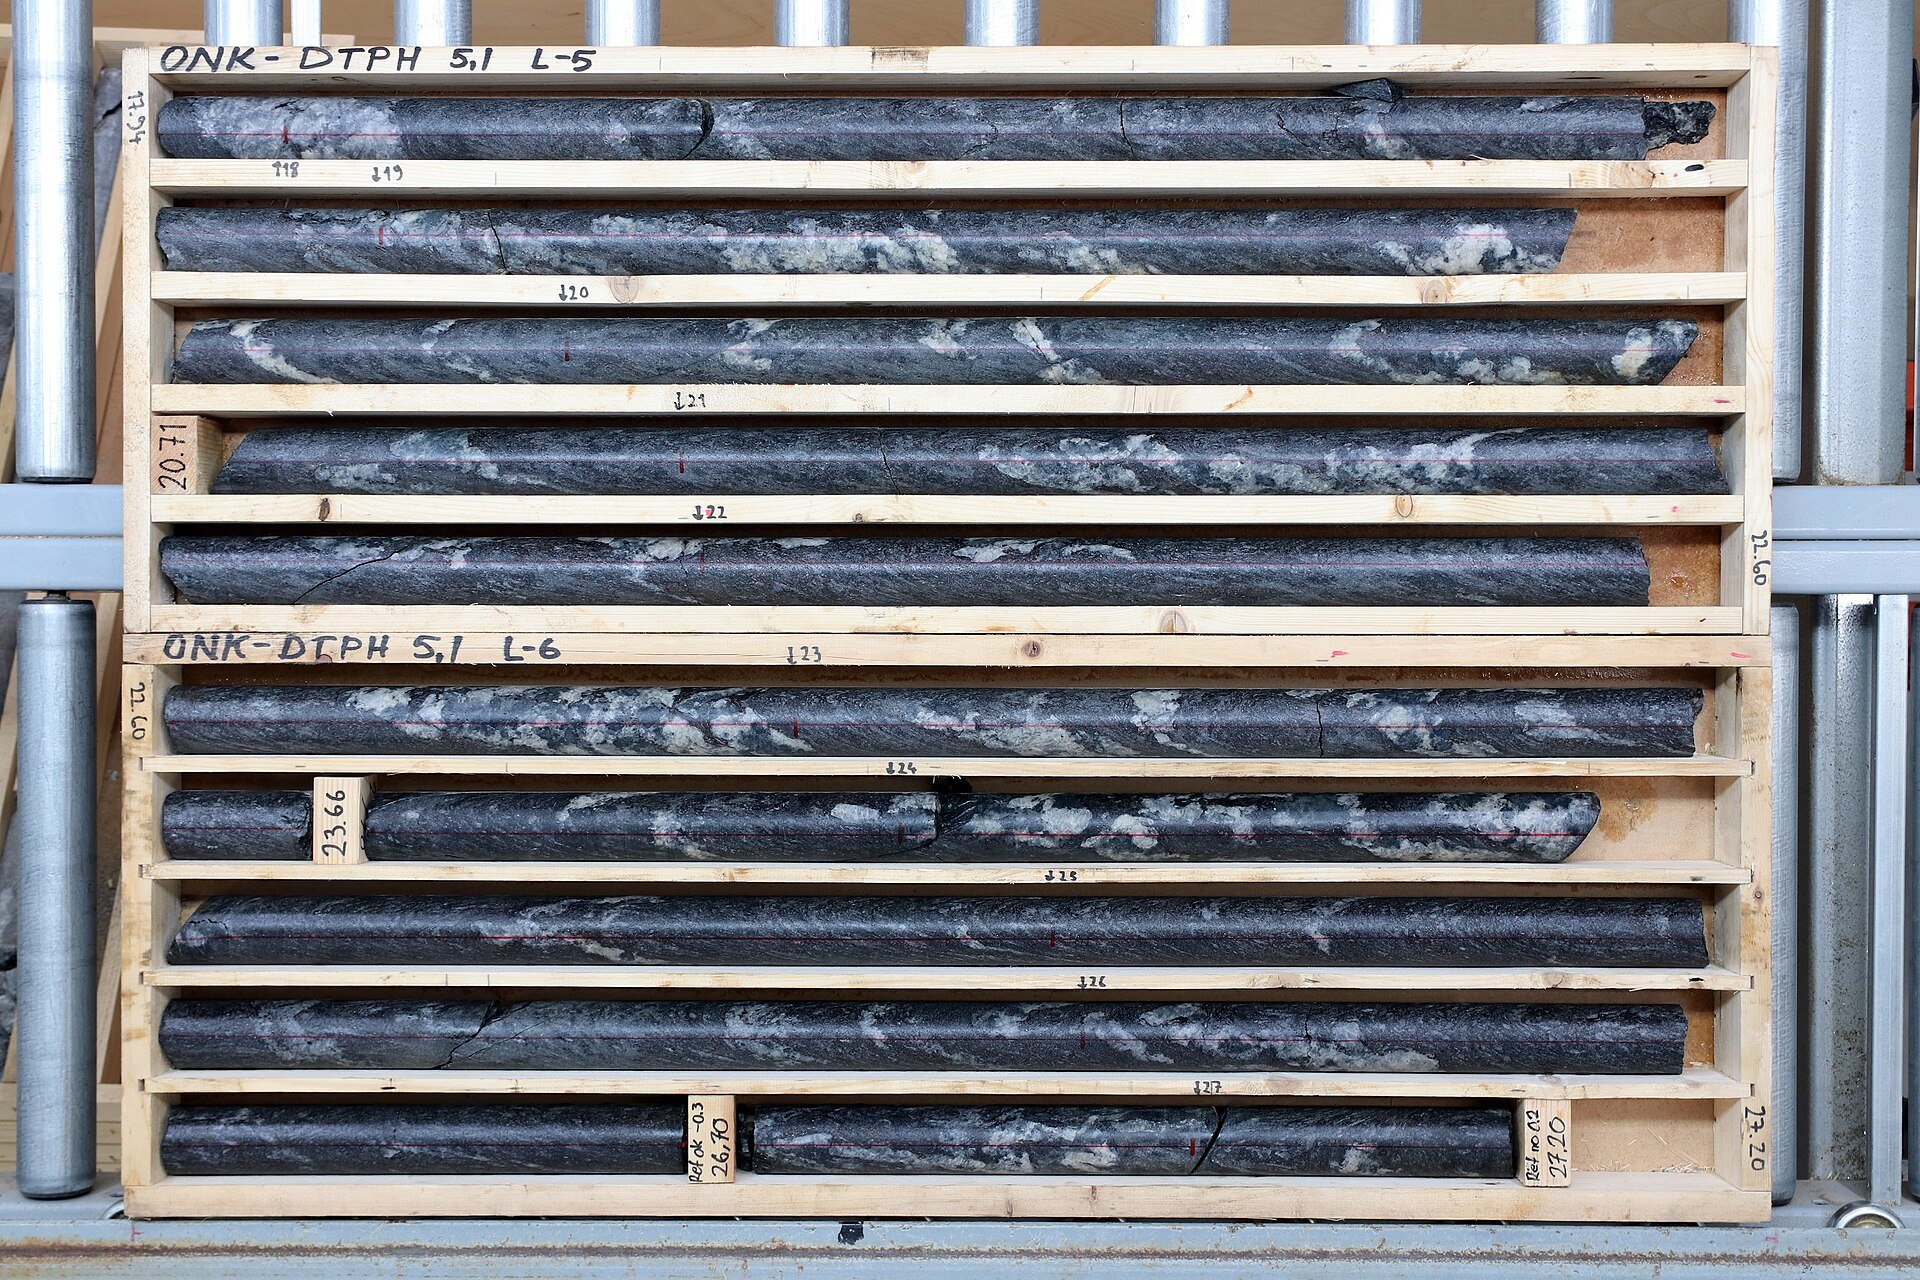
- Gamma — DB26-43: multiple zones of moderate-to-strong faulting and alteration in the lower sandstone plus localised basement faulting; unconformity intersected 22 m lower than winter hole DB26-41, taking total unconformity relief on section to 57 m. Anomalous radioactivity of 950 cps over 0.5 m (689.0–689.5 m), 33 m below the unconformity, associated with hematite, limonite and argillization.
- Gamma — DB26-45: drilled 1,600 m south along strike to follow up historical hole DB-23R; intersected a 37 m interval of faulting in the upper sandstone, interpreted as a possible additional untested structure. Both DB-23R and DB26-45 "may be overshots" of an untested package.
- Bravo — DB26-44: followed up historical DB-12; unconformity intersected 41 m lower than DB-12; lower sandstone contains faulting and alteration; interpreted as a near-miss overshot of the ideal target by ~30 m.
- Bravo — DB26-46: 800 m east along strike; weakly bleached lower sandstone above the unconformity at 516.1 m; variably graphitic gneiss from 542 to 568 m (26 m) is faulted with weak-to-moderate hydrothermal alteration; interpreted to have undershot the optimal target by ~30 m.
- Assays: no chemical assay results are reported for any of the four holes. The company states it "awaits geochemical assays to further vector drilling."
- Next steps: fully funded follow-up in early 2027, prioritising Gamma; simultaneous drilling at Darby and Murphy Lake North tentatively January 2027.
Material Impact
- Stage weighting: pre-resource explorer, no resource, no PEA, no revenue — market cap ~C$41.6M on 134.2M shares. At this stage a genuine discovery or step-change hole would be highly material. This release contains no assay, no mineralised intercept, no new zone with grade, and no increase in the known extent of uranium mineralisation anywhere.
- What actually changed: the company now knows two more places where the target horizon is not. Unconformity relief on the Gamma section rose from 35 m to 57 m; two Bravo holes bracketed a graphitic horizon. Understanding improved; the asset did not.
- Versus embedded expectations: Darby was never priced as a discovery. The market's Darby expectation was set by the winter 2026 programme — 103.5 m at 5.6 ppm U (i.e. anomalous geochemistry, not mineralisation) at Charlie, and structure/alteration at Gamma. Today's release does not even clear that low bar in metal terms, since winter at least produced assayed uranium values and today produced none. The stock's decline from C$0.79 (April) to C$0.31 (now) is about Murphy Lake North fading and about financing dilution, not about Darby; Darby contributes little embedded expectation, which caps the damage but also removes any positive surprise.
- Expected share-price reaction: flat to modestly negative (0 to −7%). There is no new number to re-rate and no failure of a priced-in thesis.
- Prior-period context — not disclosed in today's release: cash C$18.0M and working capital C$14.2M at June 30, 2026, against a half-year operating cash outflow of C$4.1M and a stated going-concern material uncertainty; a $12.7M flow-through expenditure obligation by December 31, 2027; and a $5.0M Darby commitment by June 30, 2029 (C$1.9M spent to that date). The Darby spend is a contractual obligation being serviced, not a return-generating investment so far.
COSA · Price
Company Overview
- Cosa Resources Corp. (TSXV: COSA; OTCQB: COSAF; FSE: SSKU) — Vancouver-headquartered, exploration-stage uranium company with ~237,000 ha across the Athabasca Basin, Saskatchewan. No revenue, no resources, no reserves, no economic studies, no production.
- Key assets: Murphy Lake North (70% Cosa / 30% Denison, 1,876 ha, 3 km east of IsoEnergy's Hurricane deposit) — the only project with a genuine assayed uranium intercept (MLN26-013: 5.0 m @ 0.55% U3O8 incl. 0.5 m @ 1.70%, plus 4.09% Ni and 1.73% Co). Darby (70/30 with Denison, 18,829 ha, 10 km west of Cigar Lake) — multiple trends, historical weak mineralisation, structure/alteration, no assayed discovery. Packrat (70/30). Ursa (100%, 60,599 ha). Astro (option to Global Uranium, up to 80%). Aurora (option to Traction Uranium, up to 80%). Plus Orion, Charcoal, Castor, Orbit, Cosmo, Highway, Heron (100%).
- Balance sheet (June 30, 2026): cash C$18.0M, working capital C$14.2M, total assets C$26.9M, no debt, equity C$20.4M, book value ~C$0.15/share. H1 2026 net loss C$3.39M; operating cash outflow C$4.10M. Shares out 134.24M (plus 18.21M warrants, 10.09M options — heavily diluted capital structure).
- Governance/technical: CEO Keith Bodnarchuk; VP Exploration Andy Carmichael, P.Geo. (QP); VP Corporate Development Justin Rodko, P.Geo. Team carries Hurricane/Gryphon discovery credentials. Denison is largest shareholder (~18.9% partially diluted) and JV partner.
- Commitments: $5.0M Darby exploration by June 30, 2029 (C$1.9M spent); $1.5M MLN sole-fund (met); $12.7M flow-through expenditures by Dec 31, 2027; remaining deferred consideration to Denison fully satisfied post-quarter in shares.
More from Cosa Resources Corp.
Oct 19, 2026 · 08:01