Capstone Copper Announces Sale of Cozamin for Total Consideration of up to $385 Million
Capstone exits Cozamin for up to $385m, cutting net debt 40% before final investment decision.
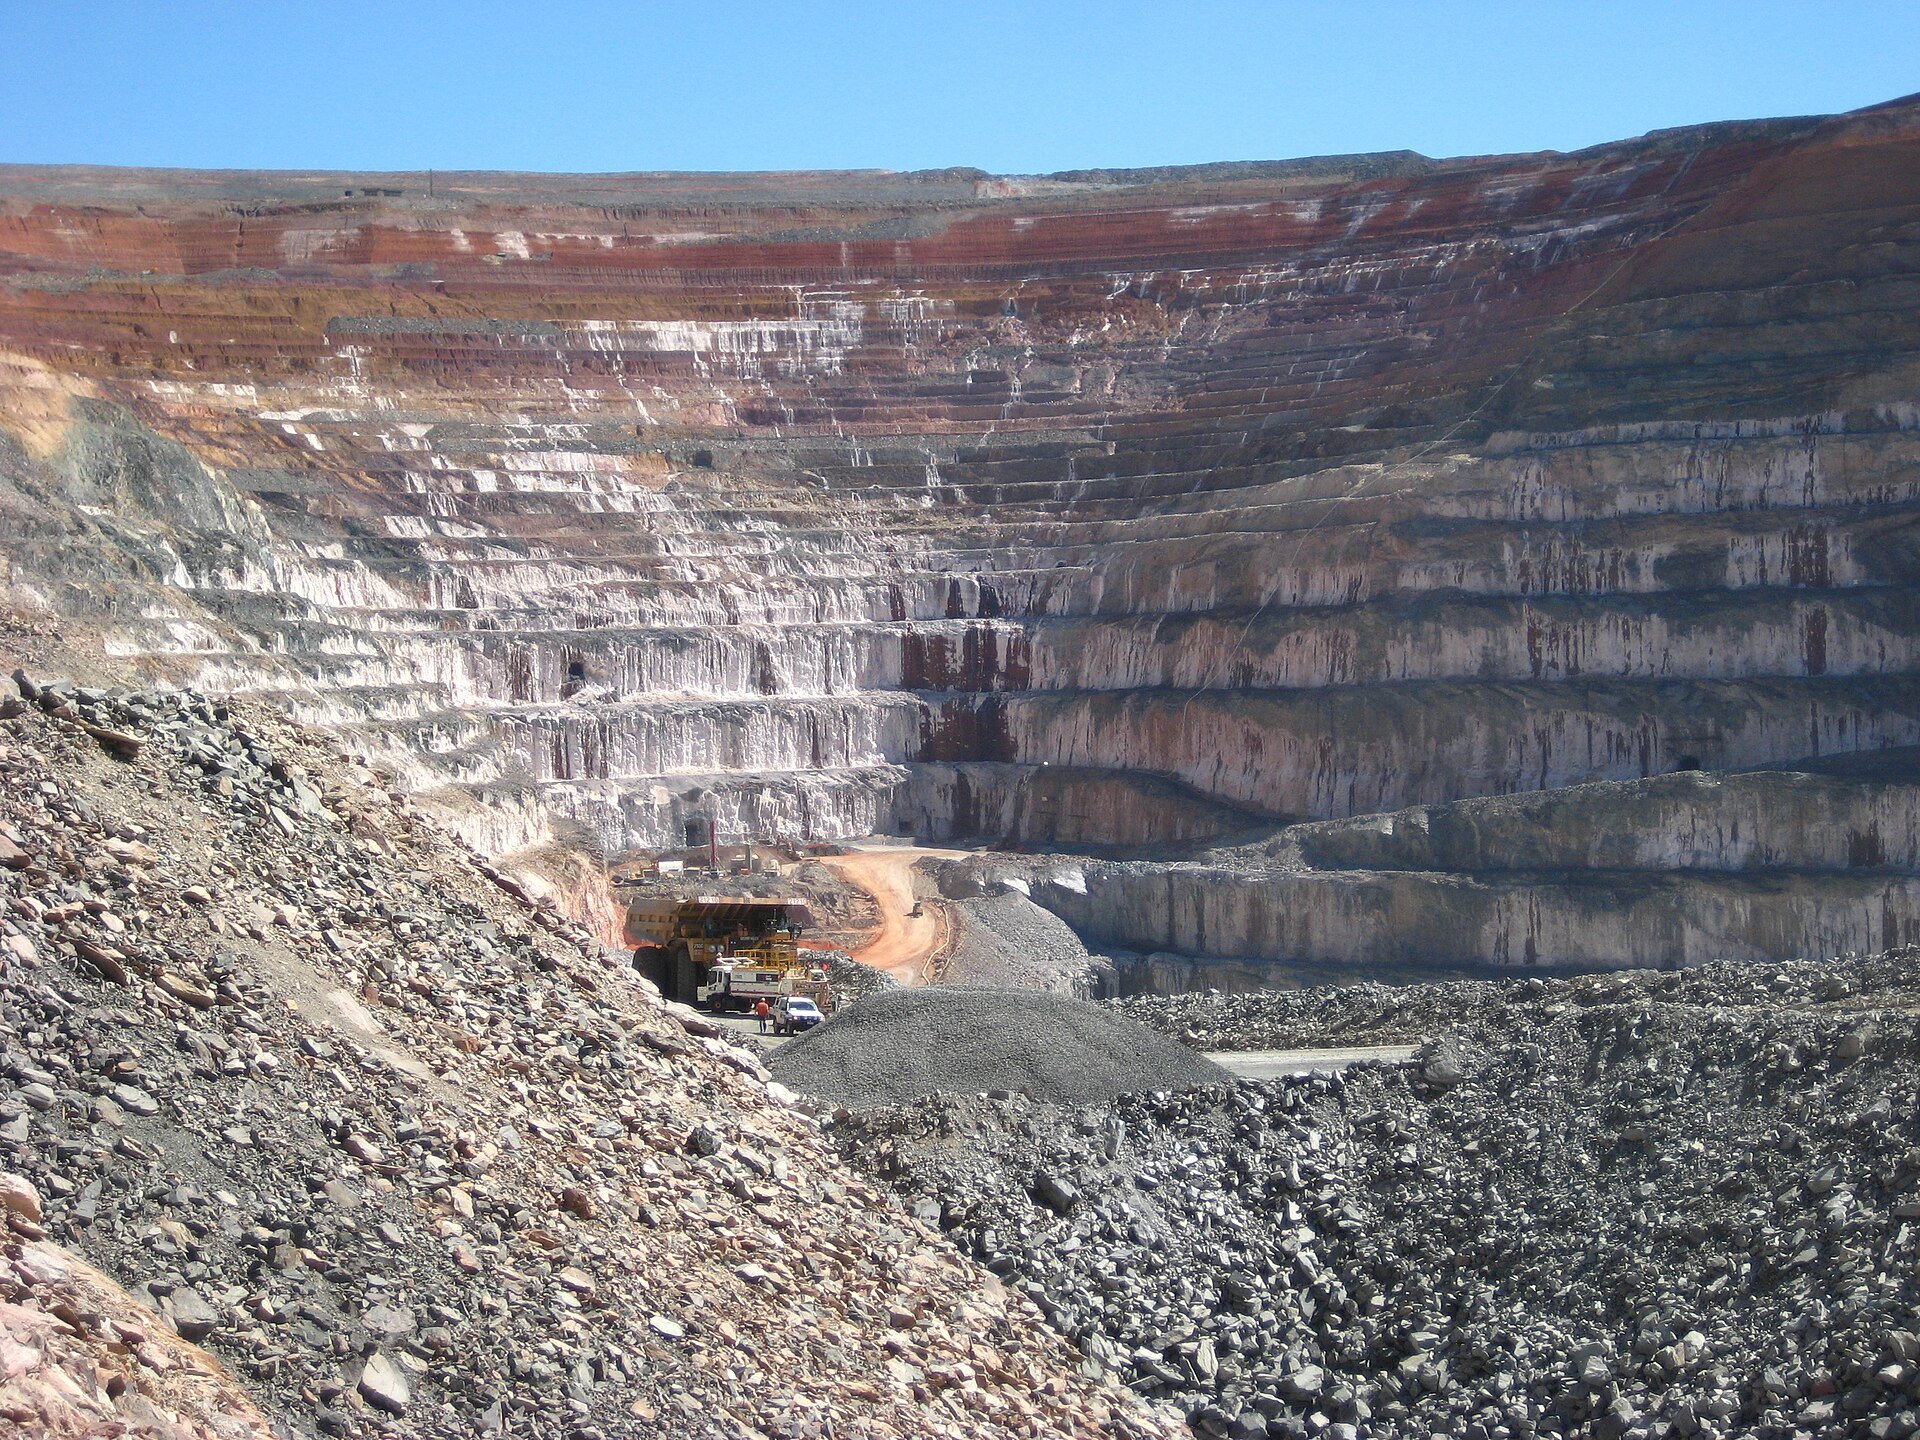
Capstone Copper Corp. (CS) has signed a definitive agreement to sell 100% of the Cozamin copper-silver-zinc-lead mine in Zacatecas, Mexico, to Luca Mining Corp. (TSXV:LUCA, OTCQX:LUCMF, Frankfurt:Z68) for total consideration of up to US$385 million. The transaction structure includes US$275 million in upfront cash, based on an October 31, 2026 lock-box date on a cash-free and debt-free basis and assuming normalized working capital, subject to customary closing adjustments. Additionally, the deal includes US$15 million in Luca shares issued at closing and US$35 million deferred, payable on the first anniversary of closing in cash and/or Luca shares at Luca's option.
Up to US$60 million in contingent cash is payable after each of the 2027, 2028, and 2029 calendar years, based on the annual average LME copper price. The contingent tiers are structured as follows: - US$10 million if the price is US$7.00-7.75/lb - US$15 million if the price is US$7.76-8.50/lb - US$20 million if the price is at least US$8.51/lb
The base-case consideration is US$325 million, comprising the upfront cash, closing shares, and deferred payment. At the Q2-2026 realized copper price of US$6.22/lb, the contingent tiers—which start at US$7.00/lb, roughly 13% above that realized price—would not be triggered.
The sale is subject to customary conditions, including stock exchange and Mexican National Antitrust Commission approval. It is explicitly not subject to shareholder approval or any financing condition. Capstone targets a close in Q4 2026. The company stated that the proceeds will be used to strengthen the balance sheet and provide financial flexibility to redeploy capital into high-return growth projects in Chile and the United States.
Capstone will retain equity exposure to Luca, including the US$15 million in shares at closing and the possibility of deferred shares, which the company framed as retaining "exposure to the exploration upside at Cozamin." No retained royalty, stream, offtake, or back-in right is disclosed. The release did not disclose Cozamin's mineral reserves and resources, mine life, current production and cost contribution, the implied transaction multiple, any book gain or loss on disposal, any tax leakage on the sale, Luca's funding plan or balance sheet, or the impact on Capstone's 2026 and 2027 production guidance.
Capstone Copper Corp. (CS) has entered into a definitive agreement to sell its Cozamin asset, a transaction that will close in the fourth quarter of 2026. The deal involves US$275 million in upfront cash, representing 41% of the company’s net debt of US$674.9 million and 75% of its cash on hand of US$367.1 million, based on prior-period context as of June 30, 2026. Pro forma net debt is expected to fall to approximately US$400 million, with net leverage decreasing from roughly 0.48x to 0.28x against annualized second-quarter 2026 adjusted EBITDA.
On a per-share basis, the maximum consideration amounts to approximately US$0.50, with upfront cash valued at about US$0.36 per share, based on 763,949,339 shares outstanding. This represents a mid-single-digit percentage of the company’s market capitalization. The transaction marks a shift from the second-quarter 2026 call, which indicated a sale was possible but uncommitted. The signed definitive agreement includes a disclosed price and structure, carries no financing condition, and is scheduled to close in the fourth quarter of 2026. The release landed after the last market data point of September 18, 2026, meaning the market has not yet priced the move.
The transaction offers several positive vectors, including a material credit improvement ahead of the Santo Domingo Final Investment Decision. At the time of the October 13, 2025 release, Capstone’s estimated equity share of construction capital was approximately US$400 million. The sale also removes a small Mexican operating liability from a management team focused on Chile and Arizona. Additionally, the company is recycling capital from an asset into which it was choosing not to reinvest; only US$2 million of the US$70 million 2026 exploration budget was allocated to Cozamin, the smallest allocation in the portfolio, and the asset received no line item in the US$225 million 2026 stripping budget.
However, there are negative vectors to consider. The realistic base case for the sale is US$325 million, rather than the maximum consideration of US$385 million. Approximately 13% of the maximum consideration, or US$50 million, is dependent on a junior counterparty’s equity value and one-year credit, with the deferred tranche payable in Luca shares at Luca’s option. Capstone retains no royalty or stream on Cozamin, effectively giving up all future reserve conversion at the asset in exchange for equity in a small operator. Furthermore, no reserves, mine life, or transaction multiple are disclosed, leaving the price unvalidated.
An important quantitative deduction from the release involves consolidated volumes. Cozamin was guided to produce 21,000 to 24,000 tonnes of copper in 2026 at a C1 cost of US$1.55 to US$1.85 per pound, representing about 10% of consolidated volumes and one of the lowest-cost units, with a second-quarter 2026 C1 of US$1.52 per pound. Mantoverde Optimized is expected to add roughly 20,000 tonnes per year once ramped in early 2027. These figures nearly cancel each other out, suggesting that 2027 consolidated volumes will look close to flat excluding Cozamin versus 2026, despite the release’s framing of the deal as "transformational copper growth."
Capstone Copper Corp. (TSX:CS; ASX:CSC), a Vancouver-headquartered producer focused on the Americas, had 763,949,339 shares outstanding as of June 30, 2026. The company’s operating assets include Mantoverde in Atacama, Chile, which targets 64,000-74,000t of sulphide copper at US$1.25-1.55/lb C1 costs, plus 25,000-28,000t of cathode; Mantos Blancos in Antofagasta, Chile, targeting 38,000-44,000t of copper-silver sulphide at US$2.85-3.15/lb plus 10,000-12,000t of cathode; and Pinto Valley in Arizona, USA, targeting 42,000-48,000t at US$3.00-3.30/lb. The company is also selling its Cozamin asset in Zacatecas, Mexico, which targets 21,000-24,000t at US$1.55-1.85/lb.
The growth pipeline includes the fully permitted Santo Domingo project, located roughly 35km northeast of Mantoverde, with a final investment decision targeted for Q4 2026. Orion holds a 25% stake in the project for up to US$360M, leaving Capstone’s estimated equity share of construction capital at about US$400M. Other pipeline assets include Sierra Norte, which carries an ENAMI option over more than 18,000ha, and San Pietro, acquired on August 31, 2026, for 2,034,970 shares at a deemed C$15.77, adding roughly 16,000ha adjacent to Santo Domingo.
Near-term optimization efforts include the Mantoverde Optimized project, costing US$176M, which is expected to add roughly 20,000t of copper and 6,000oz of gold per year, extending the mine life to 25 years with tie-ins scheduled for September 2026. The Mantoverde Pyrite Augmentation project, valued at US$45M and expected in early 2028, aims to reduce acid consumption by about 20% and add roughly 3.5kt/yr of copper. Additionally, the Mantos Blancos Phase II project aims to increase throughput from 20,000 to at least 27,000tpd, with a pre-feasibility study due by the end of 2026 and expanded output targeted for 2030-2031.
Following these developments, Capstone Copper will operate as a Chile-and-Arizona copper producer with a materially smaller Mexican footprint limited to equity in Luca. This structure results in a less diversified geographic presence, with greater concentration in the Mantoverde-Santo Domingo district and associated Chilean permitting, water, and labour risks. Cashel Meagher serves as President and CEO, and John MacKenzie is Chair; no management ownership or detailed background is disclosed.