Aya Gold & Silver Reports Strong Q3-2026 Results on Record Production and Lower Cash Costs
Aya raised its guidance floor and beat costs, though fourth-quarter implied results remained below the record set in the third quarter.
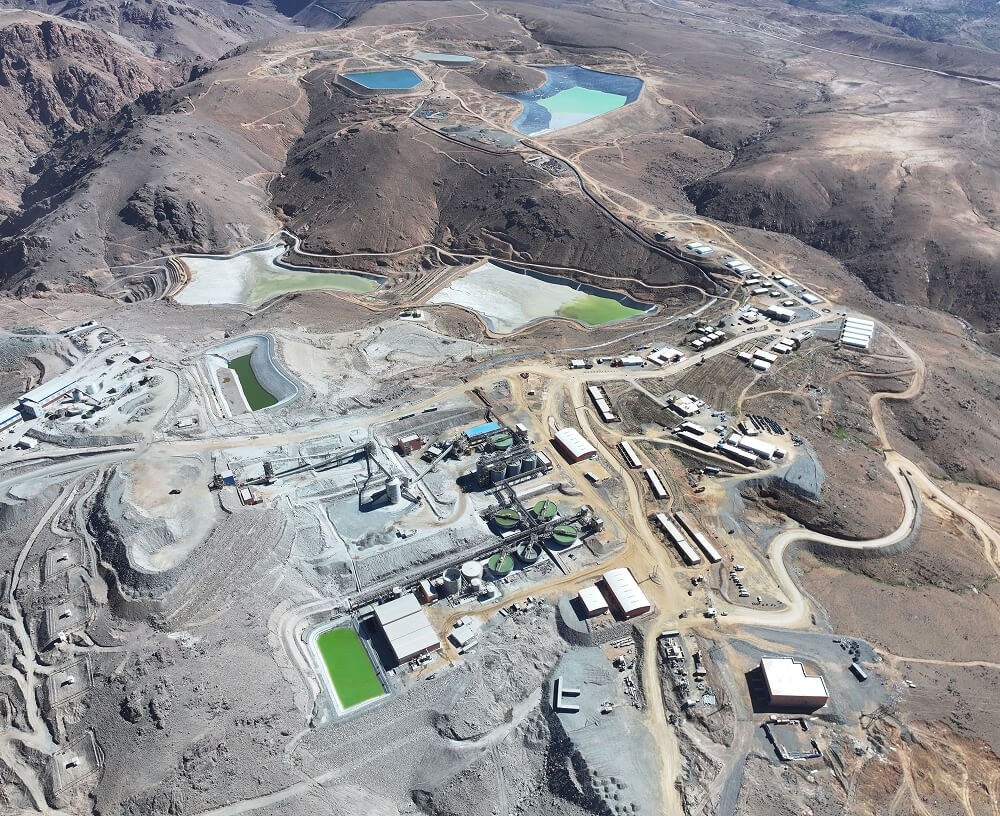
Aya Gold & Silver Inc. (AYA) reported third-quarter 2026 results for the period ended September 30, 2026, highlighting significant growth in revenue and profitability. Consolidated revenue reached $103.287 million, a 90% increase from the $54.337 million reported in the same period last year. Year-to-date revenue stood at $317.355 million, representing a 150% year-over-year rise. Gross profit surged 220% year-over-year to $68.298 million, expanding the gross margin to 66.1% from 39.3% in the prior year period.
Operating income increased 292% to $59.472 million, while net income rose 182% to $35.007 million. Of the net income, $33.5 million was attributable to Aya, with the remainder belonging to the Boumadine minority interest. Basic earnings per share were $0.23, and diluted earnings per share were $0.22. For the year to date, net income totaled $118.572 million, with earnings per share of $0.81. Operating cash flow reached $48.080 million, up 115% year-over-year, or $54 million before working capital changes. Year-to-date operating cash flow was $166.652 million.
The company’s balance sheet remained strong, with cash holdings of $183.791 million and an additional $16 million in restricted cash. Working capital stood at $153.663 million, while non-current financial liabilities decreased 48% year-over-year to $43.585 million.
Consolidated production totaled 2.0346 million ounces of silver equivalent, marking a 51% year-over-year increase and a 21% quarter-over-quarter rise. At the Zgounder mine, production reached 1,497,749 ounces of silver, up 11% year-over-year and 1% quarter-over-quarter. Mill throughput increased 23% year-over-year and 5% quarter-over-year to 4,096 tonnes per day. The feed grade averaged 146 grams per tonne of silver with a 92.0% recovery rate. Mining operations processed 4,746 tonnes per day, and the ore stockpile grew 16% quarter-over-year to 434,538 tonnes. Reported production figures exclude 138,100 ounces of silver cement that remained unsmelted at the end of the quarter.
At Boumadine, pyrite reclaim operations processed 49,890 tonnes of reclaimed and crushed material, a 191% increase quarter-over-year. The material averaged 151 grams per tonne of silver and 2.61 grams per tonne of gold, yielding 244,875 ounces of silver and 4,300 ounces of gold, equivalent to 536,879 ounces of silver equivalent. These materials were sold at a gold-to-silver ratio of 68:1.
Cash costs per ounce sold at Zgounder decreased 16% year-over-year and 1% quarter-over-year to $17.53. Boumadine cash costs per ounce of silver equivalent fell 2% quarter-over-year to $10.42. Consolidated cash costs per ounce of silver equivalent dropped 25% year-over-year and 8% quarter-over-year to $15.51. Realized prices at Zgounder were $69.32 per ounce of silver, up 2% quarter-over-year. Boumadine realized prices were $34.72 per ounce of silver equivalent, down 1% quarter-over-year. Consolidated realized prices were $59.50 per ounce of silver equivalent, up 49% year-over-year but down 7% quarter-over-year.
For the full year 2026, Aya raised its consolidated guidance to 6.6–6.8 million ounces of silver equivalent, up from the previous range of 6.2–6.8 million ounces. Zgounder’s 2026 guidance low end was increased to 5.6–5.8 million ounces of silver from 5.2–5.8 million ounces. The company expects full-year Zgounder cash costs to remain below the $21.50 per ounce guide.
The company’s land package expanded by approximately 50% to over 1,200 square kilometers, including 259 square kilometers in the Anti-Atlas and 139 square kilometers at Tizi Cu-Ag, which closed on October 16, 2026. The Azegour asset is set to be swapped for approximately 19.11% of Sama Resources. At Boumadine, the 2026 infill drilling target of 180,000 meters was exceeded with 181,685 meters drilled. A preliminary economic assessment for Boumadine, referencing a 14-year life, $3.5 billion NPV at a 5% discount rate, 93% internal rate of return, and $463 million in capital expenditure, was also referenced.
The release did not provide all-in sustaining costs, reporting only cash costs per ounce, which exclude sustaining capital, corporate general and administrative expenses, and the $60 million annual exploration program. No strip ratio was disclosed for the quarter, following a Q2 disclosure of 12 against a planned 16. Underground mining rates were not reported, whereas Q2 saw 1,444 tonnes per day. Additionally, no date was provided for the Boumadine feasibility study, though the Q2 transcript indicated a first-half 2027 timeline. The release did not update on promised year-end 2026 Boumadine early works, including access roads, power, water, and camp infrastructure, nor on the commissioning of the Q4-2026 ore sorter. Litigation costs were described only as "higher professional fees" without quantification, despite the Duro Felguera dispute lasting at least three quarters. With 5.2048 million ounces of silver equivalent delivered year-to-date, the 6.6–6.8
Aya Gold & Silver Inc. (AYA) reported third-quarter 2026 financial results on November 12, 2026, highlighting improved cost performance and an upgrade to its full-year production guidance. The company confirmed that its Zgounder operation achieved an all-in sustaining cost of $17.53 per ounce, while the consolidated all-in sustaining cost was $15.51 per ounce. These figures represent an 18% improvement over the originally guided $21.50 run-rate for the quarter and a 16% improvement over the year-to-date figure of $17.97. Management also committed to finishing full-year Zgounder costs below $21.50 per ounce.
In conjunction with the cost improvements, Aya raised its production guidance. The consolidated low-end guidance increased from 6.2 million ounces to 6.6 million ounces, a 6.5% increase. Similarly, the low-end guidance for the Zgounder operation was raised from 5.2 million ounces to 5.6 million ounces, a 7.7% increase. Previously, on October 14, 2026, management had stated the company was "firmly on track" but had not provided specific numerical targets for a potential raise.
The company reported operating income of $48.1 million, a 292% increase, and net income of $35.0 million, a 182% increase. Operating cash flow reached $48.1 million, and the company’s cash position rose to $183.8 million. Working capital stood at $153.7 million against non-current financial liabilities of $43.6 million, resulting in a net cash position estimated at approximately $140 million.
Despite the operational improvements, net income remained flat compared to the $35.0 million reported in the second quarter of 2026, even as revenue increased by 6.5%. This stagnation in earnings was driven by a 7.3% quarter-over-quarter decline in the consolidated realized AgEq price to $59.50 per ounce, down from $64.22 per ounce, alongside higher cost of sales. The year-over-year performance metrics reflect a low base from the third quarter of 2025.
Revenue for the quarter was $103.3 million, which is 11.9% lower than the $117.3 million reported in the first quarter of 2026, when the realized AgEq price was $82.22 per ounce. The company noted that the consolidated realized price fell while the Zgounder realized silver price rose 2% quarter-over-quarter. This divergence is attributed to ore mix; Boumadine AgEq ounces realize $34.72 per ounce compared to $69.32 per ounce at Zgounder. Consequently, the 51% year-over-year production growth overstates economic growth, as the incremental ounces carry roughly half the revenue per ounce.
The guidance arithmetic implies a fourth-quarter production level below the third quarter. Management indicated that open-pit pushbacks are expected to begin "toward the end of 2026," and the Boumadine annual reclaim target of approximately 1.0 million ounces has been effectively achieved, with 1.07 million ounces already accounted for in the guidance ratio. No further reclaim ounces are contemplated in the range. The release did not specify whether this range reflects an expected step-down in production or a conservative set-up for a fourth-quarter beat.
Since the second-quarter 2026 results on August 13, 2026, when the stock closed at C$37.44, Aya’s shares have declined 6.8% to C$34.89. The stock is 18.3% below its high of C$42.68 on September 22, 2026, despite the publication of a $3.5 billion PEA NPV in between. The market has already priced in the Boumadine project and has reduced exposure to the producer. The formal raise in the production floor and the locked-in cost beat differentiate the current performance from previous management commitments.
Aya Gold & Silver Inc. (AYA) is a Canadian precious metals producer listed on the TSX and, since 4-May-2026, on Nasdaq. It is the only primary silver producer of scale in Morocco and is transitioning from a single operating asset to a two-asset platform.
The company’s operating asset is the 100%-owned Zgounder mine, a rare silver-only operation located on the Anti-Atlas fault. The mine produces silver doré from a new processing facility that has run at 4,096 tpd against a 3,650 tpd plan. The open pit and underground operation has ~6 moz/yr planned through 2036, with 73.4 moz P&P reserves at 145 g/t.
Aya also holds an 85% interest in the Boumadine project, with the remaining 15% held by ONYHM. Located in Errachidia province, approximately 220 km east of Ouarzazate, the polymetallic Au-Ag-Zn-Pb-Cu project comprises a 339 km² land package, a 600 km² exploration authorization, and an existing 32 km² mining licence. A 2026 PEA outlines a conventional flotation operation producing zinc, lead, and pyrite concentrates at 8,000 tpd. The project features a $463M initial capex, a 14-year life, and production of 348 koz AuEq/yr in years 1–5 at an AISC of $1,105/oz AuEq. Feasibility is targeted for late 2027, with construction planned for 2028–2029 and production around 2031. The release explicitly states that Boumadine "remains at the exploration and evaluation stage and is not in commercial production."
Additionally, Aya is commercializing a legacy stockpile of approximately 260,000 t of historical flotation pyrite from late-1980s/early-1990s lead-zinc operations. The material grades ~2.3 g/t Au and 144 g/t Ag. This pyrite reclaim program began on 19-Nov-2025 under an offtake agreement with an international buyer and is expected to run for 20–24 months at a rate of ~10,000 t/month. The activity generates cash, remediates acid-generating material ahead of the planned open pit, and establishes concentrate offtake relationships.
The company’s exploration portfolio has expanded from approximately 732 km² to over 1,200 km² in roughly six months. This expansion includes the ~259 km² Anti-Atlas portfolio, covering Zagora, Agadir-Melloul, and Goulmim with Ni-Co-Pb-Zn-Ag-Au, Cu-Ag-Au, REE, and Pb-Ag-Cu-Au targets, as well as the 139 km² Tizi Cu-Ag portfolio located approximately 35 km west of Zgounder, which includes a 19 km² mining licence. Azegour, a Cu-W-Mo project in the Western High Atlas, is being divested to Sama Resources.