Aya Gold & Silver Files Updated Preliminary Economic Assessment Technical Report for Boumadine Project
Aya re-filed the Boumadine preliminary economic assessment without new data, as the project’s net present value had already declined from previous price assumptions.
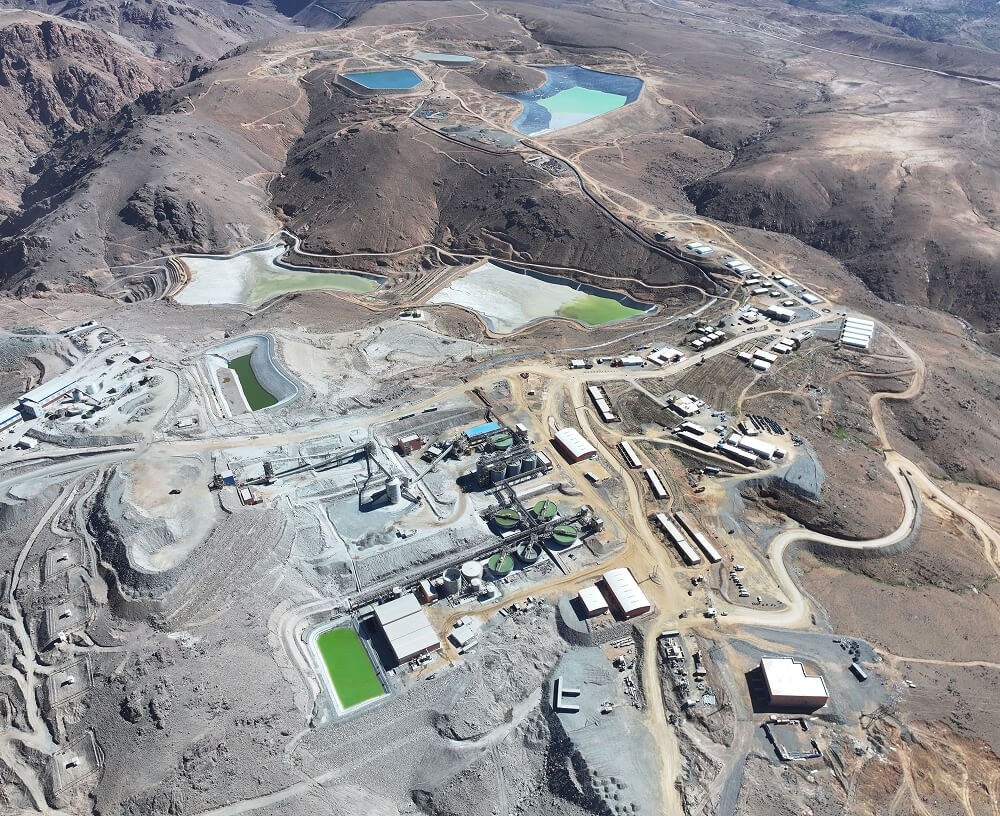
Aya Gold & Silver Inc. (AYA) filed a National Instrument 43-101 technical report for the Boumadine 2026 Preliminary Economic Assessment (PEA) on SEDAR+ and EDGAR on October 20, 2026. The filing, which supersedes the 2025 PEA effective November 4, 2025, carries an effective date of September 9, 2026, with the Mineral Resource Estimate (MRE) within it effective February 28, 2026. The release notes that the results and highlights were previously reported in Aya’s news release dated September 9, 2026.
The re-stated base case economics project an after-tax NPV5% of $3.5 billion, representing more than double the prior PEA, alongside a 93% internal rate of return (IRR) and a 0.7-year payback period. Initial capital expenditure is estimated at $463 million, with a capital efficiency ratio of 7.6x, up from 3.3x. Under a re-stated spot case using prices as of September 3, 2026—disclosed in the sensitivity table as $4,472/oz Au, $66.85/oz Ag, $1.77/lb Zn, and $0.85/lb Pb—the project yields a $5.5 billion NPV5%, a 128% IRR, and a 0.5-year payback.
Production estimates have been re-stated at 348,000 ounces of gold equivalent (AuEq) per year for Years 1–5 and 271,000 AuEq per year for the life of mine (LOM). Total LOM production is 3.9 million AuEq, a 7% increase versus the prior PEA, comprising 2.3 million ounces of gold, 81.2 million ounces of silver, 422,000 tonnes of zinc, and 195,000 tonnes of lead. This represents approximately 16% higher LOM silver production than the prior PEA. The mine plan involves mining 41.2 million tonnes of mineralized material over the LOM, a 33% increase versus the prior PEA, at grades of 4.11 g/t AuEq for Years 1–5 and 3.10 g/t AuEq for the LOM. The mine life has been extended from 11 to 14 years, utilizing an 8,000 tonnes per day flotation plant to produce zinc, lead, and pyrite concentrates.
Costs are re-stated at cash costs of $998/oz AuEq for Years 1–5 and $1,169/oz AuEq for the LOM. All-in sustaining costs (AISC) are estimated at $1,105/oz AuEq for Years 1–5 and $1,300/oz AuEq for the LOM. The re-stated MRE, effective February 28, 2026, includes Indicated resources of 8.6 million tonnes at 4.02 g/t AuEq containing 1.1 million AuEq (a 34% increase) and Inferred resources of 45.4 million tonnes at 2.92 g/t AuEq containing 4.3 million AuEq (a 1% increase).
New details disclosed in the sensitivity table include break-even prices of $1,704/oz Au and $24.34/oz Ag, where the after-tax NPV5% equals zero. In a −25% price case, assuming $2,625/oz Au and $37.50/oz Ag, the project still yields a $1.808 billion NPV5%, a 57% IRR, a 1.3-year payback, and a 3.9x capital efficiency. Other procedural disclosures include metal payability assumptions of 82% for gold and 85% for silver, up 12 and 8 percentage points from the prior PEA, respectively. The report was prepared by Lycopodium (Americas) and CCE Mining, with the MRE by SRK (Mr. Guy Dishaw, P.Geo.). The company states that the existing mining licence is in hand in advance of Feasibility Study completion.
The release contains a caveat that the PEA is preliminary in nature and includes inferred mineral resources considered too speculative geologically to have economic considerations applied to them. The company acknowledges it may make decisions to advance the development of its mineral projects prior to the completion of a feasibility study, which involves materially greater technical and economic risks. Aya Gold & Silver Inc. is scheduled to release Q3-2026 financial results and hold a conference call on November 12, 2026.
Aya Gold & Silver Inc. (AYA) filed a technical report on September 9, 2026, disclosing economic, operational, and resource figures that had already been released. The filing served as a 45-day administrative obligation.
Following the initial Pre-Feasibility Study (PEA) on September 9, the stock did not re-rate despite the headline net present value (NPV) of $3.5 billion. Shares closed at $40.16 on September 8, rose to $41.27 on September 9, and fell to $37.42 by September 14, marking a 9.3% decline in three sessions. From a high of $42.68 on September 22, the stock dropped 13.5% to $36.91.
The market’s skepticism appears rooted in the price assumptions used in the new base case. The prior PEA utilized $2,800/oz Au and $30/oz Ag, while the new base case uses $3,500/oz Au (+25%) and $50/oz Ag (+67%). These assumptions are close to spot prices of $4,472/oz Au and $66.85/oz Ag as of September 3, 2026, meaning the base case is no longer considered conservative.
Genuine improvements independent of price include metal payability of 82% Au and 85% Ag, up 12 and 8 percentage points respectively. Long-of-mine (LOM) silver production is up approximately 16%, mine life has increased from 11 to 14 years, and total tonnes mined rose 33% to 41.2 Mt. Under a −25% sensitivity case with gold at $2,625/oz and silver at $37.50/oz—below the prior PEA’s gold base case—the project returns a $1.8 billion NPV and 57% internal rate of return (IRR), compared to the prior PEA’s $1.5 billion at $2,800/oz.
The filing does not address capex-overrun sensitivity, opex-inflation sensitivity, or sensitivity at a discount rate above 5%. The project, a greenfield in Morocco with commercial production targeted for 2031, is discounted at only 5%, resulting in a 0.7-year payback period.
Aya Gold & Silver Inc. (AYA) is a Canadian precious metals company anchored in Morocco, dual-listed on the TSX and, since May 4, 2026, on Nasdaq. The company was added to the VanEck Gold Miners ETF (GDX) on June 16, 2026.
Its primary asset is the Zgounder mine, a 100%-owned operation located on the Anti-Atlas Fault. Zgounder is a rare primary silver mine producing silver doré from a new processing facility, utilizing both open-pit and underground methods. In Q3-2026, throughput reached 4,096 tpd against a 2,700 tpd nameplate capacity. An updated life-of-mine plan extends to 2036, projecting approximately 6 moz Ag per year at $16.26/oz cash cost and $71M in sustaining capital. The project holds P&P reserves of 73.4 moz Ag at 145 g/t and M&I resources of 100.2 moz Ag at 165 g/t.
The Boumadine project, in which Aya holds an 85% interest and ONHYM holds 15%, is currently at the PEA stage. This polymetallic project derives roughly 60% of its value from gold and 30% from silver, with lead, zinc, and pyrite concentrates. The company holds a 32 km² mining licence, a 339 km² land package, and a 600 km² exploration authorization. The 2026 PEA describes a district-scale open-pit and underground operation at 8,000 tpd with a 14-year life. Separately, a historical pyrite stockpile is being reclaimed and shipped under an offtake agreement, a finite 20–24 month operation that started in November 2025.
The exploration portfolio includes Zagora (158.6 km², Ni-Co-Pb-Zn-Ag-Au), Agadir-Melloul (68.5 km², Cu-Ag-Au and REE), Goulmim (32.0 km², Pb-Ag-Cu-Au), plus Imiter Bis, Amizmiz, Azegour, Asirem, Touda and Elios. The Moroccan land package expanded from approximately 732 km² to over 991 km² during 2026, a 35.4% increase.
Per the investor presentation, the development timeline for Boumadine includes 2026 early works; H2-2027 Feasibility Study and ESIA; 2028 definition drilling and FEED; 2029 process plant construction; 2030 commissioning and ramp-up; and 2031 commercial production, marking a five-year path to first revenue. Infrastructure requirements include a 72 km powerline and substation with the national grid operator, process water primarily from treated municipal wastewater plus a brackish water program, and tailings storage of approximately 24 Mt, fully lined and phased to GISTM standards. Logistics involve roughly 640 km of road haulage to Nador-West port, with rail refurbishment under discussion. Each of these is a live permitting, cost and schedule risk, not a solved problem.
Management includes Benoit La Salle (President & CEO), founder of SEMAFO; Mustapha Elouafi (President, Morocco), formerly of OCP S.A.; Ugo Landry-Tolszczuk (CFO); Raphaël Beaudoin (EVP Operations) and David Lalonde (EVP Exploration), both NI 43-101 Qualified Persons. The board is chaired by Ghislane Guedira.