With Long-Term Uranium at US$98, Wyoming's In-Situ Basins Draw a New Acquirer
Sector M&A validates uranium thesis, but Anfield's near-term catalysts remain execution-dependent.
Eagle Nuclear Energy Corp. (NASDAQ: NUCL) has signed a binding letter of intent to acquire 100% of Noble Plains Uranium Corp. in an all-stock transaction. The deal values Noble Plains at a deemed price of CAD $0.125 per share, representing a ~92% premium to its October 29 closing price. The transaction adds ISR potential and scale to Eagle's portfolio, specifically the Duck Creek and Shirley Central projects in Wyoming.
The release highlights rising uranium prices, with the Cameco long-term indicator at US$98.00/lb, and provides peer updates on Cameco, enCore Energy, Anfield Energy, and Peninsula Energy. This news is a sector-wide M&A event and does not directly involve Anfield Energy's assets, management, or capital structure.
The acquisition of Noble Plains by Eagle Nuclear serves as a strong sector-wide validation of the current uranium market fundamentals and the strategic value of U.S. ISR and brownfield assets. For Anfield Energy Inc. (AEC), this M&A activity reinforces the macro tailwinds supporting the company's hub-and-spoke model and brownfield development strategy, establishing a valuation benchmark for comparable U.S. uranium assets and increasing the likelihood of strategic interest or consolidation in the sector.
The news does not alter Anfield's immediate operational roadmap, capital requirements, or project timelines. Instead, it functions as a positive sentiment catalyst rather than a direct operational or financial inflection point for the company.
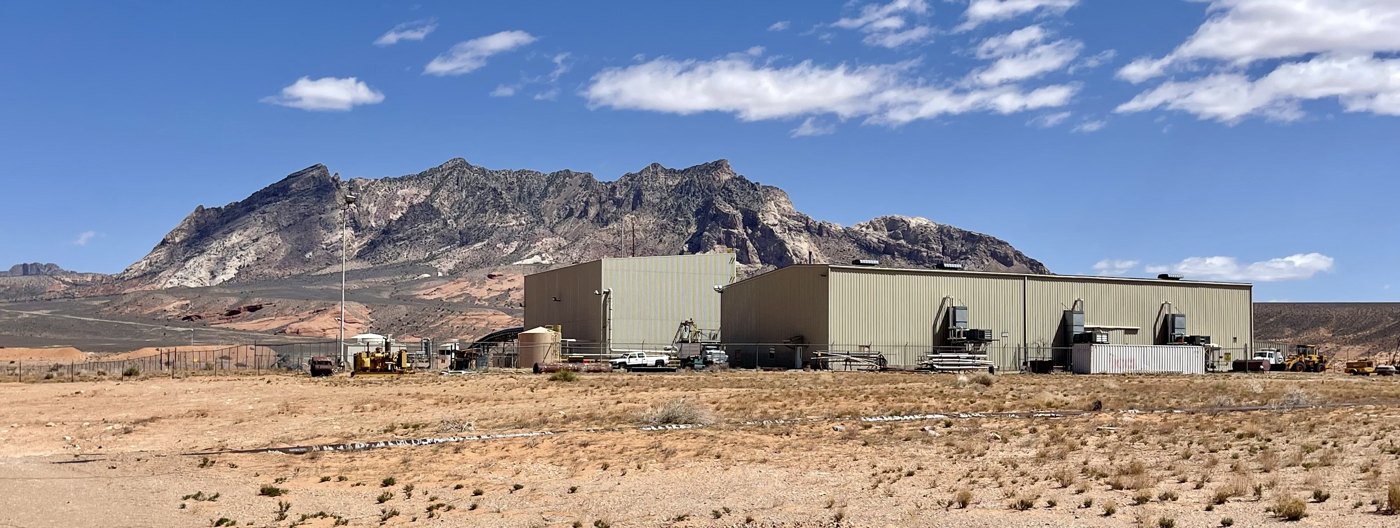
Anfield Energy Inc. (AEC) operates a hub-and-spoke uranium and vanadium production strategy centered on the fully permitted Shootaring Canyon Mill in Utah. The mill is one of only three licensed, permitted, and constructed conventional uranium mills in the U.S., with a target capacity upgrade to 1,000 tons per day and an annual production capacity of 3 million pounds of U3O8.
The company’s "spoke" portfolio includes the Velvet-Wood mine in Utah, as well as the Slick Rock, JD-8, JD-7, and SM-18 projects in Colorado. These assets leverage historical infrastructure and brownfield development to minimize greenfield risk. An updated Preliminary Economic Assessment (PEA) highlights robust project economics, including a 106% pre-tax IRR, $606 million USD NPV, and a 1.3-year payback period, based on $100/lb uranium and $9/lb vanadium assumptions. The company targets an average annual production of ~1.3 million pounds of U3O8 and 6.4 million pounds of V2O5 over a 15-year mine life.