Selkirk Copper Announces Positive PEA for the Minto Project, Delivering After-Tax NPV of C$494M with 48% IRR
Selkirk’s preliminary economic assessment delivers a C$494 million net present value at planning prices for its project.
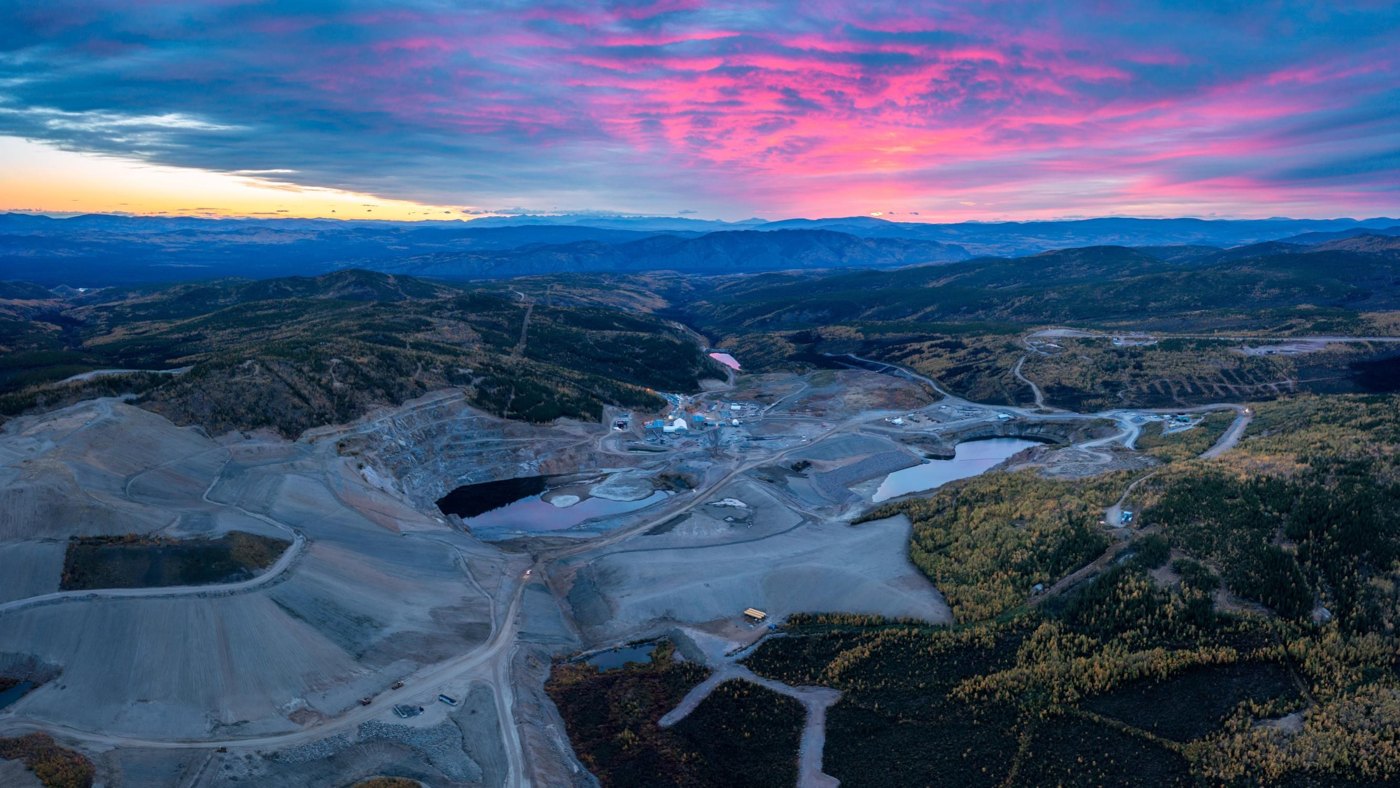
Selkirk Copper Mines Inc. (SCMI) has released the Preliminary Economic Assessment (PEA) for the restart of its 100%-owned Minto copper-gold-silver project in Yukon. This marks the first economic study published regarding the restart and represents a significant disclosure for the company.
The PEA, based on planning prices of US$5.00/lb Cu, US$3,600/oz Au, and US$50/oz Ag, outlines the following headline economics:
- After-tax NPV7%: C$493.9M; pre-tax NPV7% C$742.6M
- After-tax IRR: 47.8% (pre-tax 54.8%)
- After-tax payback from first production: 1.9 years
- Initial capital cost (incl. contingency and working capital): C$185.9M
- Sustaining capital (incl. scoping-level closure/reclamation): C$409.3M
- LOM operating cost: C$1,764M total; C$95.77/t milled
- Copper C1 net of by-product credits: US$1.53/lb; CuEq cash cost US$2.63/lb
- Capital efficiency ratio (after-tax NPV / initial capex): 2.7:1
Sensitivity analysis highlights the project's exposure to commodity prices and foreign exchange. The company states the restart economics are most sensitive, in descending order, to copper price, CAD:USD FX, copper recovery, gold price, and operating costs. The sensitivity table is as follows:
- Downside (US$3.50/lb Cu, US$2,500/oz Au, US$35/oz Ag): after-tax NPV7% C$10M; IRR 9%; payback 6.5 years
- Planning: NPV C$494M; IRR 48%; payback 1.9 years
- Spot (US$6.50/lb Cu, US$4,300/oz Au, US$65/oz Ag): NPV C$1,023M; IRR 78.2%; payback 1.3 years
- Upside (US$7.50/lb Cu, US$5,400/oz Au, US$75/oz Ag): NPV C$1,385M; IRR 96.3%; payback 1.0 year
The study notes a wide asymmetry in outcomes, with the project becoming essentially NPV-neutral at downside copper prices.
The PEA models a 13-year initial mine life at 4,100 tpd (1.5 Mtpa). Peak production is estimated at 27,200 tpa CuEq contained in concentrate, or 48,700 tpa of concentrate at a target 38% Cu, 12-18 g/t Au, and 100-150 g/t Ag. Total LOM mill feed is modeled at 18.4 Mt grading 1.07% Cu, 0.46 g/t Au, and 4.00 g/t Ag (CuEq 1.61%), with an open pit strip ratio of 7.9:1 and an oxide ratio of 7.5%.
Modelled recoveries are 88.7% for copper, 84.6% for gold, and 77.3% for silver. The contained metal in mill feed totals 434 Mlbs Cu, 271 koz Au, and 2.36 moz Ag (653 Mlbs CuEq), with payable metal estimated at 377 Mlbs Cu, 225 koz Au, and 1.39 moz Ag (552 Mlbs CuEq).
Mining operations will begin underground using longhole open stoping with rib pillars, targeting Copper Keel (5.66 Mt), Minto East (2.82 Mt), Minto North (2.17 Mt), and Area 118 UG (1.70 Mt). This will be followed by open pit mining at Ridgetop (5.63 Mt) and Area 118 OP (0.39 Mt). Surface and underground work will be confined to the existing Quartz Mining Licence (QML) boundary.
Tailings management involves in-pit slurry deposition for Years 1-3 behind a new Area 2 dam, transitioning to a new dry-stack facility after Year 3, which is included in sustaining capital for Years 2-3. Permitting amendments are scheduled for submission to the Yukon Environmental and Socio-economic Board (YESAB) in Q4 2026, with the company stating it does not expect notable changes to water discharge criteria.
The timeline models a capex period from 1 July 2027 to 30 June 2028. A restart decision and receipt of permit amendments are targeted for H2 2027, with first concentrate production in H2 2028 and full ramp-up in H1 2029.
Phase 2 drilling, totaling 50,000 meters, is 98% complete but is not included in the PEA or the 2026 Mineral Resource Estimate (MRE). Results from this drilling will feed an updated MRE in Q1 2027 and a subsequent Feasibility Study. The PEA is preliminary, includes Inferred Mineral Resources, and does not constitute a Mineral Reserve.
Technical work was led by Hatch, with contributions from SRK, Fuse Advisors (SLR), Moose Mountain Technical Services, and Ensero. News release scientific and technical content was supervised by Scott Fulton, P.Eng., VP Engineering, a non-independent Qualified Person.
Pre-capex items, including dewatering, physical rehabilitation, re-servicing of existing underground infrastructure, ongoing water treatment, deposits on fixed and mobile equipment, and refurbishment of two backup diesel generators, are explicitly excluded from the C$185.9M initial capital cost and treated as sunk costs. The project includes a 1.5% Net Smelter Return (NSR) payable to Selkirk First Nation on all payable metals.
Selkirk Copper Mines Inc. (SCMI) has released its first economic study for the Minto restart, providing initial disclosures on net present value (NPV), internal rate of return (IRR), capital expenditures (capex), operating expenses (opex), recoveries, and the mine plan. The headline NPV is C$494 million at Planning Prices and C$1,023 million at Spot prices, figures that represent approximately 1.8x to 3.8x the company’s current market capitalization.
The Preliminary Economic Assessment (PEA) was released on September 22, 2026, following a series of management guidance updates that pushed the timeline from an initial "mid-2026" target through "Q3 2026." The study outlines a 13-year mine life, which sits within the previously guided range of 12 to 15 years. The planned throughput is 4,100 tonnes per day (tpd), consistent with prior guidance. However, peak production is modeled at 27,200 tonnes per annum (tpa) of copper equivalent (CuEq), falling below the approximately 30,000 tpa CuEq production target stated in the company’s investor deck. First concentrate production is targeted for the second half of 2028, aligning with previous "2028" guidance.
The restart decision timeline has slipped from an original target of early 2027, to mid-2027, and is now contingent on the completion of a Feasibility Study and receipt of a permit amendment in the second half of 2027. Consequently, the start of the Feasibility Study has moved from the third quarter of 2026 to the fourth quarter of 2026.
The 2026 Measured and Indicated (M&I) resource is reported at 47.8 million tonnes (Mt) at 0.89% copper, compared to 12.6 Mt of Indicated material at 1.203% copper in the April 2025 estimate. While tonnage increased by 280% and contained copper rose by 182%, the average M&I copper grade fell by approximately 26%. Of the 47.8 Mt M&I resource, only 18.4 Mt, or approximately 38%, converts into PEA mineable inventory. Similarly, only 434 million pounds (Mlbs) of the 940 Mlbs M&I copper, or approximately 46%, is included in the life-of-mine (LOM) mill feed. The mine plan also incorporates Inferred material, which cannot be classified as reserves.
The study reports an initial capex of C$186 million, excluding pre-capex items such as underground dewatering, rehabilitation, water treatment, equipment deposits, and generator refurbishment, which are deemed sunk costs. Total capital expenditure, including C$409 million of sustaining spend, is approximately C$595 million. This stands against a company balance sheet showing C$17.6 million in cash as of March 31, 2026, with no current revenue.
Copper recovery is assumed at 88.7% in the PEA, compared to a maximum of 98% allowed by the Mineral Resource Estimate (MRE) recovery formula. Management applied historic recovery assumptions rather than improved recoveries indicated by Blue Coast metallurgical testwork. Ridgetop’s oxide ratio of 13% in the pit inventory is noted as a constraint on copper recovery and concentrate moisture. The economic model utilizes an elevated price deck, assuming US$6.50/lb for copper, US$4,300/oz for gold, and US$65/oz for silver. The copper price assumption is described as roughly 50% higher year-on-year. The PEA also assumes negative treatment charges of -US$186/t and -US$0.186/lb at Spot/Upside prices; a reversal to normal positive treatment charges and refinery charges (TC/RCs) would reduce the calculated NPVs.
The study is classified as a PEA on an Inferred-containing resource base with no Mineral Reserve and no demonstrated economic viability. The modelled capex period begins July 1, 2027, while the restart decision and permit amendment receipt are targeted for the second half of 2027. This sequence requires the go/no-go decision and permit receipt to land at or after the start of the spending window, with the schedule dependent on YESAB timelines outside the company’s control.
Following the release of the MRE, Phase 2 hits, port study, and financing news, Selkirk Copper Mines Inc. shares declined from a high of C$2.10 on May 13, 2026, to C$1.58 on September 16, 2026, a drop of 25%. The stock closed at C$1.72 the day before the PEA release.
Selkirk Copper Mines Inc., formerly Venerable Ventures Ltd., has completed a reverse takeover and three-cornered amalgamation to acquire 100% of the former Minto copper-gold-silver mine from Selkirk First Nation affiliates. The transaction closed on 29 October 2025, with trading resuming on the TSXV under the ticker SCMI on 4 November 2025. The company also began trading on the OTCQB under the ticker SKRKF on 13 February 2026, with DTC eligibility, and is listed on the Frankfurt exchange under IO20. The legal name change from Venerable Ventures was delayed due to a BC Registries job action.
The company’s flagship asset is the Minto Project, a past-producing mine located in central Yukon, approximately 250 km north of Whitehorse on the Klondike Highway within the Minto-Carmacks copper belt. Selkirk Copper Mines controls 26,850 hectares of mineral claims. The deposit is characterized by structurally controlled, migmatised chalcopyrite-bornite-(magnetite) bearing schist, representing a strongly metamorphosed calc-alkaline porphyry- or IOCG-like system. Mineralisation occurs in multiple shallow-dipping lenses, with 69 mineralised lenses identified across the central mine area.
Existing infrastructure at the site includes a 4,100 tpd process plant featuring a SAG mill, two ball mills, flotation cells, concentrate thickening and filtration, and an assay lab. The site also houses a 400-person camp, water treatment plant, main power line and substation, fuel farm, maintenance shops, warehouse, airstrip, concentrate storage shed, and extensive underground development. The company values the reusable infrastructure at over C$330M, and a preliminary economic assessment (PEA) confirms that negligible capital is required for most of it. Mining operations ceased as recently as May 2023.
Historic production from 2007 to 2023 ranged from 70,000 to 1,969,000 tonnes of open-pit ore and 20,000 to 1,480,000 tonnes of underground ore annually, with copper recoveries between 82% and 97%. The current development stage focuses on a restart evaluation. Metallurgical processing targets a single copper-gold-silver concentrate with specifications of 36-40% Cu, 12-18 g/t Au, and 100-150 g/t Ag, featuring low deleterious elements to position the product as premium quality.
Logistics involve a 27 km site access road leading to the Yukon River, where crossing is achieved by barge or ice bridge, subject to seasonal constraints. From there, material travels 425 km on the Klondike Highway to the Port of Skagway, Alaska, for tidewater shipment. An 18,000 tonne on-site concentrate shed is available to cover periods when the river cannot be crossed.
The project operates under a commercial and operating partnership with the Selkirk First Nation, which serves as both the largest equity holder and the royalty holder. An Indigenous engagement function has been staffed to support this relationship. The social licence is supported by a pro-mining Yukon Party majority government, elected in November 2025.
Qualified persons responsible for the technical reports include Sue Bird, P.Eng. (MMTS), for the 2026 mineral resource estimate; Leif Bailey, P.Geo., Director of Geoscience & Exploration, for the 14 September 2026 NI 43-101 filing; and Scott Fulton, P.Eng., VP Engineering, for the PEA news release. Bailey and Fulton are noted as non-independent.