Selkirk Copper Drills 9.3% Cu, 7.4 g/t Au and 54.9 g/t Ag (15.1% CuEq) over 5.4 Metres at Minto North as Part of the Ongoing Phase 2 Drill Program
Selkirk’s infill drilling at the Selkirk deposit revealed a high-grade 99th-percentile hole, confirming robust mineralisation without changing total tonnes.
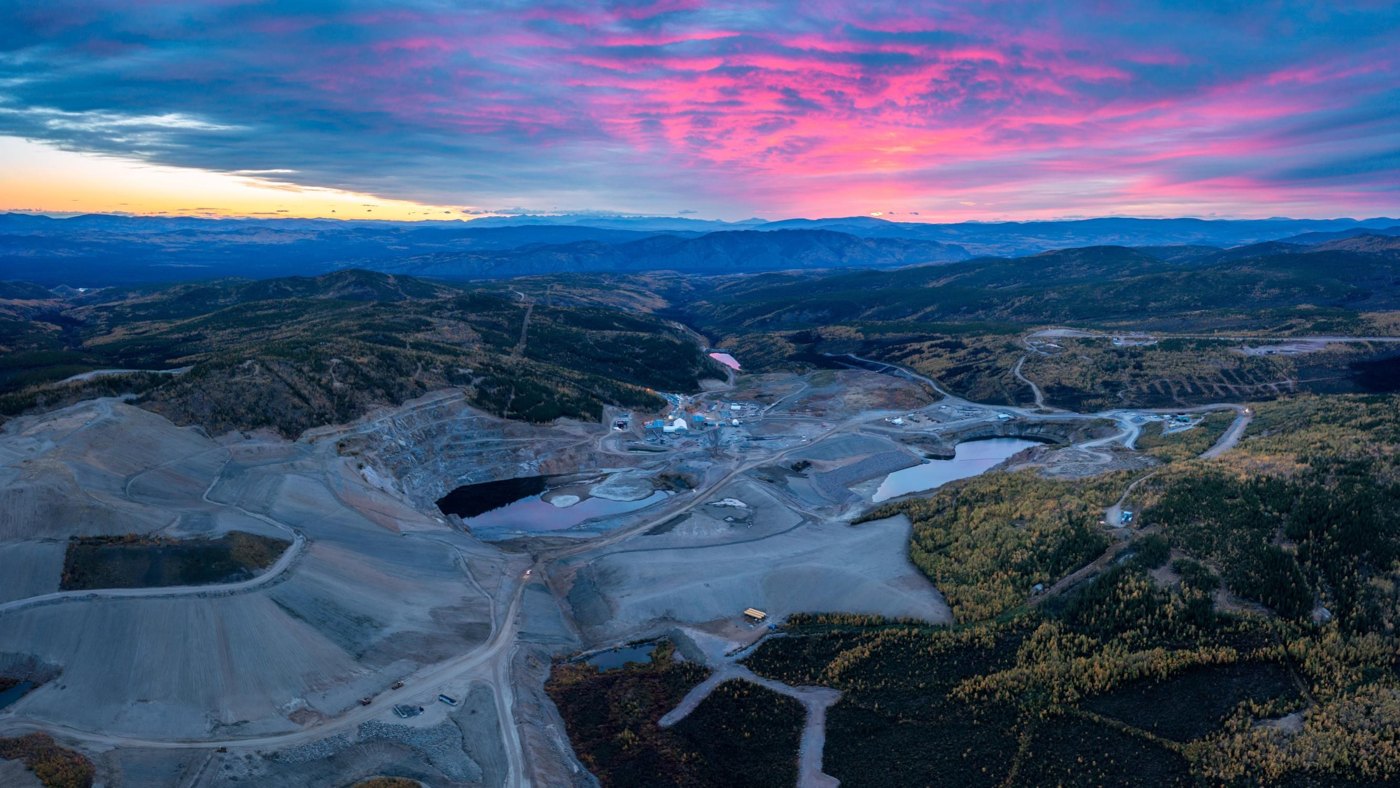
Selkirk Copper Mines Inc. (SCMI) released assay results from 26 holes drilled in June 2026 as part of the Phase 2 program at its Minto copper-gold-silver project in the Yukon. As of September 28, 2026, Phase 2 stands at 52,485 meters across 224 holes, representing 105% of the 50,000-meter plan. Only 53 of the 224 holes have reported assays to date, broken down by area as follows: Minto North (14 of 35), Minto East (3 of 14), Minto Main (10 of 37), Area 118 (9 of 46), Copper Keel (17 of 47), and Ridgetop (0 of 45).
Key intercepts reported in Table 3 include:
- 26SCM209 (Minto North, expansion, 35 m step-out south of the 202 Lens): 9.27% Cu, 7.43 g/t Au, 54.9 g/t Ag (15.11% CuEq) over 5.4 m from 218.6 m; within 6.62% Cu, 5.09 g/t Au, 38.7 g/t Ag (10.61% CuEq) over 8.1 m from 215.9 m; plus a separate 0.97% Cu, 2.58 g/t Au, 8.4 g/t Ag (3.11% CuEq) over 9.0 m from 170.0 m.
- 26SCM224 (Minto North, expansion, 35 m step-out northwest): 1.00% Cu, 0.37 g/t Au, 3.9 g/t Ag (1.25% CuEq) over 17.6 m from 182.0 m, including 1.59% Cu, 0.61 g/t Au (1.99% CuEq) over 5.7 m.
- 26SCM198 (Area 118, infill, 114 Lens): 1.53% Cu, 0.58 g/t Au, 7.6 g/t Ag (1.94% CuEq) over 9.1 m from 239.6 m.
- 26SCM207 (Area 118, infill): 0.83% Cu (1.02% CuEq) over 33.3 m from 238.0 m, including 1.61% Cu, 0.59 g/t Au (2.03% CuEq) over 6.9 m.
- 26SCM216 (Area 118, infill): 1.07% Cu (1.43% CuEq) over 14.8 m, including 2.54% Cu, 1.25 g/t Au (3.45% CuEq) over 3.0 m.
- 26SCM235 (Minto Main, infill, 114/117 Lens): 1.15% Cu, 0.43 g/t Au (1.42% CuEq) over 9.7 m; 0.83% Cu (0.94% CuEq) over 32.1 m; 0.71% Cu (0.79% CuEq) over 8.7 m.
- 26SCM213 (Minto North, infill): 1.19% Cu (1.39% CuEq) over 16.1 m, including 5.20% Cu, 1.32 g/t Au (6.07% CuEq) over 2.8 m. 26SCM231 (infill): 1.02% Cu (1.51% CuEq) over 20.6 m.
- Copper Keel: 26SCM234 2.00% Cu, 0.54 g/t Au (2.29% CuEq) over 5.0 m, plus 0.56% Cu (0.65% CuEq) over 20.6 m; 26SCM238 0.82% Cu (0.94% CuEq) over 18.0 m, including 1.30% Cu (1.49% CuEq) over 7.0 m.
- Four reported holes returned no significant intercept (26SCM201, 26SCM206, 26SCM210, 26SCM230).
The release also provided a drilling-milestone update, noting 365 holes totaling 98,467 meters drilled in one year at a cost of approximately C$45 million, involving roughly 200,000 person-hours. The company cited its standing June 10, 2026 Mineral Resource Estimate (MRE), which includes 47.8 million tonnes of Measured and Indicated resources grading 0.89% Cu, 0.34 g/t Au, and 3.2 g/t Ag, alongside 16.9 million tonnes of Inferred resources grading 0.76% Cu. A regional exploration update mentioned SQUID QMAGT/QAMT surveys with results pending, and an investor webinar is scheduled for October 2, 2026.
Selkirk Copper Mines Inc. (SCMI) is a development-stage company with a completed Preliminary Economic Assessment (PEA) outlining a 13-year mine life, C$186 million in initial capital expenditure, and a C$494 million after-tax net present value at 7% based on C$5.00/lb copper planning, or C$1.023 billion at spot prices. The project features internal rates of return of 47.8% and 78.2%, a 47.8 million-tonne measured and indicated resource, a 16.9 million-tonne inferred resource, and a targeted restart in the second half of 2028.
The recent release does not alter the resource or the PEA, as Phase 2 results are explicitly excluded from both and will instead feed the Q1 2027 mineral resource estimate and feasibility study. The 202 Lens is an existing priority resource area that already saw its Indicated contained copper grow by 238% in the 2026 mineral resource estimate. The reported holes consist of five infill and two expansion holes. The new information indicates that the 202 Lens extends at least 35 meters south and 35 meters northwest, both with pending follow-up. Additionally, a credible structural hypothesis regarding NNW fold-hinge control on high grade across Minto North, Minto Main, Area 118, and Copper Keel has been identified as a targeting tool rather than a tonnage indicator. Net of the two soft spots in Minto Main and Copper Keel, the release is roughly a wash on confidence and positive on grade in one location.
The best previously reported intercepts on Minto North include 25SCM043 at approximately 105 %CuEq·m in April 2026 and 25SCM052 at approximately 91 %CuEq·m in April 2026. The most recent headline at Minto North was 26SCM190, which returned 13.12% CuEq over 1.93 meters on August 20, 2026. The stock has risen approximately 130% from its C$0.59 resumption on November 4, 2025, peaking at C$2.10 on May 13, 2026, which represents a 256% increase from resumption. The stock has since round-tripped approximately 35% from its high, falling from C$1.72 on September 21 to C$1.34 on September 23 following the PEA.
The new intercepts show better grade over a shorter interval. The grade is the highest ever recorded over more than five meters, while the width is 5.4 meters compared to 16.7 meters in prior bests. The product of grade and width is roughly in line to slightly below the prior best. The price remains above its resumption level but well off its high, having been de-rated by the PEA. The result is not materially better in grade-and-width substance than anything previously demonstrated, being better on one axis and worse on the other within an existing resource.
Selkirk Copper Mines Inc. (TSXV: SCMI; FSE: IO20; OTCQX: SKRKF) is a development-stage company that acquired 100% of the idled Minto copper-gold-silver mine in central Yukon from Selkirk First Nation affiliates via a three-cornered amalgamation. The transaction was funded with approximately C$44.5M in subscription receipts and shares, with trading resuming on November 4, 2025. The Selkirk First Nation holds a controlling equity stake of approximately 18% on a non-diluted basis, according to May 2026 filings, and holds two board seats.
The company holds 26,850 hectares of mineral claims in the Minto-Carmacks copper belt, along with substantial inherited infrastructure. This includes a 4,100 tonnes-per-day processing plant, a 400-person full-rotation camp, water treatment facilities, an 8.5 MW grid connection plus on-site generation, a 27 km all-weather road to Minto Landing, and existing open pit and underground workings valued at C$330 million or more. Concentrate is intended to ship seasonally via the Port of Skagway, Alaska. A scoping study with KPFF, funded up to US$200,000, was due in September 2026.
Effective June 10, 2026, the company reported 47.8 million tonnes of Measured and Indicated resources grading 0.89% copper, 0.34 grams per tonne gold, and 3.2 grams per tonne silver, containing 940 million pounds of copper, 530,000 ounces of gold, and 4.97 million ounces of silver. Additionally, there are 16.9 million tonnes of Inferred resources grading 0.76% copper, containing 281 million pounds of copper. This represents a 280% increase in Measured and Indicated tonnage over the 2025 estimate.
The completed Preliminary Economic Assessment defines a 13-year mine life at 4,100 tonnes per day. The project requires C$186 million in initial capital expenditure and C$409 million in sustaining capital. Net of by-products, the C1 cash cost is US$1.53 per pound. At planning prices of $5.00 per pound for copper, $3,600 per ounce for gold, and $50 per ounce for silver, the after-tax NPV7% is C$494 million with a 47.8% internal rate of return. At spot prices, the after-tax NPV7% rises to C$1.023 billion with a 78.2% internal rate of return, with a payback period of 1.3 to 1.9 years. The PEA and the mineral resource estimate use different price decks.
Restart is targeted for the second half of 2028, with full ramp-up in the first half of 2029. The restart decision follows a Feasibility Study and permit amendment in the second half of 2027. Amended permit applications and the commencement of the Feasibility Study are targeted for the fourth quarter of 2026, with an updated mineral resource estimate incorporating Phase 2 targeted for the first quarter of 2027.
According to SEDAR filings, Selkirk Copper Mines Inc. reported a net loss of C$26.0 million for the fiscal year ending March 31, 2026, of which C$22.0 million was exploration and evaluation expenditure. The company recorded an operating cash outflow of C$22.2 million and a financing inflow of C$42.1 million. At year-end, the company held C$17.6 million in cash and C$11.1 million in working capital, with C$396,690 in capital expenditures. There was no revenue and no debt. Book value per share was C$0.16 at the end of FY2026, compared to C$0.24 in the third quarter. There were 128.3 million shares outstanding as of March 31, 2026, versus approximately 158.6 million basic shares per the company's presentation summary following the April 30 bought deal and the Selkirk First Nation participation right, with fully diluted shares totaling approximately 171.2 million.