Koryx Copper Completes PFS Drill Program, Announces Further Positive Infill Drill Results at the Haib Copper Project in Southern Namibia
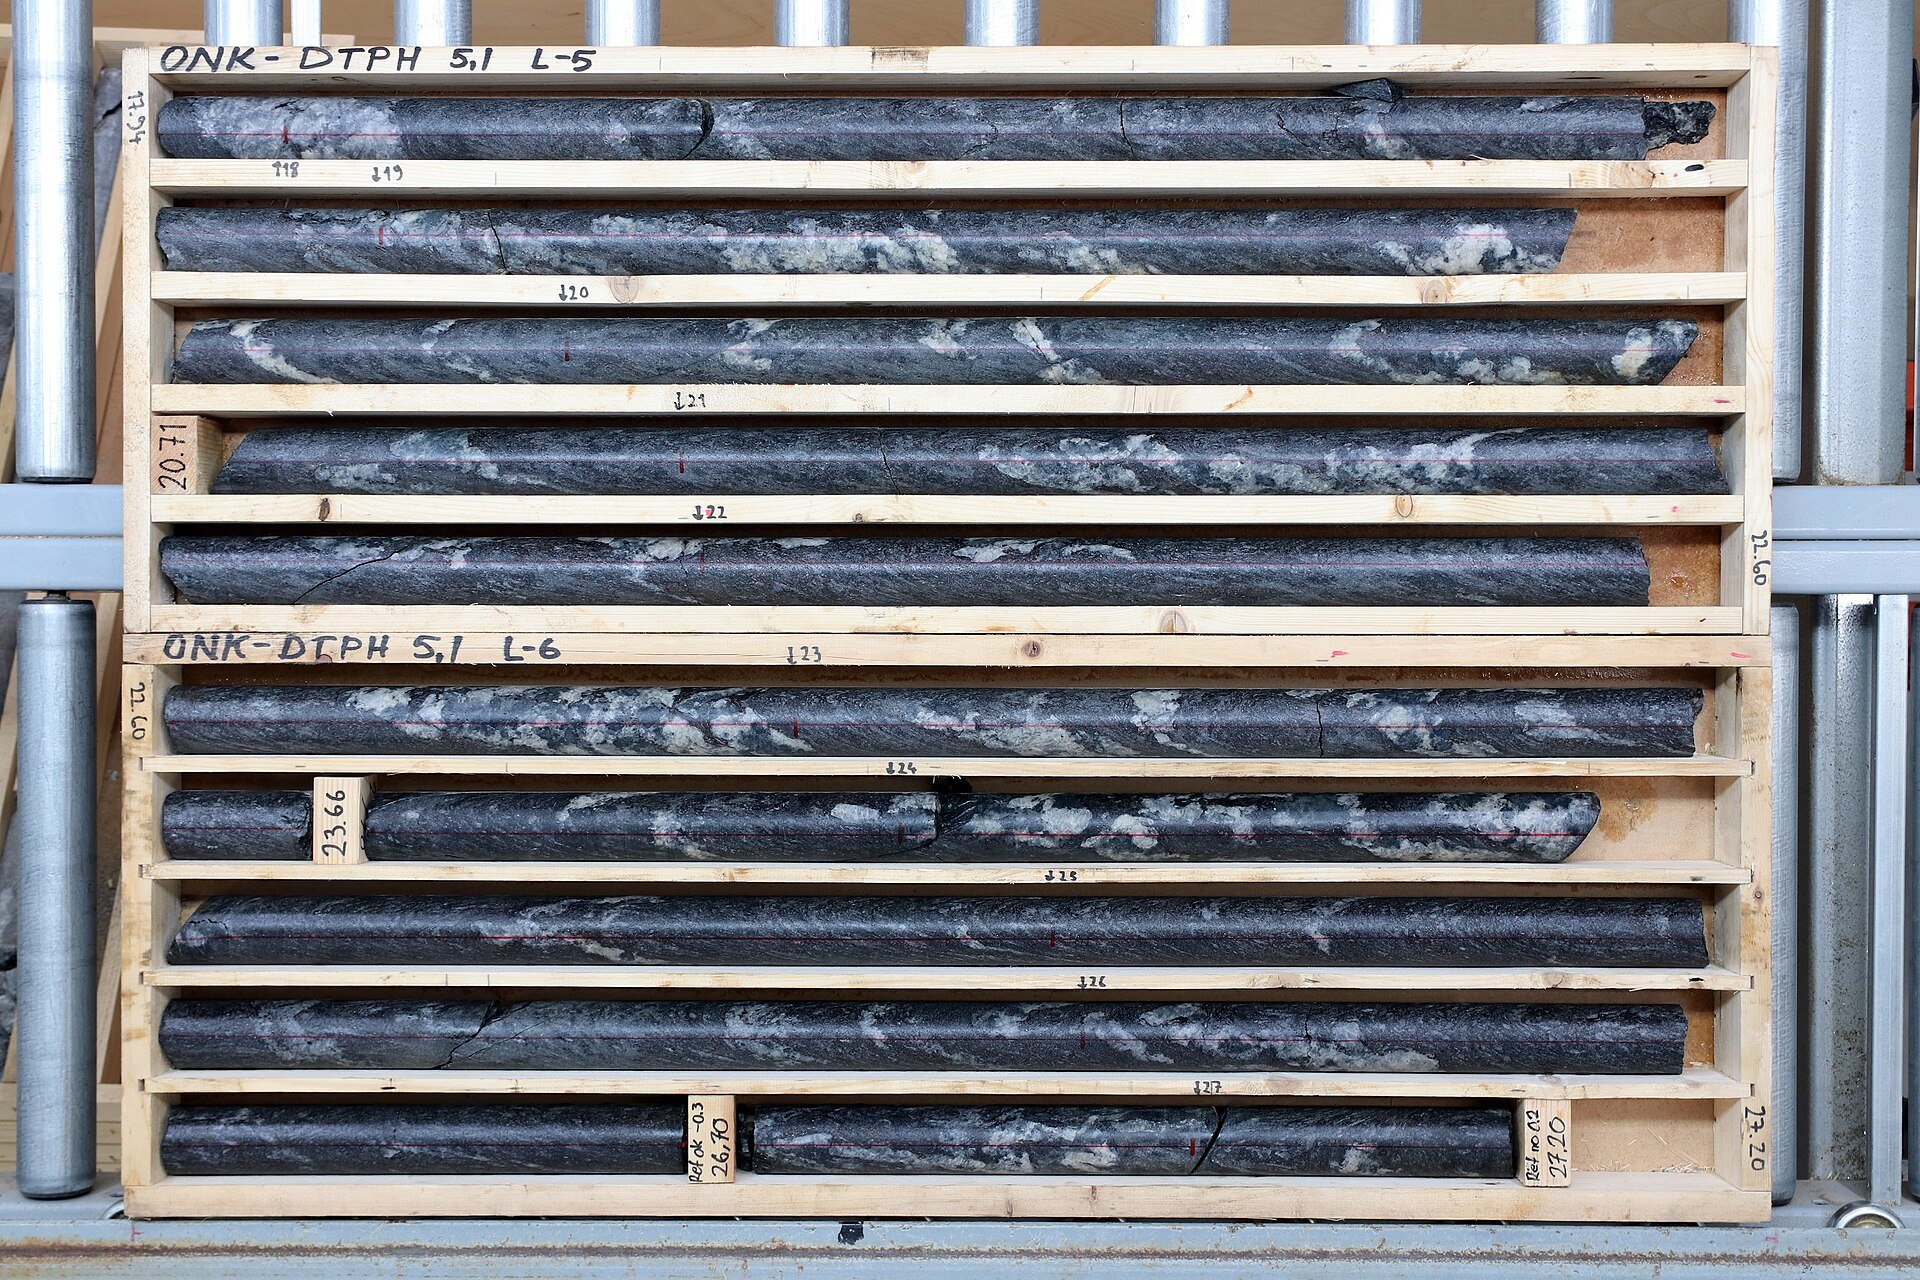
Koryx Copper S.A. (KRY) has completed its pre-feasibility study (PFS) infill and expansion drill program at its 100%-owned Haib Copper Project in southern Namibia. The company reported assay results from 18 drill holes totaling 7,074 meters of drilling.
The best eight of the 18 holes, reported as copper-equivalent (CuEq) intervals with a standard width rather than true width, are as follows:
- HMRC015: 491m @ 0.22% CuEq (33ppm Mo, 0.016g/t Au) from 0m; including 79m @ 0.46% CuEq (412-491m) and 352m @ 0.34% CuEq (38-390m).
- HM199: 438m @ 0.40% CuEq (52ppm Mo, 0.026g/t Au) from 0m; including 16m @ 0.77% CuEq (4-20m) and 224m @ 0.51% CuEq (96-320m).
- HM193: 681m @ 0.34% CuEq (39ppm Mo, 0.024g/t Au) from 0m; including 22m @ 0.71% CuEq (180-202m) and 169m @ 0.40% CuEq (512-681m).
- HM191: 429m @ 0.30% CuEq (57ppm Mo, 0.020g/t Au) from 0m; including 82m @ 0.56% CuEq (314-396m) and 38m @ 0.41% CuEq (54-92m).
- HM186: 369m @ 0.29% CuEq; including 150m @ 0.37% CuEq (0-150m).
- HM192: 411m @ 0.30% CuEq; including 102m @ 0.40% CuEq (6-108m) and 54m @ 0.39% CuEq (172-226m).
- HM189: 648m @ 0.22% CuEq; including 14m @ 0.59% CuEq (434-448m) and 115m @ 0.35% CuEq (455-570m).
- HM182: 324m @ 0.31% CuEq; including 18m @ 0.48% CuEq (176-194m) and 58m @ 0.45% CuEq (0-58m).
The full disclosure includes all 18 holes, acknowledging several instances of lower-grade results. HM198 returned 317m at 0.15% Cu / 0.18% CuEq, a result the company noted is expected to produce a marginal reduction in mineralised tonnage. HMRC012 returned 432m at 0.14% Cu / 0.17% CuEq, with the company stating the trace lies beyond the main mineralisation. HM204 returned 288m at 0.15% Cu / 0.16% CuEq, described as generally low throughout. HM209 returned 249m at 0.15% Cu / 0.17% CuEq. Additionally, in HM200, a high-grade interval predicted between 156m and 300m did not materialise; the company stated the reasons for this are not yet understood but will be assessed.
Two modest positive surprises were flagged as occurring outside or above the current block model. HM205 returned 52m at 0.39% Cu, including 12m at 0.61%, near the surface in northeast Target 3. HMRC015 returned 79m at 0.43% Cu below 400m in Target 2.
Koryx Copper described the results as being in line with expectations and correlating well with the current geological model. The CEO restated that the mineral resource estimate (MRE) update and PFS remain on track for publication before the end of 2026.
Koryx Copper S.A. (KRY) is a pre-PFS explorer and developer with a market capitalization of approximately C$440 million and no revenue. It is neither a producer nor a sub-C$25 million micro-cap. For a company of this size, a drill release typically matters only if it changes the perceived scale, grade, or odds of the Preliminary Feasibility Study (PFS) clearing its hurdle; this release changes none of those three factors.
The recent program is classified as infill and resource-definition work, intended to complete the current drilling phase. The framework for judging such releases requires comparison against the resource grade rather than the gram-metres of a previous headline hole. The March 16, 2026 Mineral Resource Estimate (MRE) reports 0.28% Cu / 0.32% CuEq for Indicated resources and 0.24% Cu / 0.28% CuEq for Inferred resources, with high-grade domains reaching 0.40%/0.39% CuEq. The 18 holes in this batch average approximately 0.30% CuEq on a whole-hole basis, matching resource grade over meaningful intervals. This serves as a confirmation of the existing resource model.
The stock has tripled from C$1.18 on September 22, 2025, to C$3.62 on September 21, 2026. Since March 2026, shares have traded in a C$2.80 to C$3.83 range and are currently approximately 5% below the 52-week high. The last two drill releases produced roughly 3% single-day moves that fully faded within a week. On August 26, 2026, the price moved from C$3.70 to C$3.83, returning to C$3.56 by August 28. On September 9, 2026, it moved from C$3.62 to C$3.74, returning to C$3.41 by September 15. This pattern indicates the market’s revealed reaction to Haib drill news is a small positive pop followed by a fade.
The best composite in this batch, HM199’s 224m @ 0.51% CuEq, is comparable to, but below, the prior batch’s headline composites: HM178’s 318m @ 0.49% CuEq and HM185’s 236m @ 0.57% CuEq reported on August 26, 2026. This comparison would be relevant if the anchor were a discovery hole the market was paying to see repeated. It is not; the anchor is the resource grade, which these holes match. There is no new zone, no new depth extent, no new intrusive centre, and no change in scale. The two outside-model intervals, HM205 near surface in Target 3 and HMRC015 below 400m in Target 2, are described as "expected to improve" and representing a "slight increase in higher-grade tonnage," indicating incremental tonnes rather than new dimensions.
What genuinely changes is that the program is complete. This removes a schedule risk and puts the MRE update and PFS squarely in view for before the end of 2026. This represents deliverable progress on an explicit, dated management promise of 52,000m of conversion drilling by September 2026.
Prior-period financial context, not disclosed in this release, includes C$57.2 million in cash, C$44.4 million in working capital, a nine-month net loss of C$40.6 million, and a nine-month operating cash outflow of C$21.5 million (approximately C$2.4 million per month). Total equity stands at C$46.9 million, with a book value of C$0.39 per share versus a C$3.62 price, roughly 9 times book. The company is funded through the PFS but will need more capital thereafter; the MD&A states it will "continuously require additional financing."
The result is a solid, in-line confirmation that de-risks the PFS timeline, with modest offsetting holes.
Koryx Copper S.A., a Luxembourg-domiciled pre-production copper developer with no revenue, is listed on the TSXV (KRY), NSX (KYX), and OTCQX (KRYXF). The company’s flagship asset is the 100%-owned Haib Copper Project in southern Namibia, a large, advanced Paleoproterozoic porphyry Cu-Mo-Au deposit. It is one of only a few deposits of that age globally, with more than 160,000m drilled since the 1970s by Falconbridge (1964), Rio Tinto (1975), Teck (2014), and Koryx (2021-2026).
An NI 43-101 Mineral Resource effective 16 March 2026, using a 0.15% Cu cut-off, reports Indicated resources of 744Mt @ 0.28% Cu, 63ppm Mo, 0.02g/t Au, and 0.32% CuEq (4,608kt CuEq), and Inferred resources of 579Mt @ 0.24% Cu, 66ppm Mo, 0.02g/t Au, and 0.28% CuEq (3,052kt CuEq). High-grade CuEq domains are reported at 0.40% in the Indicated category and 0.39% in the Inferred category. By-products include 104Mlb Mo and 488koz Au in the Indicated category. The stripping ratio has been reduced to 0.92x from 1.74x.
The conceptual plan outlines a large open pit with approximately 40 Mtpa of sulphide processing via conventional milling and flotation, targeting approximately 100ktpa of copper over a mine life previously cited at 24 years and extended to more than 35 years in the March 2026 update. The sulphide heap leach circuit has been eliminated, while a 3 Mtpa oxide/transitional heap leach has been retained. Concentrate specifications target greater than 20% Cu with 0.8-1 g/t Au (primary) and 10-15% Cu with greater than 3% Mo (secondary).
Regarding studies and permitting, a Preliminary Economic Assessment (PEA) was filed in September 2025, and an updated Mineral Resource Estimate (MRE) was filed in May 2026. A maiden Preliminary Feasibility Study (PFS) is targeted for Q4 2026. An Environmental Clearance Certificate (ECC) application is targeted for mid-2026, with approval expected in H1 2027. A mining licence application has been submitted, and Exploration Permit (EPL) 3140 was renewed to July 2027.
Koryx Copper also holds an 80% interest in Koryx Copper Zambia Ltd, encompassing the Luanshya West and Mpongwe licences on the Zambian Copperbelt. These are grass-roots projects where maiden drilling of 2,500m commenced in late September 2026.
The company has approximately 121.5M shares outstanding (basic), C$57.2M in cash, and C$44.4M in working capital, based on prior-period context for the nine months ended 2026-05-31. Notable holders include Ross Beaty, Resource Capital Funds, Mackenzie Investments, and Namibian high-net-worth investors. Management includes President & CEO Heye Daun, Chairman Alan Friedman, and CFO Tony Da Silva. The board includes Charles Loots, Alfredo Luis Riviere Rodriguez, Cristina Lara, and Tarik El Hanch. COO Trevor Faber departed in May 2026, with a succession process underway, and Aideen McDermott was appointed Head of IR in August 2026.