LUCA MINING ANNOUNCES ACQUISITION OF THE COZAMIN MINE, CREATING A LEADING POLYMETALLIC PRODUCER
Luca’s acquisition of Cozamin doubles production capacity while securing five-year reserves and a fifty percent silver stream.
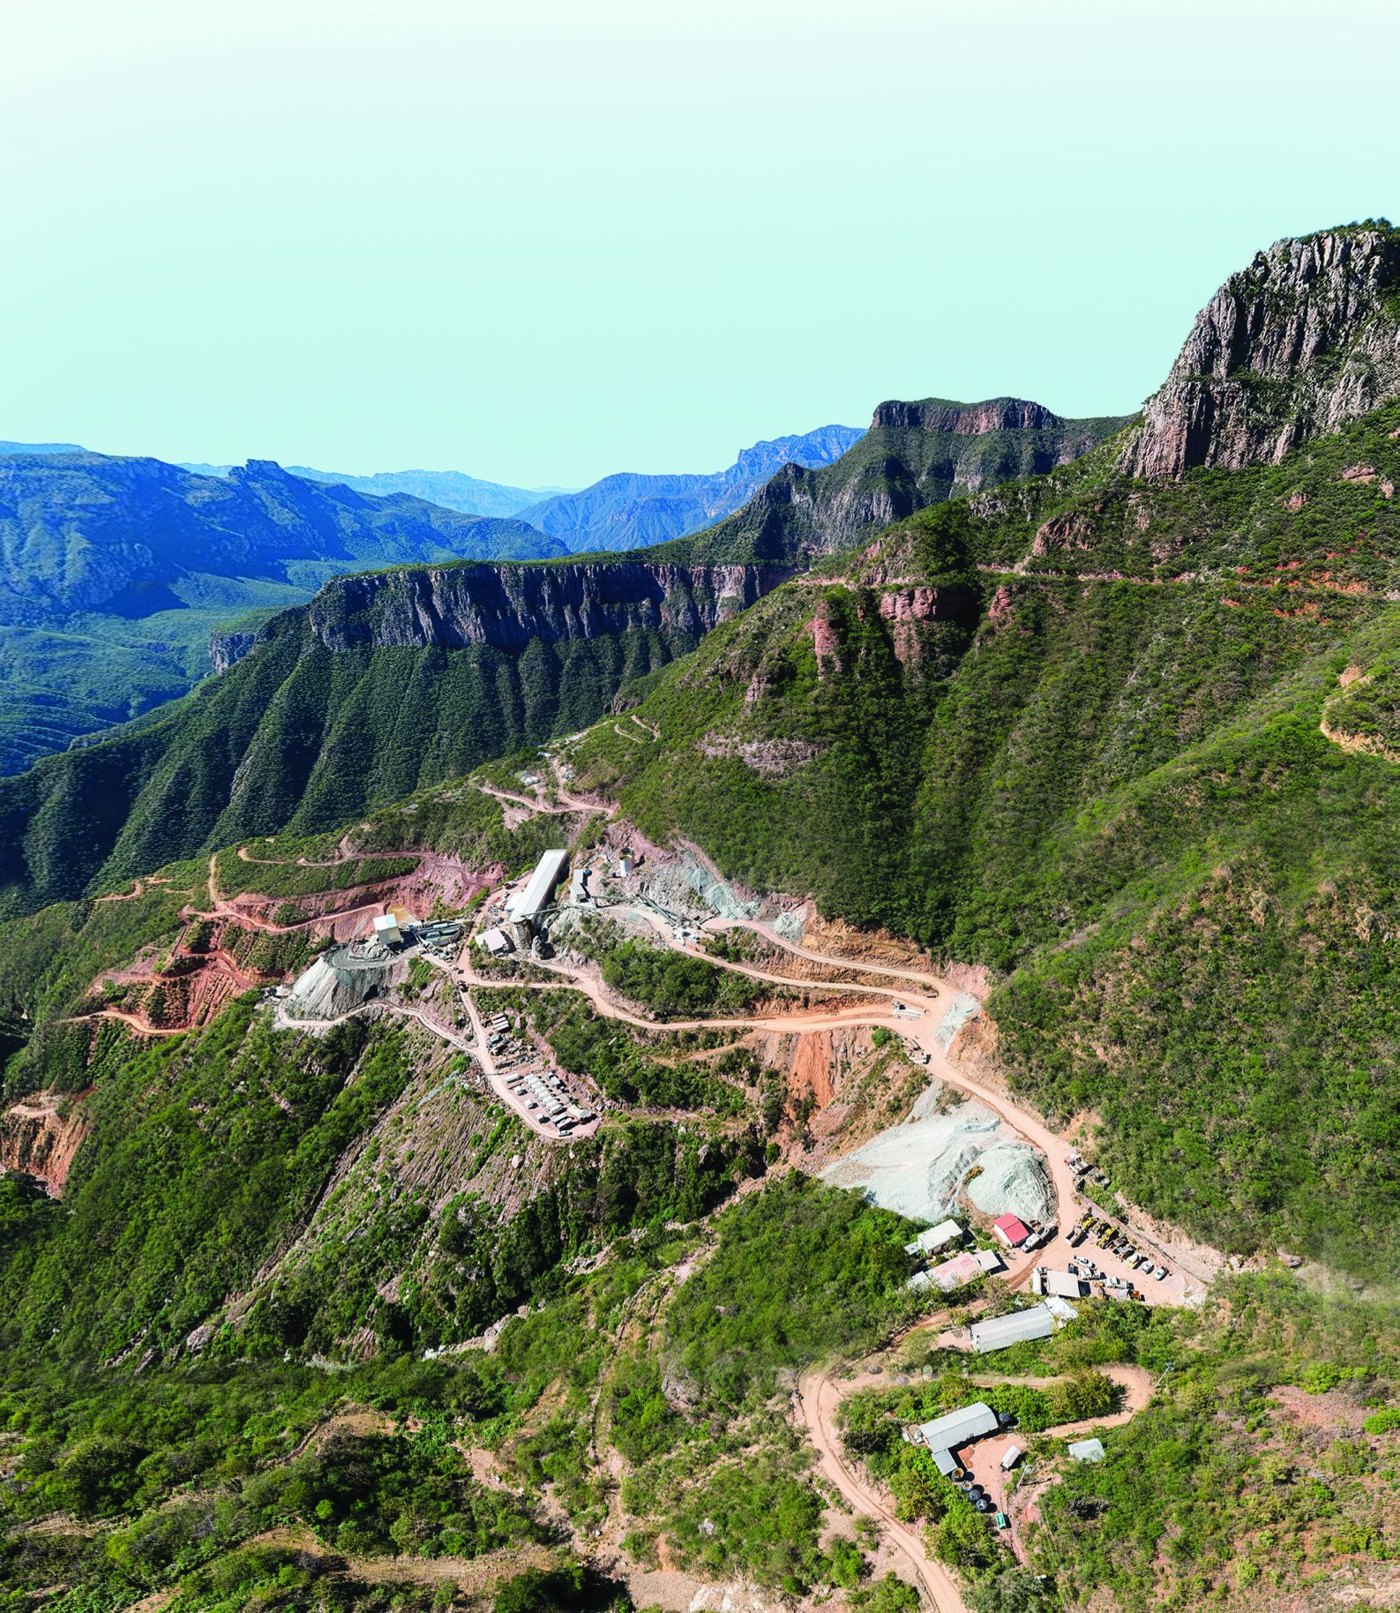
Luca Mining Corp. (LUCA) has signed a definitive share purchase agreement dated September 21, 2026, with Capstone Copper to acquire 100% of the Cozamin underground copper-silver mine in Zacatecas, Mexico. The transaction carries a base consideration of $290 million, comprising $275 million in cash on closing plus $15 million satisfied in Luca shares at the Issue Price of C$1.00. An additional $35 million is deferred payable on the first anniversary, at Luca's election in cash or shares. Up to $60 million in contingent payments is tied to average LME copper prices in 2027, 2028, and 2029. These contingent terms include $10 million if copper is greater than or equal to $7.00/lb, $15 million if greater than or equal to $7.76/lb, and $20 million if greater than or equal to $8.51/lb. The payments are inclusive of each other, with only one payment due per year, bringing the maximum total consideration to up to $385 million.
To finance the deal, Luca has secured a $300 million package. This includes a $110 million (C$155 million) bought-deal private placement of 155,000,000 subscription receipts at C$1.00, led by National Bank, with a Trafigura equity backstop of up to $75 million capped at 19.9% of pro forma voting securities. A $40 million (C$56 million) concurrent private placement involves Wheaton and Taurus, alongside a $125 million senior secured acquisition facility from Taurus and Macquarie. Additionally, the package includes a $25 million incremental silver stream from Wheaton.
The loan terms span four years, with Tranche A at $75 million carrying an interest rate of 8.5% per annum and Tranche B at $50 million priced at SOFR + 4.9%. Principal repayment occurs in equal quarterly installments commencing six months after closing, with prepayment allowed without penalty after 12 months. As part of the financing, Luca issues 21.5 million non-transferable warrants at C$1.20 with a four-year term to Taurus and Macquarie. The incremental silver stream requires Wheaton to receive 15% of refined silver delivered until 500,000 ounces have been delivered, at an ongoing payment of 10% of spot silver. Downside protection reduces the production payment, potentially to zero, if silver falls below $60/oz. On financial closing, Luca will enter 36-month forward-curve LME copper hedges with Macquarie covering 25% of forecasted Cozamin copper sales from 2027.
The Cozamin asset has maintained continuous production since commercial production began in August 2006. Operations utilize two ramp declines plus the San Roberto shaft, employing longitudinal and transverse longhole stoping and mechanized cut-and-fill methods. The crush-grind-sequential flotation capacity reaches up to 4,400 tpd, with average throughput of approximately 3,670 tpd over the past five years. Mine production, rather than milling, is the current constraint. Mineralization occurs across the Mala Noche Vein, mapped with a strike of at least 5.5 km and drill-tested to roughly 1,500 m depth, and the higher-grade Mala Noche Footwall Zone, which has more than 2.5 km of strike, extends 200-1,000 m down dip, and is drilled to approximately 1,450 m. Both zones remain open at depth and along strike, including below the MNFWZ, at the MNV West target, and toward zinc mineralization east of San Rafael.
Technical data are historical Capstone estimates as of December 31, 2025, disclosed in Capstone's 2025 AIF and a January 1, 2023 technical report. Mineral Resources total 17.5 Mt Measured & Indicated at 1.29% Cu, 44 g/t Ag, 1.22% Zn, and 0.45% Pb, plus 13.5 Mt Inferred at 0.72% Cu and 39 g/t Ag. These underpin Proven & Probable Reserves of 6.7 Mt at 1.40% Cu and 42.2 g/t Ag. Luca explicitly does not treat these as current NI 43-101 estimates and will file a supporting technical report within 180 days. While the historical mine plan supports mine life through 2030, Luca has not adopted this plan and will develop an updated plan after verifying technical information.
Pre-existing stream and royalty terms include a Wheaton stream from Capstone's $150 million, 2020 transaction, which takes 50% of refined silver, stepping down to 33% for the life of mine after 10 moz silver is delivered. 3.4 moz had been delivered as of June 30, 2026. Reserve NSR formulae reference net smelter return royalties of 1-3%, with specific royalty percentages not itemized. Pro forma claims, sourced to third-party estimates, project 2027 net revenue of approximately $598 million versus Luca's 2025 net revenue of $177 million. 2027 operating cash flow is estimated at approximately $223 million versus Luca's 2025 operating cash flow of $37 million. Operating cash flow per share is expected to rise from $0.22 to $0.42 (+93%), and unlevered free cash flow is projected to improve by approximately $139 million, or $0.28 per share, from ($12 million) to $127 million in 2027.
Closing is expected in Q4 2026, subject to Mexican Federal Antitrust Commission (COFECE) and TSXV approvals. The subscription receipt escrow release deadline is February 28, 2027, extendable by up to two successive one-month periods solely for failure to obtain regulatory approvals, after which escrowed funds are returned to subscribers and receipts cancelled
Luca Mining Corp. (LUCA) announced a transformative acquisition of Cozamin’s El Barqueño mine for $290 million upfront, plus $35 million in deferred consideration and $60 million in contingent payments. The transaction, funded through a $125 million secured facility and an equity issuance representing over 84% of shares outstanding, marks a significant departure from the company’s previously debt-free balance sheet. This deal follows the September 17, 2026, acquisition of El Barqueño, which signaled management’s expansionist intent, but this new transaction is an order of magnitude larger and was not anticipated by the market.
The pro forma financial impact is substantial. Luca projects 2027 net revenue of approximately $598 million, up from $177 million in 2025, and operating cash flow of approximately $223 million compared to $37 million in 2025. The company claims per-share accretion of 93% on operating cash flow. The acquisition adds a third mine, a second jurisdiction within Mexico, and shifts the commodity weighting toward copper. El Barqueño is a brownfield asset with existing infrastructure and permits, supported by the addition of named strategic shareholders.
However, the pro forma figures are third-party estimates rather than company guidance. Visible Alpha data for Cozamin and street consensus for Luca were used, and the figures are subject to a "future-oriented financial information" disclaimer with no update obligation. Comparing 2027 pro forma results against 2025 actuals may flatter the growth rate relative to Luca’s own 2026 run-rate, where H1 2026 revenue was $116.0 million.
The valuation has drawn scrutiny. At $290 million upfront for a mine with 6.7 Mt of reserves at 1.40% Cu (approximately 207 million pounds of contained copper), the cost is roughly $1.40 per contained reserve pound before any silver credit, deferred payments, contingent payments, or operating costs. At a processing rate of 3,670 tpd, the 6.7 Mt represents about five years of mill feed, with the historical plan running only to 2030.
A material gap in the disclosure is the absence of Cozamin operating costs. The release does not disclose cash costs, all-in sustaining costs (AISC), head grades, realized recoveries by year, sustaining capital, or production volumes. Without this data, the pro forma cash flow numbers cannot be audited, and the buyer's underwriting cannot be verified.
Internal inconsistencies also appear in the accretion calculations. The unlevered free cash flow line indicates an incremental $139 million, or $0.28 per share, implying a pro forma share count of about 496 million. Applying that same share count to the cash flow per share (CFPS) line, which shows a $0.20 per share uplift, implies only about $99 million of incremental operating cash flow. The release does not state the pro forma share count or reconcile these two measures.
The stock closed at C$1.04 on September 18, 2026, having drifted down 10% from C$1.16 on September 3 and 49% below the January high. There is no evidence of pre-positioning for a positive deal reaction, as the market has recently punished capital deployment rather than rewarding it. The transaction introduces a roughly 84% increase in shares outstanding and shifts Luca from a debt-free position to meaningful leverage, against a projected doubling of production and cash flow.