StrikePoint Announces Agreement to Purchase the Northumberland Project, a Gold Deposit in Nevada's Walker Lane, from Newmont Corporation
Strikepoint acquires Newmont’s Northumberland project for us$70m alongside a c$140m capital raise.
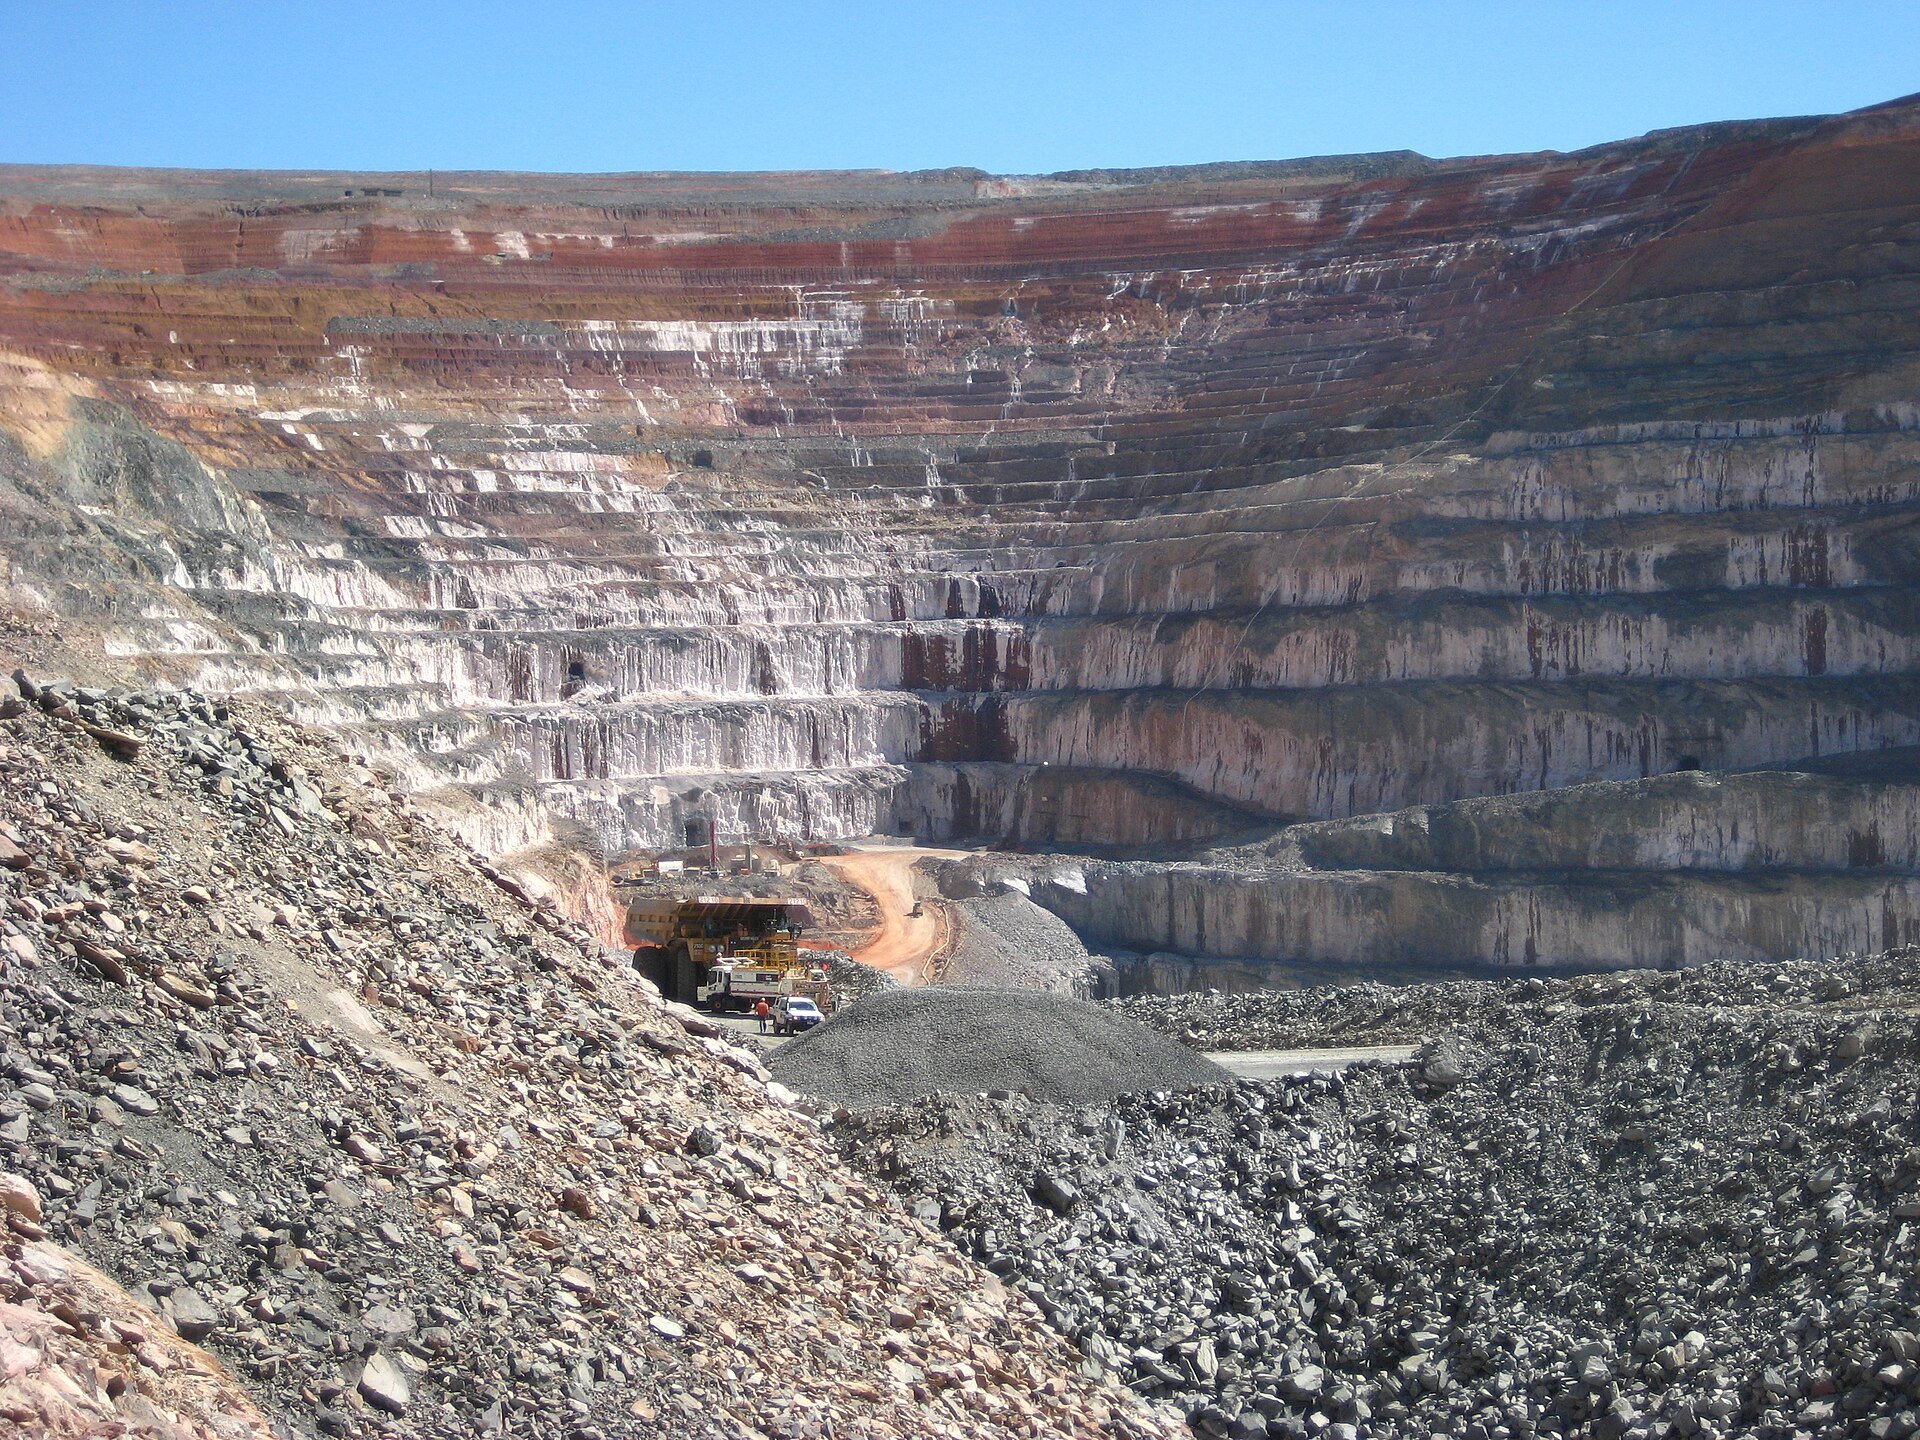
StrikePoint Gold Inc. (SKP) announced on August 18, 2026, a definitive agreement to acquire the Northumberland Gold Project in Nevada’s Walker Lane from Newmont USA Limited and Fronteer Development LLC, subsidiaries of Newmont Corporation. The transaction is classified as a Fundamental Acquisition under TSXV Policy 5.3, is arm’s length, and does not require shareholder approval. Closing is anticipated on or about the end of September 2026, with trading expected to remain halted pending completion.
The purchase price consists of US$70 million in cash at closing, plus two contingent cash payments of US$25 million each: one within 120 days after completion of a Feasibility Study, and one within 120 days after achieving certain commercial production milestones. The release includes an initial independent Mineral Resource Estimate for Northumberland, effective July 31, 2026, prepared by SLR Consulting. The resource is based on historical drilling by previous operators, comprising 1,511 reverse-circulation holes and 37 core holes. StrikePoint has not yet drilled Northumberland. The company states that Northumberland is a past-producing gold deposit, largely on private land, with five drill permits in place, and that the property has not been explored since approximately 2010.
The Mineral Resource Estimate is reported within an optimized pit shell using 45-degree overall pit slope angles, US$2.12 per tonne mining cost, US$1.35 per tonne G&A, and processing costs of US$12 per tonne for oxide and US$30 per tonne for sulphide material. AuEq calculations use US$3,500 per ounce gold and US$55 per ounce silver, with variable cut-off grades by metallurgical domain: 0.16 g/t oxide, 0.31 g/t fresh low preg-robbing, 0.35 g/t fresh medium preg-robbing, and 0.47 g/t fresh high preg-robbing. Metallurgical recovery assumptions are oxide 75% Au and Ag; fresh low preg-robbing 90% Au and 70% Ag; fresh medium preg-robbing 80% Au and 60% Ag; fresh high preg-robbing 60% Au and 40% Ag.
The resource estimates are as follows:
- Indicated resource: 67,008 kt at 1.26 g/t Au and 5.38 g/t Ag, containing 2,709,000 oz Au and 11,599,000 oz Ag, equivalent to 2,857,000 oz AuEq at 1.33 g/t AuEq.
- Inferred resource: 30,967 kt at 1.53 g/t Au and 4.28 g/t Ag, containing 1,519,000 oz Au and 4,260,000 oz Ag, equivalent to 1,568,000 oz AuEq at 1.58 g/t AuEq.
Concurrent with the acquisition, StrikePoint announced a bought deal private placement of 70,000,000 subscription receipts at C$2.00 each for gross proceeds of C$140 million, led by Canaccord Genuity. Canaccord has an option to purchase additional subscription receipts for up to C$21 million, exercisable up to 48 hours before closing of the brokered offering. Each subscription receipt entitles the holder to receive one post-consolidation common share upon satisfaction of escrow release conditions, including TSXV approval and closing of the Northumberland transaction. Gross proceeds, less certain underwriter expenses, will be held in escrow. If escrow release conditions are not satisfied by 45 days after closing of the brokered offering, funds are returned and subscription receipts are cancelled.
The company also announced a non-brokered private placement of up to C$2 million at C$0.20 per unit, described as C$2.00 on a post-consolidation basis. Each non-brokered unit includes one share and one-half of one warrant. Each whole warrant is exercisable at C$0.30 per share, described as C$3.00 post-consolidation, for three years from closing. StrikePoint announced a 10-for-1 share consolidation, subject to TSXV approval.
Alan Pangbourne will join the board as Chairman upon completion of the transaction. Shawn Khunkhun will remain as a director but is described as outgoing Executive Chairman. The company entered into C$500,000 of non-interest-bearing, due-on-demand promissory notes with certain individuals, including non-arm’s-length parties, to pay claim maintenance fees for Hercules and Cuprite. The loan is expected to be repaid from the non-brokered offering proceeds. This is not an earnings release. References to financial statements below are prior-period context, not new information disclosed in today’s release.
StrikePoint Gold Inc. (SKP) has announced a transaction that significantly alters its asset base and market capitalization, shifting from a small pre-revenue junior explorer focused on the Hercules and Cuprite projects to a holder of the Northumberland past-producing gold deposit. Prior to this release, the company’s market capitalization was estimated at roughly C$9 million to C$10 million. The acquisition replaces Hercules, an exploration-stage project with no mineral resource, with Northumberland, which carries an initial indicated resource of 2.86 moz AuEq and an inferred resource of 1.57 moz AuEq.
The transaction is materially larger than any previously announced by the company. While the February 2026 Como district acquisition involved staged payments totaling US$300,000 plus US$5 million in milestone payments and a royalty, the Northumberland deal involves US$70 million upfront and US$50 million in contingent payments. To support this, StrikePoint is undertaking a C$140 million bought deal, a figure that is extremely large relative to the company’s prior market capitalization and its previous C$3.1 million LIFE financing.
The deal deviates from historical management focus, which had centered on drilling Hercules and targeting a maiden resource. There was no prior disclosure in the news flow indicating an acquisition of this scale. If completed, the transaction provides StrikePoint with a large Nevada resource base, private land, past-producing infrastructure, existing drill permits, and a potential development pathway. However, the news is also highly dilutive and conditional. Subscription receipts convert into 70 million post-consolidation shares, while the pre-deal share count of 62,392,382 would become approximately 6,239,238 post-consolidation shares after the 10-for-1 consolidation.
On simple arithmetic, if only the base C$140 million offering is completed, existing shareholders would own approximately 8.2% of the post-financing company before considering the non-brokered placement, underwriter option, warrants, and options. The C$2.00 post-consolidation offering price is equivalent to C$0.20 pre-consolidation, which is above the last traded price of C$0.15. This sets an important reference price, but it does not guarantee market pricing after trading resumes.
The acquisition price can be compared to the resource base using simple arithmetic, although resources are not reserves and economic viability has not been demonstrated.
- US$70 million upfront divided by 2.857 moz indicated AuEq is approximately US$24.5 per indicated AuEq ounce.
- US$70 million upfront divided by total indicated plus inferred AuEq of 4.425 moz is approximately US$15.8 per AuEq ounce.
- Total potential consideration of US$120 million divided by total indicated plus inferred AuEq of 4.425 moz is approximately US$27.1 per AuEq ounce.
These arithmetic resource-acquisition metrics appear optically inexpensive, but they must be discounted heavily for metallurgy, preg-robbing, permitting, financing, development capital, and the fact that there are no mineral reserves. The resource estimate has meaningful technical caveats. Preg-robbing and sulphur coverage is sparse relative to the assay database, some metallurgical composites are not tied to specific drill intervals, density data for disturbed materials is limited, and no geotechnical support is presented for the assumed 45-degree pit slopes. The estimate also relies on high metal price assumptions: US$3,500 per ounce gold and US$55 per ounce silver. Lower metal prices would increase cut-off grades and could reduce the resource materially.
The financing structure introduces closing risk. If escrow release conditions are not satisfied within the required timeframe, subscription receipts are cancelled and funds are returned. In that scenario, the transaction may fail and the company would remain a much smaller, undercapitalized explorer with going-concern risk.
Additionally, the appointment of Alan Pangbourne as Chairman is viewed as a positive governance and credibility item, given his background including senior roles at Guyana Goldfields, SSR Mining, Kinross, and BHP Billiton. However, no direct investment amount by him is disclosed. Conversely, the C$500,000 demand loan to pay claim maintenance fees is a negative liquidity signal, showing that even after the November 2025 C$3.1 million financing, the company needed short-term related-party funding to maintain projects.
If the transaction and financing close, the news is material and transformational. If they fail, the news becomes materially negative because the company’s going-concern risk and dilution concerns return to the forefront.
StrikePoint Gold Inc., a Vancouver-based pre-revenue junior gold exploration company listed on the TSX Venture Exchange under SKP and quoted on the OTCQB under STKXF, has shifted its strategic focus following an announced transaction. While the company’s primary focus prior to this release was the Hercules Gold Project in Nevada’s Walker Lane, with Cuprite as another Nevada exploration property, the company’s strategy outlined in its January 2026 investor presentation was to concentrate on low-cost, open-pit heap-leach gold projects in Nevada to convert exploration targets into resources that could be advanced or sold. Following the transaction, Northumberland becomes the intended flagship project, subject to closing.
The Northumberland Gold Project is located approximately 150 kilometers by road from Tonopah, Nevada, in the Walker Lane. Described as a past-producing gold deposit largely located on private land, the mineralization is characterized as Carlin-style. The project includes claims, fee lands, licenses, permits, and equipment. Five drill permits are stated to be in place, subject to transfer or replacement requirements after closing. The deposit was discovered in the late 1800s, with significant oxide mineralization discovered in the 1930s and intermittent mining until 1991. Fronteer Gold acquired the interest in 2007, and Newmont acquired Fronteer, including Northumberland, in 2011. The release states that Northumberland has not been explored since approximately 2010 and has untested near-pit, in-pit, and regional targets. The initial resource estimate is based on historical drilling by Cyprus Mines Corporation, Western States Minerals Corporation, Newmont USA Limited, and Fronteer Development Group Inc. StrikePoint has not yet drilled or explored Northumberland.
Regarding the Hercules Gold Project, the company acquired the asset in August 2024 for C$250,000. The project had an exploration target of 40.3 million to 65.6 million tonnes at 0.48 to 0.63 g/t Au, equivalent to approximately 819,000 to 1,019,000 ounces of gold. The company commenced a 2026 RC drill program and completed 29 holes totaling approximately 3,918 meters. Notable prior drill results include:
- H26004 cutting 114.30 meters grading 0.69 g/t Au and 5.03 g/t Ag
- H26005 cutting 67.06 meters grading 0.53 g/t Au and 11.69 g/t Ag, including 7.62 meters grading 2.93 g/t Au and 54.48 g/t Ag
Prior releases described Hercules mineralization as predominantly oxide and potentially suitable for heap-leach scenarios, but no mineral resource has been reported for Hercules in the provided materials. A maiden Hercules resource estimate was targeted for Q4 2026 in prior news, while prior MD&A context also referenced a goal before the end of 2026.
In the Como Mining District, StrikePoint agreed in February 2026 to acquire 51 unpatented claims from Fronteer Development USA LLC, a Newmont subsidiary. The consideration included staged cash payments totaling US$300,000, milestone payments of US$1.5 million upon a PEA and US$3.5 million upon commercial production, and a 1.5% NSR royalty to Newmont with a buy-down to 1.0% for US$1 million, plus a right of first refusal.
Cuprite remains an earlier-stage Nevada exploration project. Prior MD&A context indicated an updated Cuprite technical report was planned for Q2 2026, but the current release does not provide new Cuprite details.
Regarding royalty status, no royalty is disclosed for Northumberland in the release, and it cannot be confirmed as royalty-free based on the provided materials. For the Como district at Hercules, Newmont retains a 1.5% NSR royalty, buyable down to 1.0% for US$1 million, and a right of first refusal. No royalty information is provided for Cuprite.