Hemlo Mining Corp. Reports Third Quarter 2026 Financial and Operating Results
Hemlo’s high AISC of $2,660/oz and missing 2026 guidance stall the ramp-up story.
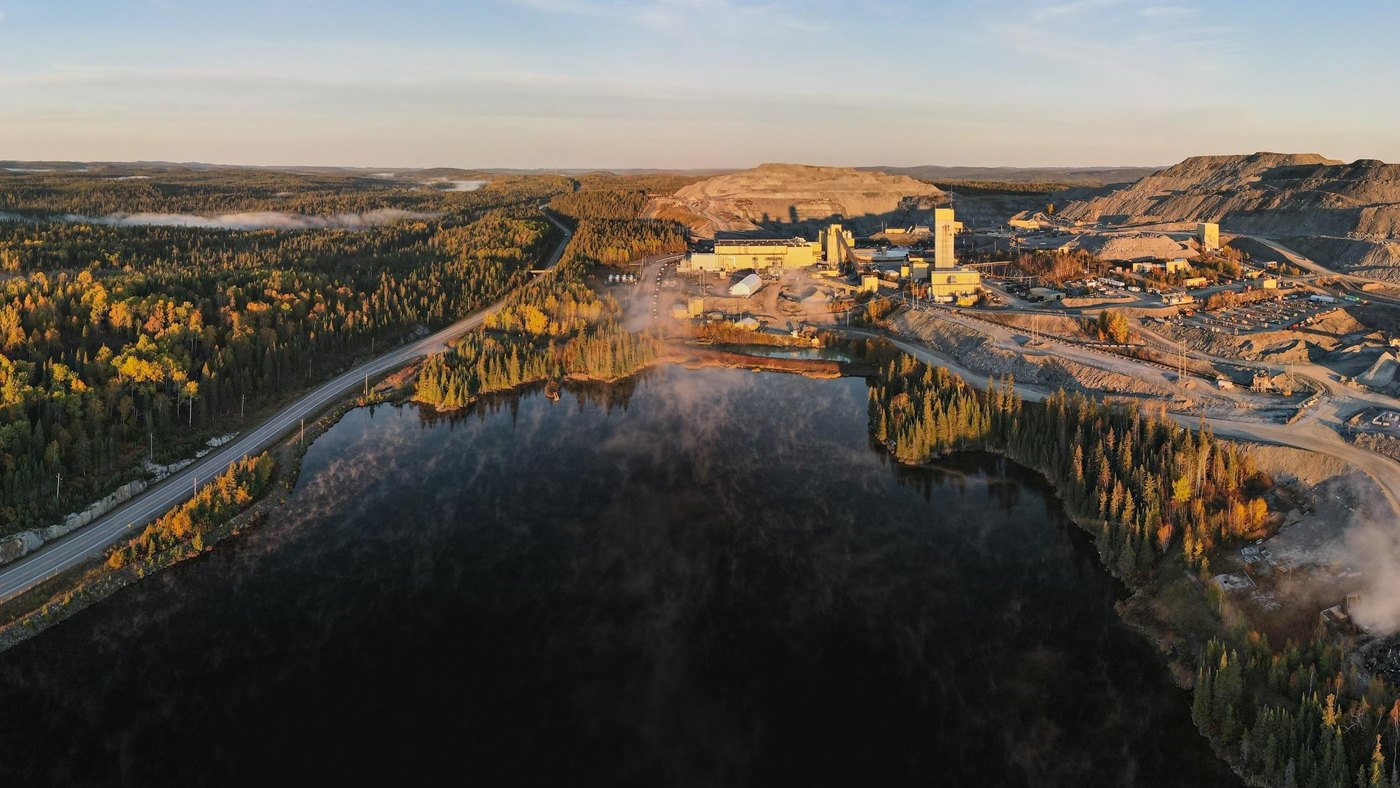
Hemlo Mining Corp. (HMMC) reported third-quarter 2026 financial results for the period ended September 30, 2026, with all figures in US dollars. The company generated $135.5 million in revenue from the sale of 32,424 gold ounces on a 100% basis, at an average realized price of $4,234 per ounce. Net income was $3.5 million, or $0.01 per share, while adjusted net income reached $15.6 million, or $0.05 per share. EBITDA stood at $51.6 million.
Cash from operating activities totaled $54.6 million, compared to $39.5 million in cash flow from operations before working capital changes. Attributable production was 25,652 ounces, with attributable gold sales of 29,830 ounces and recoveries at 95.0%. Site attributable cash costs were $1,799 per ounce sold, down from $1,880 in the second quarter, while site attributable all-in sustaining costs (AISC) rose to $2,660 per ounce sold from $2,561. Sustaining capital expenditures increased to $25.1 million from $17.5 million in the prior quarter, while growth capex decreased to $4.0 million from $6.9 million. The company held $144.8 million in cash, resulting in a net cash position of $2.3 million.
For the nine-month period, Hemlo Mining reported revenue of $464.2 million, net income of $56.2 million ($0.19 per share), and adjusted net income of $75.6 million ($0.26 per share). EBITDA was $215.4 million, with operating cash flow of $178.1 million. Attributable production for the nine months was 80,539 ounces, with an AISC of $2,324 per ounce.
Corporate developments included the company’s inclusion in the GDXJ index on September 18, DTC eligibility, and the appointment of Martin Rioux as Vice President of Human Resources.
The October 21 operating release had already disclosed tonnage of 342,000 tonnes, grade of 3.00 g/t, output of 29,617 ounces (25,652 ounces attributable), the Williams/Interlake split, and a substation incident. The current release provides new data on cost structure, earnings and cash-flow quality, and a step-up in capital expenditures. It also confirms that 2026 operating and cost guidance, previously promised, has not yet been issued. The release contains no production guidance, cost guidance, reserve or resource update, or quantified ramp-up timetable toward the 4,800 tonnes per day Phase 1 target described in the investor deck.
Management characterized the quarter as resilient, citing higher-grade ore from Interlake supporting stable production. The 100%-owned Williams mine produced less gold than in the second quarter, while the grade uplift originated from an asset where 50% of profits accrue to Franco-Nevada.
Hemlo Mining Corp. (HMMC) reported an all-in sustaining cost (AISC) of $2,660 per ounce for the third quarter, a 3.9% increase from the previous quarter and 23.3% above the $2,157 per ounce average recorded in the first half. The rise in AISC was driven entirely by an increase in sustaining capital expenditures, which climbed from approximately $618 per ounce in the second quarter to roughly $795 per ounce in the third quarter. This figure, calculated using Williams sustaining costs of $22.4 million plus 50% of Interlake’s $2.6 million divided by 29,830 attributable ounces, marks the second consecutive quarterly increase. The company provided no guidance against which to measure this performance, though the study basis stands at $1,395 per ounce.
Headline operating cash flow was reported at $54.6 million, a figure management noted was influenced by $14.8 million in collection timing related to 3,721 ounces sold at the end of the second quarter. Cash flow before changes in working capital stood at $39.5 million. Net income of $3.5 million was impacted by $10.1 million in other expenses, comprising a $6.5 million non-cash loss on contingent consideration revaluation and a $3.6 million loss on gold derivatives. Additionally, finance costs, including stream accretion, totaled $9.0 million. The effective tax rate reached 78%, with $12.4 million in income tax levied on $15.8 million in pretax income, a result of the contingent consideration loss being non-deductible.
The company did not provide guidance for 2026, despite having promised to do so in the third quarter. Hemlo Mining Corp. reported third-quarter results in November without outlining the costs or timeline for ramping production to 4,800 tonnes per day and 6,000 tonnes per day.
Hemlo Mining Corp. shares closed at C$6.85 on August 11, prior to the earnings release, and peaked at C$8.38 on September 11. The stock fell 11.4% on October 22, the day after the operating pre-release, and bottomed at C$4.63 on November 3, representing a 36.8% decline from the peak.
Hemlo Mining Corp. (HMMC) is a single-asset Canadian gold producer centered on its flagship Hemlo Gold Mine, located approximately 35 km east of Marathon in northwestern Ontario. The site sits on the Trans-Canada Highway and benefits from rail access and grid power. Since operations began in 1985, the mine has produced approximately 25 million ounces of gold.
The company acquired the asset from Barrick for an aggregate consideration of up to US$1.1 billion, with the transaction closing on November 26, 2025. The acquisition was executed by the entity formerly known as Carcetti Capital Corp., which underwent a two-thirds share consolidation, resulting in 296.3 million shares outstanding.
Production is derived from two sources: the 100%-owned Williams mine and the Interlake claims, which are subject to a 50% net profits interest payable to Franco-Nevada, attributable at 50%. The mine’s infrastructure includes a mill with a permitted capacity of 13,500 tonnes per day (tpd) and a current capacity of approximately 10,000 tpd, featuring two independent grinding lines. Hoisting capacity stands at approximately 6,000 tpd of ore. Current throughput is approximately 3,720 tpd, representing roughly 37% of permitted mill capacity and 52% of hoisting capacity.
The company’s land package totals approximately 45,000 hectares across the Hemlo camp. This includes the Hemlo Mine Property of approximately 10,000 hectares, Hemlo North of approximately 12,000 hectares, and the Pic Property of approximately 23,000 hectares, which hosts the Beggs and Wire deposits.
Hemlo Mining employs 555 full-time workers and 373 contractors, with approximately 75% of the workforce drawn from surrounding communities. The company transitioned from a contractor to an owner-operator model on March 16, 2026, with 97% of the contractor workforce accepting positions.
Management is led by President, CEO, and Director Jason Kosec, alongside CFO Jon Case, COO Eric Tremblay, VP Exploration and Qualified Person Raphael Dutaut, VP Operations and General Manager Garett Macdonald, and VP Engineering and Projects and Qualified Person Mike Tsafaras. The board of directors includes Executive Chair Jonathan Awde, Lead Director Dr. Robert Quartermain, and directors Eva Koci, Glenn Kumoi, Audra Walsh, and Tom Yip.