Tintina Mines Intersects 460m at 0.50% CuEq at the Dos Amigos Copper-Gold Project in Chile
Tintina’s first infill hole confirms low-grade porphyry mineralisation with no scale change at the project.
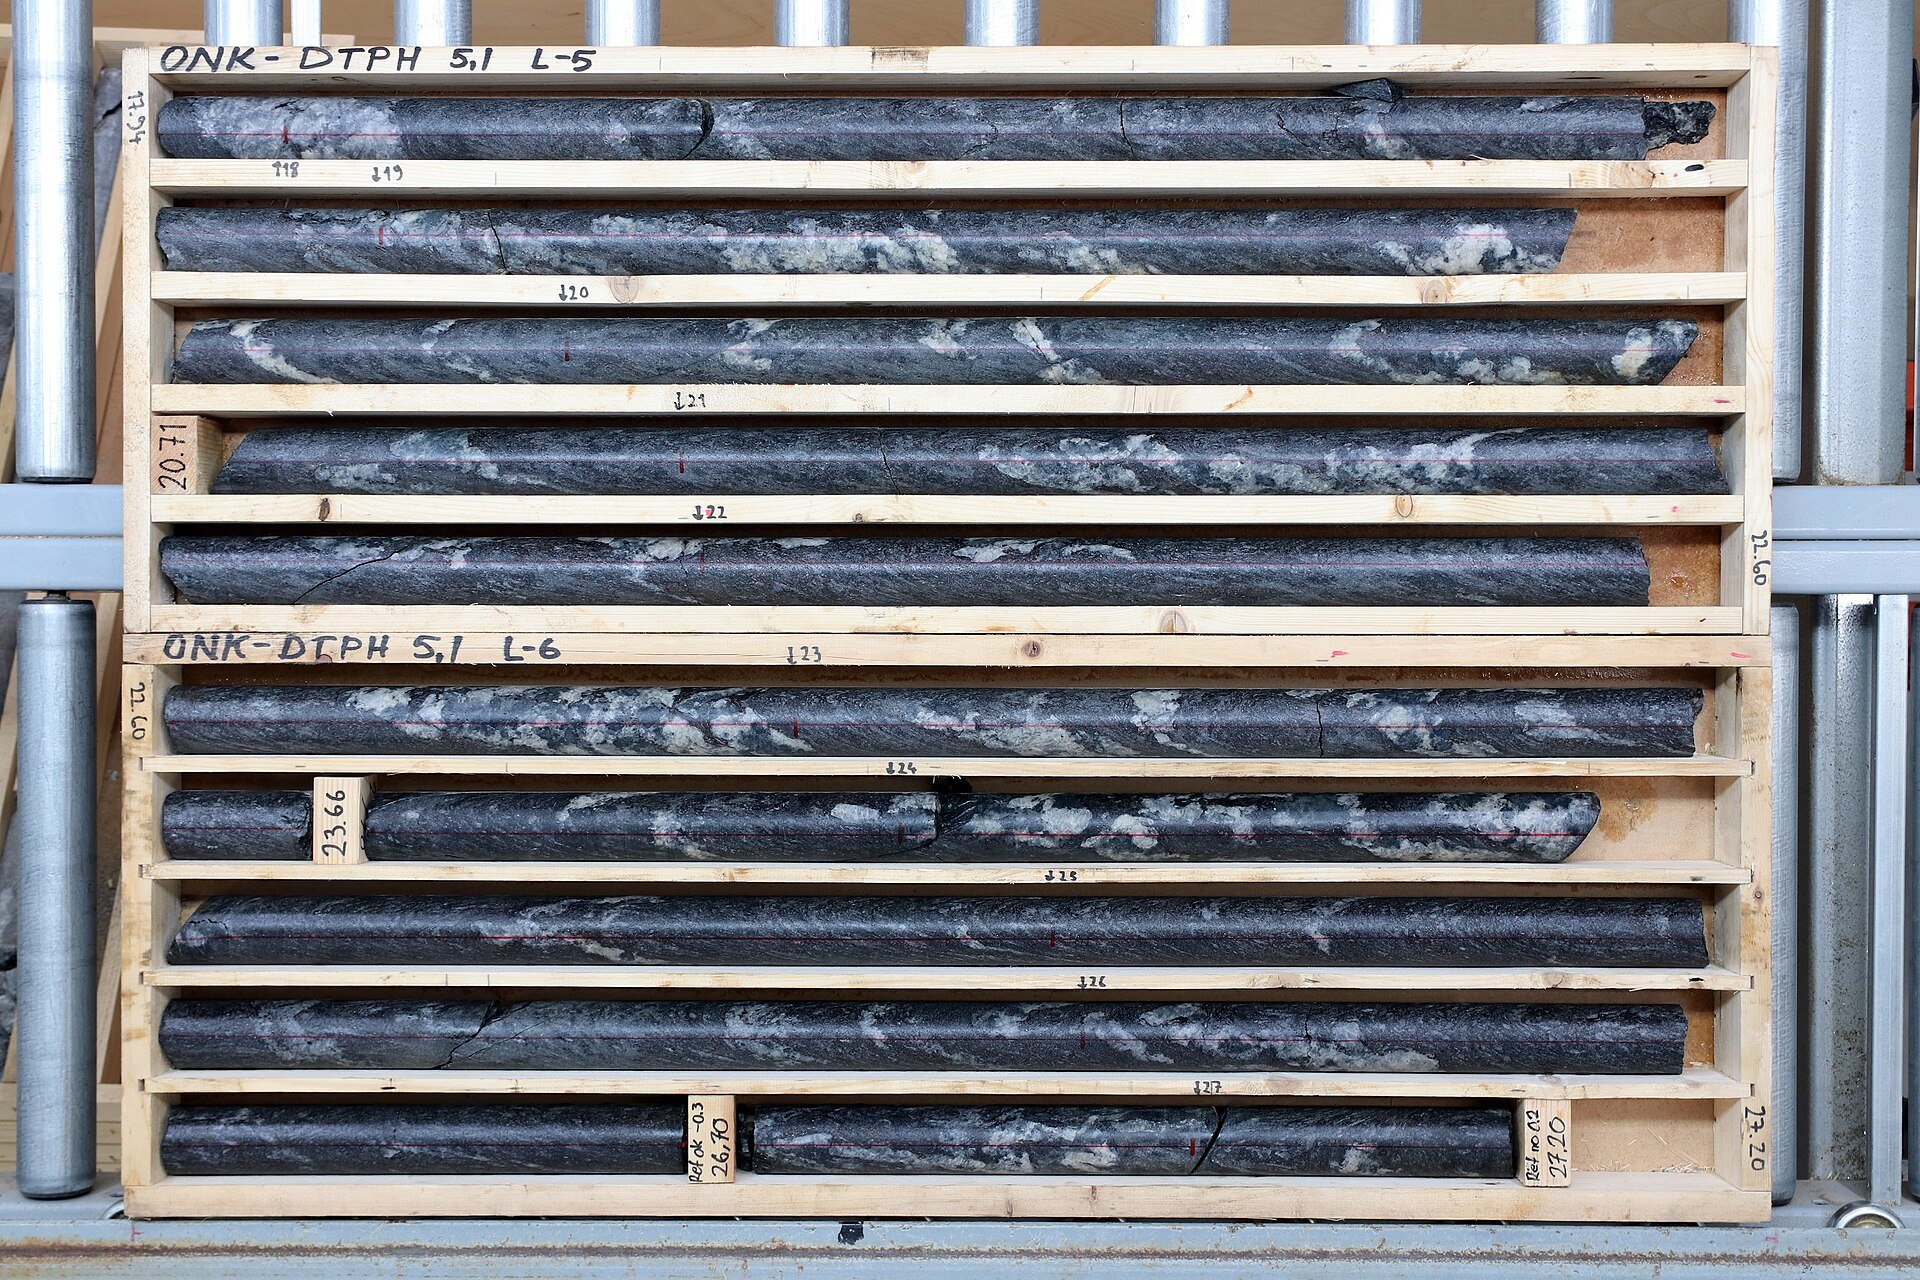
Tintina Mines Ltd. (TTS) reported initial 2026 drilling results from its wholly owned Dos Amigos copper-gold project in Chile. The release details data from a single hole, SDDK26-001, which returned 460m from 200m to end-of-hole at 660m grading 0.31% Cu and 0.24 g/t Au, or 0.50% CuEq using the company’s disclosed Sep 2026 consensus prices and PEA recoveries.
Nested higher-grade intervals within the same 460m include: - 112m at 0.55% CuEq from 200m - 26m at 0.41% CuEq from 328m - 98m at 0.63% CuEq from 380m - 166m at 0.50% CuEq from 494m
The cutoff is 0.2% Cu with up to 10m internal dilution. True width is not determined; the release says there is insufficient information on zone orientation.
The hole was collared west of the interpreted Dos Amigos porphyry/pre-cursor intrusion contact and drilled east at about 74 degrees dip. It passed low-grade phyllic alteration to about 200m, then contact breccia, then more abundant M- and A-type veins with potassic alteration and magnetite.
The company says the result correlates with the block model used in the 2026 PEA and supports continuity in an area previously interpreted as low-grade. Three rigs are operating, with a fourth arriving. Drilling is aimed mainly at converting Inferred resources to Indicated.
QA/QC is disclosed: ALS Global, ISO/IEC 17025, Cu-AA62 four-acid copper, Au-AA23 30g fire assay, ME-ICP41 multi-element, certified standards, coarse and fine blanks, quarter-core duplicates and pulp duplicates. The QP is James Purchase, P.Geo., VP Exploration, who is not independent.
Tintina Mines Ltd. (TTS) is a development-stage copper-gold company that is neither a grassroots explorer nor a producer. Its equity is currently valued based on the Dos Amigos resource, the 2026 Preliminary Economic Assessment (PEA), a C$91 million strategic financing, a partnership with Sumitomo, Gignac, and Franco-Nevada, and the path toward permitting, feasibility, and final investment decision.
The existing resource base is substantial, comprising 100.8 Mt Measured and Indicated plus 256.3 Mt Inferred. A single infill-style drill hole at approximately resource grade does not alter the perceived scale, grade, or mine life of the deposit. Instead, it supports the block model and the thesis regarding the conversion of Inferred resources to Indicated.
Tintina’s stock has seen significant volatility, rising from approximately C$0.62 prior to the June 2 strategic financing announcement to a C$3.50 close on June 30, before falling to C$1.88. The current price reflects project advancement, partner credibility, and copper leverage rather than pricing in the repetition of a single drill hole.
The recent release serves as a positive confirmation from a large drill program, with a resource update targeted for the second half of 2027. Little immediate share-price impact is expected from this hole alone, as copper price, permitting, financing, and subsequent step-out results remain the larger drivers.
Tintina Mines Ltd. is advancing its wholly owned Dos Amigos project, formerly known as the Domeyko Sulfuros project, in the Atacama Region of Chile through Andean Belt Resources SpA. The company, which is listed on the TSXV, holds an existing preliminary economic assessment and mineral resource estimate for the site. The resource base includes 100.8 million tonnes of measured and indicated resources grading 0.35% copper and 0.28 grams per tonne gold, alongside 256.3 million tonnes of inferred resources grading 0.34% copper and 0.24 grams per tonne gold.
The preliminary economic assessment outlines a 25-to-26-year open-pit operation utilizing a 35,000-tonne-per-day flotation plant. Under the scenario modeled at US$4.30 per pound of copper and US$2,500 per ounce of gold, the project is projected to produce approximately 37,000 tonnes of copper and 57,000 ounces of gold annually. This scenario yields a pre-tax net present value of US$560 million and an after-tax net present value of US$328 million.
Tintina is proceeding directly to a feasibility study, with a final investment decision targeted for 2030. The project requires initial capital of US$1.283 billion, including contingency, and sustaining capital of US$905 million.
In 2026, Tintina closed a C$91 million subscription receipt financing at C$0.68 per share. The transaction consolidated 100% ownership of Andean Belt Resources and brought in Sumitomo and Gignac as anchor investors, along with Franco-Nevada. Following the exchange, the company reported 283,518,365 shares outstanding, with approximately 91.3 million warrants exercisable at C$0.80 and C$1.00.
Prior-period context not disclosed in today’s release indicates that Tintina’s Q2 2026 as-reported financials showed C$3.65 million in cash, a going-concern warning, and an accumulated deficit before the C$91 million financing closed. The financing materially changes the near-term liquidity picture, although future development capital requirements remain significant.