Silvercorp Announces Project Update for El Domo
Silvercorp’s El Domo project faces a five percent capital expenditure increase, delaying first production to November 2027.
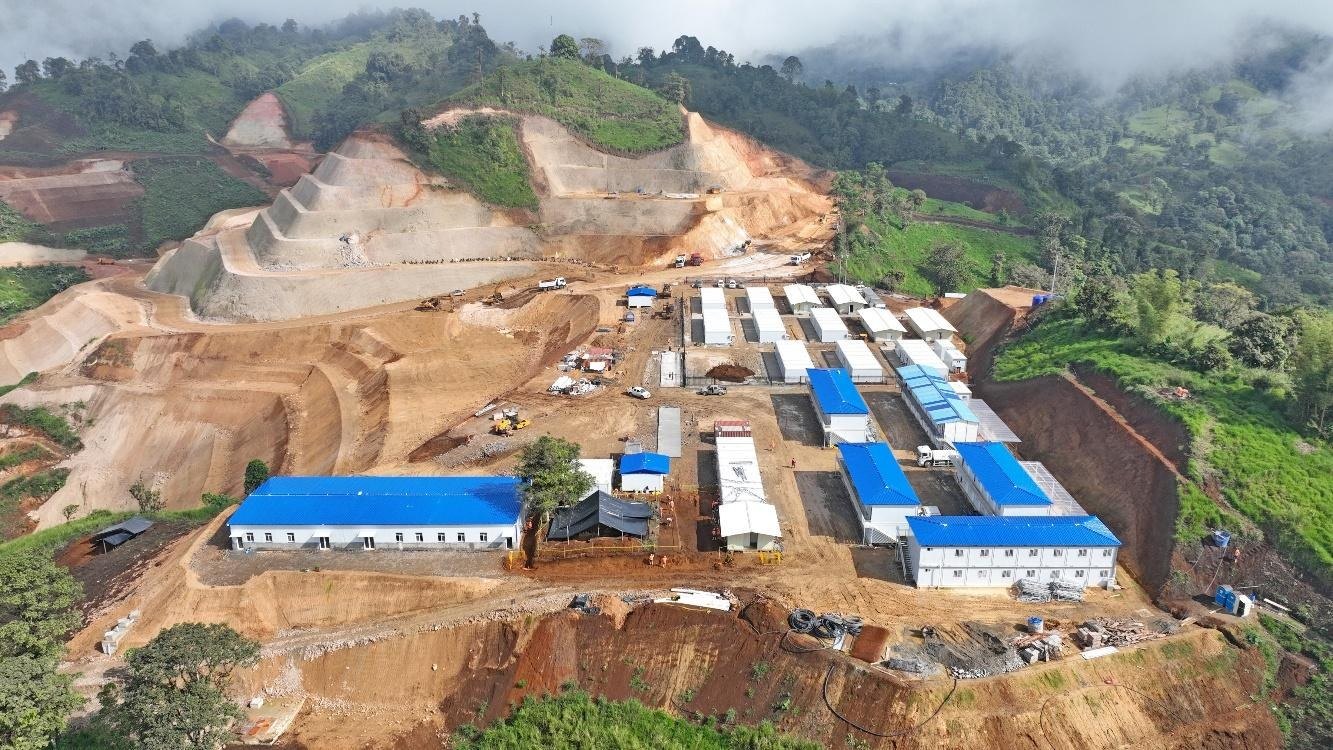
Silvercorp Metals Inc. (SVM) has revised the capital cost and construction timeline for its El Domo project in Ecuador, where the company holds a 75% ownership and operating interest while Salazar retains a 25% carried interest. The update, which does not constitute an earnings release, raises the total construction budget to $298.2 million, an increase of $14.6 million, or 5.1%, from the $283.6 million estimate provided on February 4, 2026. This figure also represents a $50.2 million, or 20.2%, increase over the $248 million estimate in the 2021 Feasibility Study.
The delay in project execution has pushed the first production date to November 1, 2027, a four-month shift from the July 1, 2027 date reaffirmed in the Q1 FY2027 MD&A on August 10, 2026. Management attributed the delay to extended rainfall at the site caused by Super El Nino.
The $14.6 million net cost increase results from gross increases of $24.4 million offset by $9.8 million in savings. Diesel fuel costs rose by $8.3 million, comprising $3.6 million in Package #1 and $4.7 million in Package #2, following Ecuador’s removal of diesel subsidies. The price increased from under $3.00 per gallon in December 2024 to $5.64 per gallon in October 2026, a rise of approximately $2.70 per gallon, or 90%. Water management infrastructure costs increased by $4.7 million, including $3.5 million for design and construction reinforcement and $1.2 million for site cleaning added to Package #1 TSF. Processing plant construction costs rose by $3.7 million based on the actual bill of quantities for Package #3, while site power supply equipment costs increased by $2.4 million for cables and distribution based on detailed engineering.
Additional new items added approximately $2.0 million for two cofferdams, drainage pipes under the TSF starter dam, and cemented roadside ditches, as well as $3.3 million for two reactive power compensators (SVG) and related power items. Savings were realized through $1.8 million from reusing site rock for haul roads, $1.5 million from eliminating the West Non-contact Water Channel, $0.7 million from shrinking the permanent camp, and $2.7 million from contingency reduction.
As of September 30, 2026, $84.6 million, or 28.4% of the budget, has been spent, leaving $213.6 million to be expended over the next 13 months. In Package #1, $27.1 million of the $57.2 million budget has been spent, with the TSF and Non-contact Water Channel identified as laggards. Package #2 has seen $2.4 million spent of its $40.0 million budget; the mining contract was awarded to China Railway 19th Bureau Group (CRCC 19) on a unit-cost basis, valued at $35 million.
In Package #3, $14.1 million of the $62.2 million budget has been spent. Progress includes 92% completion for fine ore bin foundations, 45% for grinding and flotation, 21% for the thickener, 86% for the dewatering plant, 75% for the warehouse, 35% for the oil depot, 78% for the lab, and 46% for the office. Packages #4 and #5 have seen $13.2 million spent of the $49.3 million budget. The external powerline remains a significant challenge due to continuous delays requiring additional reviews and approvals from CNEL, with only the site substation currently under construction. Ten 17 MW generator sets have been manufactured and are ready to ship as an independent power supply.
Management did not include a quote from the CEO or President in the release and chose not to restate the project’s NPV, IRR, or mine life alongside the higher capital expenditure and revised timeline.
Silvercorp Metals Inc. (SVM) reported a $14.6 million pre-tax cost overrun and a four-month schedule deferral for its El Domo project. Against the project’s $571 million after-tax net present value at an 8% discount rate, as outlined in the 2026 technical report, the financial impact is valued at well under $30 million of net asset value, or less than $0.14 per share. This figure represents under 0.6% of the company’s $2.46 billion market capitalization. As Silvercorp holds a 75% attributable interest in El Domo, the actual financial hit to the company is smaller still.
The more significant development is the recurring pattern of cost and schedule resets. This marks the second consecutive adjustment for the project, following a date restated in an MD&A eleven weeks prior. The company did not revise this timeline when publishing its Q2 operational results on October 19, even though that release had already disclosed 620 mm of rainfall—489% above average—77 lost work days, and water-management issues at the tailings storage facility. The formal four-month delay and the additional $14.6 million in costs were withheld until the current announcement.
A critical unquantified risk involves the power supply infrastructure. CNEL approvals for the powerline are described as "continuously delayed," with only the substation construction having started. The fallback option relies on 170 MW of diesel generation at a cost of $5.64 per gallon. If El Domo enters production using generators, the project’s operating cost base and net present value will deteriorate in a manner not quantified in the release, presenting a larger latent risk than the immediate cost overrun.
Market context shows the shares closed at $11.14 on the release date, down 34% from $17.00 on the prior earnings release date of August 10, 2026, and 48% from the May 13 high of $21.52. The market has already de-rated the stock significantly due to the China safety suspension, the Q2 production miss, and softer silver prices. This news extends a negative run rather than starting one, but it removes the "El Domo on time" support that underpinned the growth story.
Silvercorp Metals Inc. (SVM) is a Canadian-domiciled producer of silver, gold, lead and zinc with a significant operational weight in China. The company is listed on the TSX and NYSE American and has proposed a triple primary listing in Hong Kong.
Its operating assets include the Ying Mining District in Henan province, where seven mines feed two mills at a combined capacity of approximately 4,000 tonnes per day. The company is targeting the No. 3 mill, with a capacity of 3,000 tpd, for completion in Q1 FY2028, while the retirement of the No. 1 mill will result in a net reduction of 6,500 tpd. The GC Mine in Guangdong province is also an operating asset.
Construction projects include El Domo in Ecuador, a copper-gold-silver deposit; Kuanping, a satellite silver mine feeding the Ying operation; and Tulkubash Phase 1 in Kyrgyzstan, an open-pit heap leach project.
Development and exploration activities are underway at Kyzyltash Phase 2 in Kyrgyzstan, a sulfide project with a preliminary economic assessment expected in 2027 and a feasibility study targeted for 2028. The Condor project in Ecuador is in the permitting phase, and the BYP project is located in China.
The company holds equity stakes of approximately 28% in New Pacific Metals (Silver Sand, Bolivia) and approximately 27.4% in Tincorp Metals via its subsidiary Adventus.