Fredonia Confirms Continuity of Gold/Silver Mineralization and the Potential Expansion of the Conceptual EDM Mine Plan at Herradura Hill
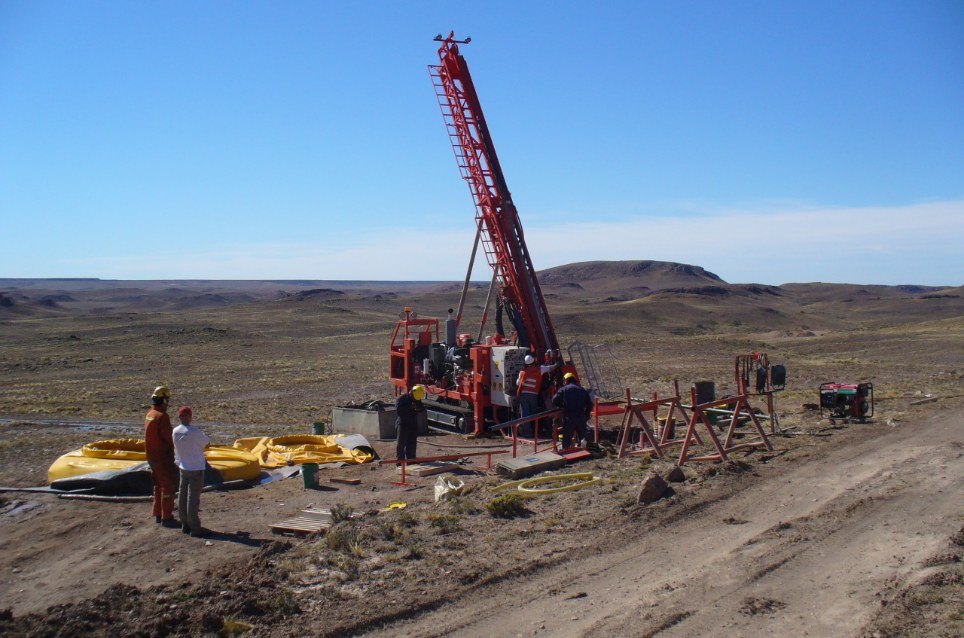
Fredonia Mining Inc. (FRED) reported assay results from three holes in the Herradura Hill sector of its El Dorado–Monserrat (EDM) gold-silver project in Santa Cruz, Argentina. The company clarified that the reported intervals represent downhole lengths and are not true widths.
HDDH062, located at the western pit boundary with a dip of 45° and an end of hole (EOH) depth of 245 m, intersected 24.7 m at 1.3 g/t Au, 15 g/t Ag, and 1.6 g/t AuEq from 120.3 m. This interval included 3.5 m at 5.1 g/t Au, 26 g/t Ag, and 5.5 g/t AuEq. It was followed by 35.0 m at 0.55 g/t Au, 16 g/t Ag, and 0.8 g/t AuEq from 153.5 m. The two intervals were separated by 8.5 m of lower-grade material.
HDDH061, drilled more than 200 m west of the pit with a dip of 50° and an EOH of 140 m, returned 10.0 m at 0.6 g/t Au, 7 g/t Ag, and 0.75 g/t AuEq from 51 m, including 1.5 m at 3.1 g/t Au, 9 g/t Ag, and 3.3 g/t AuEq. Additional intersections included 4.0 m at 0.41 g/t AuEq from 118 m, and 4.0 m at 0.44 g/t Au, 10 g/t Ag, and 0.6 g/t AuEq from 136 m. The company noted that continuity with the known deposit remains to be established.
HDDH063, located in the central-eastern portion inside the block model with a dip of 60° and an EOH of 335 m, intersected 3.0 m at 0.77 g/t AuEq from 44 m; 5.0 m at 1.4 g/t Au, 4 g/t Ag, and 1.46 g/t AuEq from 97 m, including 1.4 m at 4.7 g/t AuEq; and 7.7 m at 0.86 g/t Au, 7 g/t Ag, and 0.99 g/t AuEq from 107.4 m.
The results suggest potential to extend mineralization at depth and to the west of the current pit design. The data serves as a restatement of the August 31, 2026 Preliminary Economic Assessment (PEA), which outlined a 10 Mtpa ROM operation producing 146 koz AuEq/yr over 17 years, resulting in a US$1.5B NPV10 and 65% IRR. The new holes are not included in the current resource estimate. Additionally, the company disclosed that the July 14 hole (HDDH051) was calculated on a different gold-equivalent basis and would now grade approximately 1.33 g/t AuEq instead of 1.29 g/t.
Fredonia Mining Inc. (FRED) released drill results from its Herradura project that fall short of the property’s historical best intercept, though the company maintains it remains a post-PEA study-stage developer. The project holds an estimated 200.4 million tonnes at 0.68 g/t and 0.46 g/t AuEq, totaling 3.85 million ounces of AuEq. The company stated that the new holes postdate the resource estimate and the Preliminary Economic Assessment (PEA), meaning no new tonnes were added and the release did not alter tonnage, grade, recovery assumptions, capital expenditure, or study economics.
The best previous result at Herradura came from hole HDDH051, reported on July 14, 2026. That intercept returned 70.75 meters at 1.29 g/t AuEq, which equates to approximately 1.33 g/t on the new basis, or roughly 94 gram-meters. It also included a near-surface interval of 10.5 meters at 2.78 g/t AuEq, enriched in silver at 120 g/t Ag. Today’s best result recorded 67.5 gram-meters across two stacked zones, or approximately 1.13 g/t over a composite span of about 60 meters. This result featured higher grade—1.6 g/t versus 1.33 g/t—but over a significantly shorter interval of 24.7 meters compared to the 70.75 meters in HDDH051.
HDDH051 was released when the stock traded at $0.43, up from $0.38 the prior day. The shares then traded between $0.38 and $0.47 for six weeks. A more durable price movement followed the Aug. 31 PEA release, which saw the stock rise from $0.71 to $0.85, peaking at $0.90 on Sept. 1. Since that peak, the stock has fallen 49% to $0.46 and currently trades 29% below the $0.65 price of the Sept. 23 $11.5 million bought deal. The market appears to be evaluating the project based on its ability to justify a US$346 million capital expenditure and a 0.68 g/t heap-leach operation in Argentina, rather than expecting a repeat of the HDDH051 intercept.
At a market capitalization of approximately C$38 million and with roughly C$12–14 million in pro-forma cash, the market is heavily discounting the study’s US$1.5 billion NPV10. This discount reflects risks including the Argentine jurisdiction, the US$346 million capex against a micro-cap balance sheet, 44.1 million tonnes of Inferred material in the plant feed, and heap-leach recovery risk. The new drill holes confirm pit-wall continuity and hint at depth extension, providing support for the resource that underpins the 2027 Preliminary Feasibility Study (PFS), but they do not close the valuation gap.
Fredonia Mining Inc. (TSXV: FRED; OTC: FREDF) holds approximately 64,000 hectares of gold-silver licences in the Deseado Massif of Santa Cruz, Argentina. The company’s portfolio includes the flagship El Dorado–Monserrat (EDM) project covering roughly 33,500 hectares, the El Aguila property at approximately 9,100 hectares, and the Hornia property at roughly 21,500 hectares. Additionally, Fredonia acquired the 4,913-hectare Judite property on April 30, 2026, and the approximately 11,754-hectare Pan American Silver property package for US$225,000 payable in three instalments, subject to a 1.5% net smelter return (NSR) plus a 0.3% NSR capped at US$800,000. The EDM ground is located approximately 15 km from AngloGold Ashanti’s Cerro Vanguardia operation.
The company’s mineral resource estimate, effective August 17, 2026, reports 126.45 million tonnes of measured and indicated resources at 0.47 g/t Au, 12.66 g/t Ag, and 0.68 g/t AuEq for 2.76 million ounces of AuEq, using a cut-off of 0.10 g/t Au. Inferred resources total 73.89 million tonnes at 0.31 g/t Au, 8.98 g/t Ag, and 0.46 g/t AuEq for 1.09 million ounces of AuEq. By deposit, the Main Veins contain 88.6 million tonnes of measured and indicated resources at 0.78 g/t AuEq (2.23 million ounces) and 64.1 million tonnes of inferred resources at 0.48 g/t AuEq. La Herradura comprises 33.6 million tonnes of measured and indicated resources at 0.44 g/t AuEq (0.47 million ounces) and 7.0 million tonnes of inferred resources at 0.29 g/t AuEq. Monserrat West holds 4.3 million tonnes at 0.37 g/t AuEq and 2.9 million tonnes at 0.40 g/t AuEq.
A preliminary economic assessment (PEA) dated August 31, 2026, outlines a 10 million tonnes per annum operation with a life of more than 17 years. The plan projects an average production of 146,000 ounces of AuEq per year, rising to approximately 183,000 ounces in the first five years. The project yields a post-tax NPV10 of US$1.5 billion and an internal rate of return (IRR) of 65%. Initial capital expenditure is estimated at US$346 million, broken down into US$143 million for the fleet, US$91 million for plant and infrastructure, and US$112 million for pre-production. Operating costs are projected at C1 of US$1,630 per ounce and AISC of US$1,720 per ounce, with a strip ratio of 1.7:1, 5% dilution, and 97% mine recovery. Processing utilizes a dual-route system: a 20,000 tonnes per day crush/agglomerate heap leach circuit achieving 85% Au and 70% Ag recovery, plus an uncrushed ROM pad with 50% Au and 20% Ag recovery. Under the RIGI case scenario, the NPV10 rises to US$1.8 billion with an IRR of 82%.
The mine plan directs 79.67 million tonnes of measured and indicated resources at 0.606 g/t Au, plus 44.10 million tonnes of inferred resources at 0.474 g/t Au, to the plant. An additional 28.59 million tonnes of measured and indicated resources and 18.45 million tonnes of inferred resources are allocated to the ROM pad. Roughly a third of the plant feed consists of inferred material, a practice permitted in a PEA but not in a pre-feasibility study.
Financially, Fredonia reported cash of US$4.11 million and working capital of US$3.50 million as of March 31, 2026. The company recorded a net loss of US$1.15 million for the six months then ended, with an operating cash outflow of US$1.03 million. In February 2026, a placement raised C$7.0 million through the issuance of 17.5 million units at C$0.40, each with a half-warrant exercisable at C$0.56. A bought deal in September 2026 raised C$11.5 million gross, involving 17.69 million shares at C$0.65, including full over-allotment and a 6% commission, with insiders contributing US$325,000. The company withdrew its application to reduce the warrant strike price from US$1.40 to US$0.45, citing the ability to fund at a higher share price. The Q2 2026 MD&A includes an explicit going-concern material uncertainty.
The capital structure comprised 64.7 million shares as of March 31, 2026, expanding to approximately 82.4 million following the September issue. An investor presentation shows 5.9 million options and 20.3 million warrants outstanding, resulting in 91.1 million fully diluted shares prior to the September issuance, or approximately 108 million pro forma. This represents a approximately 30% dilution overhang on top of approximately 35% share-count growth in the last twelve months.
Management includes President and CEO Estanislao Auriemma and Chairman Ali Mahdavi. The team features principal geologist Martin Auriemma, who has over 24 years of experience in Argentina, strategic adviser Gustavo Gomes, formerly of Las Bambas, Ambatovy, Rio Tinto, and BHP, and qualified person Mario Alfaro, with 59 years in exploration. The