FREDONIA ANNOUNCES C$10 MILLION BOUGHT DEAL PRIVATE PLACEMENT
Fredonia’s EDM preliminary economic assessment yields a $1.5 billion net present value, while a C$10 million financing round highlights ongoing dilution risks.
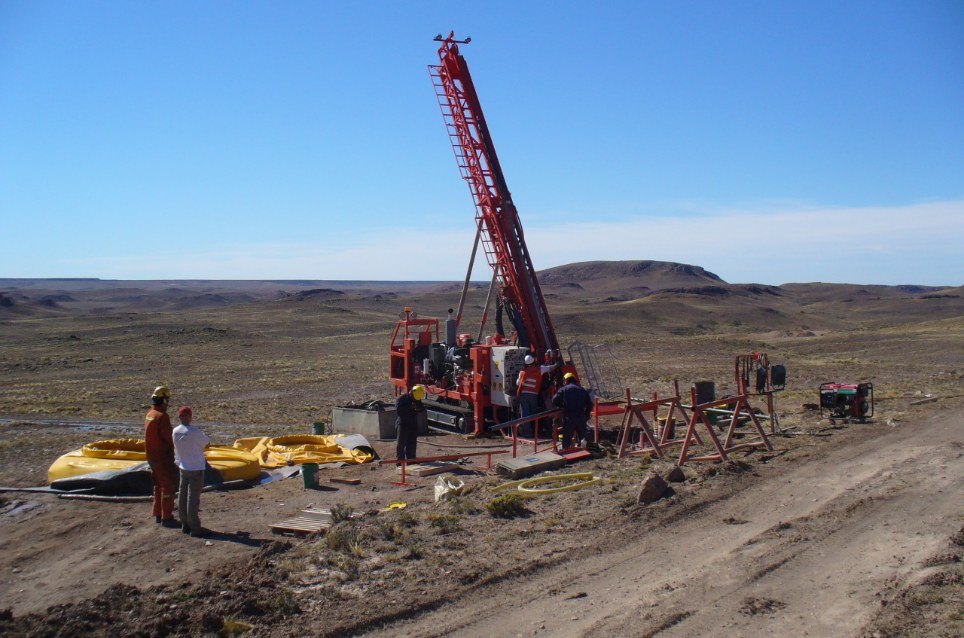
Fredonia Mining Inc. announced a C$10 million bought deal private placement of common shares at C$0.65 per share. The offering includes an over-allotment option allowing the underwriters to purchase up to an additional C$1.5 million worth of shares. Net proceeds will be directed toward the exploration and advancement of the El Dorado Monserrat (EDM) Project in Argentina, alongside general corporate and working capital needs. Closing is expected on or about September 23, 2026.
This financing directly follows the August 31, 2026 Preliminary Economic Assessment (PEA), which outlined a 17+ year mine life, 146,000 oz AuEq/year average production, a $1.5 billion post-tax NPV10, and a 65% IRR.
Fredonia Mining Inc. (FRED) announced a financing that the company’s March 2026 MD&A had explicitly flagged as necessary due to a going concern material uncertainty, noting that continued operations depend on obtaining required funding. The February 2026 raise was projected to cover 12-18 months, making a follow-on raise in September highly anticipated.
The issue price of C$0.65 represents a discount to the recent trading range of $0.70-$0.90. While standard for bought deals, this discount typically induces short-term selling pressure and caps immediate upside.
The capital raise aligns precisely with the company's stated roadmap to advance from a Preliminary Economic Assessment (PEA) to a Pre-Feasibility Study (PFS) and permitting. The move does not alter the fundamental project thesis but confirms management's commitment to execution. There was no material surprise or deviation from prior guidance, as the market had already priced in the necessity of follow-on funding post-PEA.
Fredonia Mining Inc. (FRED) is a junior explorer focused on the El Dorado Monserrat (EDM) gold-silver project in the Deseado Massif, Santa Cruz Province, Argentina. The project is strategically located approximately 15 km from AngloGold Ashanti's Cerro Vanguardia mine.
The company’s land position covers approximately 33,500 hectares, expanded through strategic acquisitions including assets from Pan American Silver Corp. and the Judite property. The project is currently in the advanced exploration stage, with a Preliminary Economic Assessment (PEA) completed in August 2026.
The PEA highlights include an average production of 146,000 oz AuEq per year, a $1.5 billion NPV10, a 65% internal rate of return (IRR), and $1,630/oz all-in sustaining costs (AISC). Management includes CEO Estanislao Auriemma and Strategic Advisor Gus Gomes, who has prior experience at Las Bambas, Ambatovy, and Rio Tinto.