Lithium Argentina Announces Repurchase of $200 Million of its 2027 Convertible Notes
Lithium Argentina AG cut 2027 notes to ~$59m, largely clearing the going-concern overhang.
Lithium Argentina AG (LAR) repurchased approximately $200 million in aggregate principal of its convertible senior notes due January 2027 through privately negotiated transactions with a limited number of qualified institutional buyers. The company paid a cash cost of roughly $198 million, plus accrued interest, representing a discount of approximately 99 cents on the dollar to par value.
The repurchase was funded using cash on hand, which included proceeds from the $180 million strategic investment by Ganfeng that closed on September 15, 2026. Following the transaction, approximately $59 million in principal of the 2027 Notes remains outstanding. Lithium Argentina stated it intends to repay the remaining balance at or before the January 15, 2027 maturity date using cash on hand. The company reported that cash on hand exceeded $100 million after the repurchases.
Management indicated that no other corporate-level debt matures until 2032. CEO framing described the move as "the next step in deleveraging and strengthening our balance sheet." This transaction executes a plan previously disclosed on August 24 and September 15, 2026, which outlined using Ganfeng’s $180 million note plus cash on hand to repay the 2027 convertible notes. While earlier releases stated proceeds would "fully repay" the $259 million in notes, this repurchase leaves approximately $59 million outstanding, though the company maintains its intent to repay the balance.
Lithium Argentina AG (LAR) confirmed the execution of a transaction to retire its 2027 Notes using proceeds from a $180 million convertible note and cash from Ganfeng, as pre-announced on August 24 and September 15. The company repurchased the debt at a slight discount, resulting in a small, unquantified gain on extinguishment.
The transaction significantly alters the company’s credit profile. In the Q2 2026 MD&A, LAR flagged a material uncertainty regarding its going-concern status, citing reliance on Cauchari-Olaroz distributions to service $258.8 million of converts maturing in January 2027. By reducing that obligation to approximately $59 million and confirming a path to clear it with more than $100 million in cash, the company has materially reduced its near-term refinancing and solvency overhang.
The operating story remains unchanged, with no impact on production, costs, resources, or project economics. The involvement of Ganfeng was previously announced, and the transaction does not constitute a game-changing event such as a first-time strategic investment, M&A activity, or a change in company size.
Several nuances accompany the deal. The repurchase leaves a residual $59 million in debt, with the company again leaning on cash on hand and future joint venture distributions to fund operations. The repurchase was conducted with holders located outside Canada, a structural detail noted for completeness. Additionally, repurchasing debt at par while the equity trades near 52-week lows suggests the convertible was priced off the credit rather than capturing a significant discount.
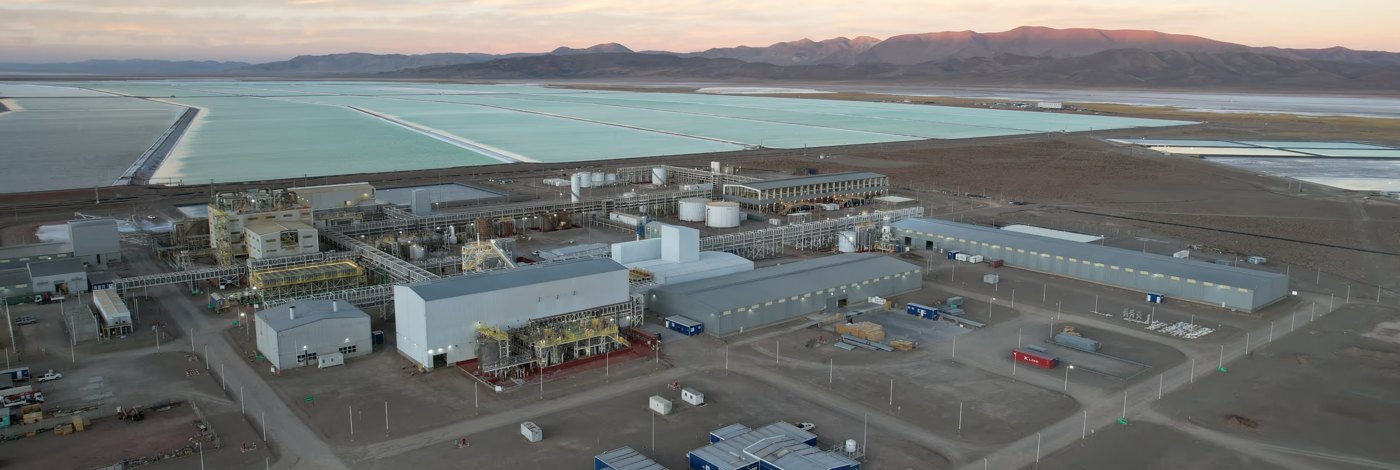
Lithium Argentina AG (TSX/NYSE: LAR), a company domiciled in Zug, Switzerland, and operating in Argentina, manages its flagship Cauchari-Olaroz asset in Jujuy province. As Argentina’s largest lithium brine operation, the site features a Stage 1 nameplate capacity of approximately 40,000 tonnes per annum (tpa) of lithium carbonate. The project is owned by Lithium Argentina (44.8%), Ganfeng (46.7%), and JEMSE, the Jujuy government (8.5%). First half 2026 production ran at approximately 95% of design capacity, with full-year 2026 guidance set between 35,000 and 40,000 tonnes.
The company is pursuing a Stage 2 expansion, approved under the RIGI framework in May 2026, which targets an additional 45,000 tpa of lithium carbonate equivalent (LCE) to bring total capacity to approximately 85,000 tpa. A scoping study released on September 30, 2026, calculated an after-tax NPV8% of $3.1 billion and an internal rate of return (IRR) of 28.5%, based on a capital cost of approximately $1.0 billion and operating expenditure of approximately $5,006/t at an $18,000/t price. Additionally, an accelerated initial 10,000 tpa adsorption-DLE phase, which is not included in the study’s economics, targets first production in 2028.
In Salta province, the Pozuelos-Pastos Grandes (PPG) growth project has been consolidated into a joint venture with Ganfeng (67%) and Lithium Argentina (33%). The project targets 150,000 tpa LCE over three phases. A scoping study in November 2025 indicated an after-tax NPV8% of $8.1 billion and an IRR of 33% at an $18,000/t price, with RIGI approval targeted for the end of 2026.
Regarding resources, the Cauchari-Olaroz measured and indicated resources rose 42% to 28.1 million tonnes LCE at a grade of 562 mg/L, effective January 1, 2026. The PPG reserves stand at 1.4 million tonnes LCE, supporting a 35-year Stage 1 life. The long-term price assumption for these calculations is $18,000/t.