SSR Mining Announces the Acquisition of Roxmore Resources
SSR acquires the Converse deposit adjacent to Marigold in a $464 million all-cash transaction.
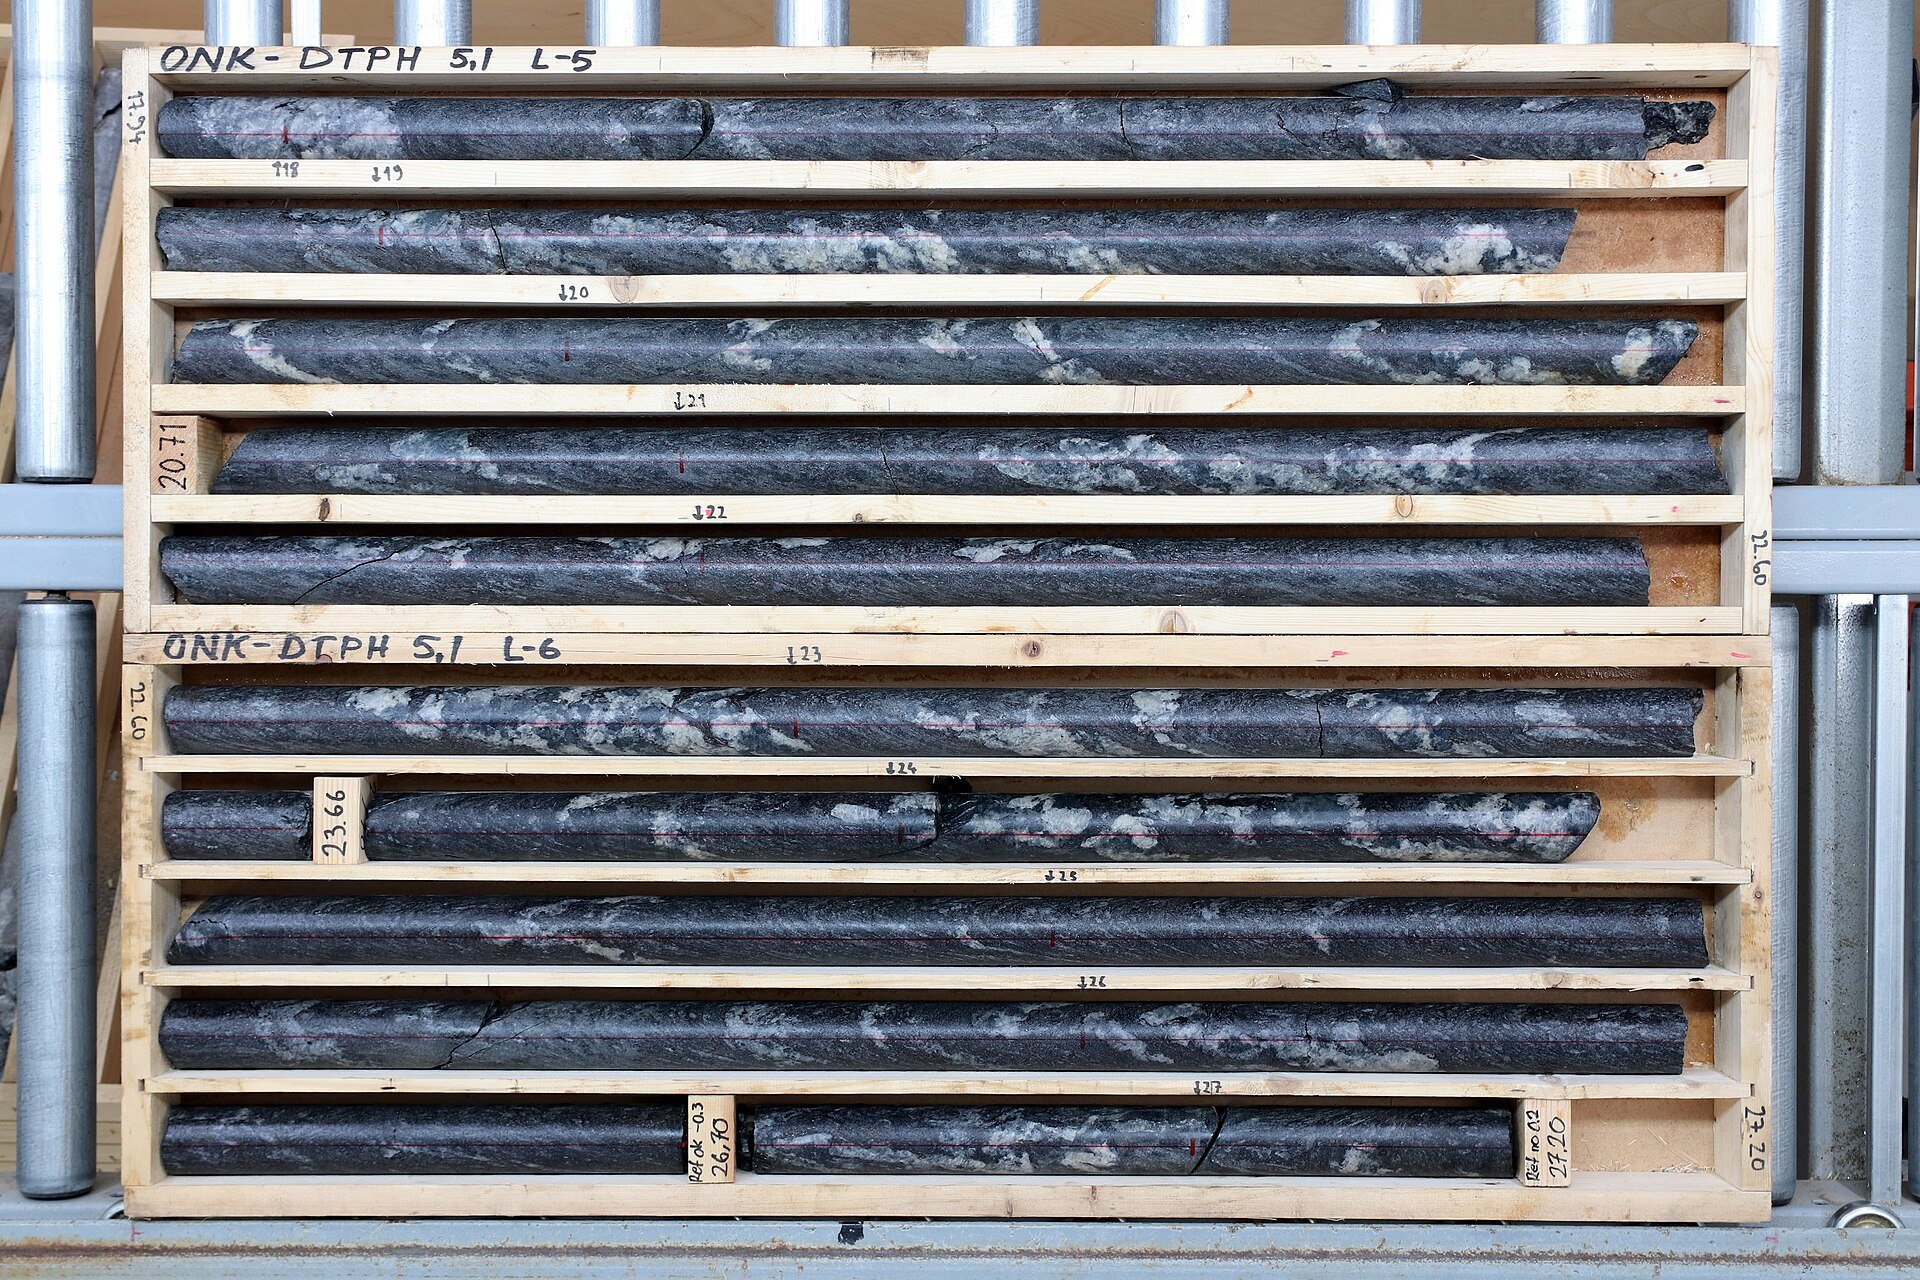
SSR Mining Inc. has entered a definitive agreement to acquire all issued and outstanding shares of Roxmore Resources Inc. through a court-approved plan of arrangement under the Business Corporations Act (British Columbia). Under the terms of the deal, Roxmore shareholders will receive C$6.75 per common share in cash, along with shares in a newly created SpinCo that will hold Roxmore’s Rattlesnake Hills, Shabu River, and Newton assets. The SpinCo will be capitalized with US$10 million in cash, with ownership split 85.01% among former Roxmore shareholders and 14.99% among SSR Mining, and will be led by key Roxmore management.
The transaction carries a fully diluted in-the-money equity value of approximately $464 million, excluding the SpinCo, with an enterprise value of approximately $392 million. The cash component represents a 27% premium to Roxmore’s closing price on October 9, 2026, and a 47% premium to its 20-day volume-weighted average price. SSR Mining will fund the cash consideration from its existing balance sheet, and no SSR shares are being issued.
The primary asset in the acquisition is the Converse Gold Project, located 6 kilometers west of SSR’s Marigold Complex on the Battle Mountain-Eureka Trend in Nevada. Converse hosts two gold-rich skarn deposits, North Redline and South Redline, which are mined via conventional open pit methods and processed through a proposed three-stage crush heap leach operation. Roxmore’s 2026 Converse resource estimate includes 103 million tonnes of Indicated resources grading 0.65 grams per tonne of gold for 2.2 million ounces, and 218 million tonnes of Inferred resources grading 0.43 grams per tonne of gold for 3.0 million ounces, calculated using a $3,000 per ounce pit shell.
SSR Mining intends to apply pit shell assumptions of $2,200 per ounce for Mineral Reserves and $2,500 per ounce for Mineral Resources, consistent with those used for Marigold, which are lower than the assumptions used in Roxmore’s preliminary economic assessment. SSR envisions Converse adding approximately 150,000 to 170,000 ounces of annual gold production over a mine life exceeding 10 years, with initial production targeted for 2033. Initial capital for the project is estimated at $800 million to $900 million, with no material development capital expected until the early 2030s.
SSR estimates undiscounted life-of-mine synergies of at least $200 million compared to a stand-alone Converse development, driven by savings in duplicate general and administrative costs, procurement, and supply chain efficiencies. Combined production from Marigold, CC&V, and Converse could reach 350,000 to 400,000 ounces of annual US gold through the 2030s, with peak US production exceeding 450,000 ounces once Converse is in production.
Closing is expected in the fourth quarter of 2026, subject to approval by at least 66 2/3% of Roxmore securityholders, court approval, and customary conditions. A C$18 million break fee is payable to SSR Mining in certain circumstances. The release contains no update to 2026 production guidance, AISC guidance, or current operating results.
SSR Mining Inc. (SSRM) announced an all-cash acquisition of the Converse project, a move funded entirely from existing liquidity that avoids immediate equity dilution. The transaction carries an equity value of approximately $464 million, representing about 4.4% of SSR’s calculated market capitalization of roughly $10.45 billion, while the $392 million enterprise value accounts for approximately 3.8% of that market cap. The cash outlay constitutes about 26% of the $1.783 billion cash balance held as of Q2 2026.
The deal adds a multi-million ounce gold resource immediately adjacent to the Marigold operation, with potential production of 150,000 to 170,000 ounces per year starting in 2033. SSR states the transaction is accretive to net asset value and gold Mineral Resources, with an internal rate of return exceeding its internal hurdle rate, though no specific IRR, net present value, or standalone Converse technical report summary under SSR assumptions was provided. Initial capital expenditures are estimated between $800 million and $900 million, with initial production targeted for 2033, meaning there is no near-term cash flow impact.
The Converse asset consists of Indicated and Inferred Mineral Resources rather than Mineral Reserves. The 3.0 million ounce Inferred component is considered speculative and requires further drilling, studies, permitting, and conversion. Simple resource-cost calculations based on the $464 million equity value place the cost at approximately $89 per ounce against the 5.2 million ounce total Converse resource, or about $211 per ounce using only the 2.2 million ounce Indicated resource. On an enterprise value basis, the cost is approximately $75 per ounce for the total resource and about $178 per ounce for the Indicated resource. These figures are derived metrics rather than company-reported valuation data.
SSR Mining Inc., a Denver, Colorado-based gold and silver mining company listed on the Nasdaq and TSX under the ticker SSRM, describes itself as the third-largest gold producer in the United States. The company’s operating assets include the Marigold mine in Nevada, the Cripple Creek & Victor mine in Colorado, the Seabee mine in Saskatchewan, and the Puna project in Jujuy, Argentina.
In recent portfolio changes, SSR Mining sold its 80% interest in the Çöpler mine in Türkiye for approximately $1.49 billion in cash in June 2026. Additionally, the company sold its 20% equity interest in Hod Maden in July 2026 in exchange for an uncapped 4.0% NSR royalty.
The company’s development and growth pipeline includes the Buffalo Valley project at Marigold, with first production expected in 2029; the Converse project, with proposed initial production in 2033; the Cortaderas project at Puna; the Porky project at Seabee; the Amisk project in Saskatchewan; and the Dobbin project through a 15% joint venture interest with Phenom Resources.
SSR Mining’s royalty portfolio includes a 4.0% NSR on Hod Maden, a 4.0% NSR on San Luis, a 1.25% NSR on Pitarrilla, a 3.0% NSR on Rowan, and a 4.0% NSR on Sunrise Lake.
For 2026, the company provided company-wide production guidance of 450,000 to 535,000 Gold Equivalent Ounces. The US platform outlook, which includes Marigold, Cripple Creek & Victor, and potentially Converse, is expected to produce 350,000 to 400,000 ounces of annual US gold through the 2030s. Peak US production is projected to exceed 450,000 ounces once Converse enters production.
Rod Antal serves as Executive Chairman and is the senior executive spokesperson for the company. No CEO or CFO change was disclosed in the current release.