NorthWest Intersects 108.7 Metres of 0.70% Copper and 1.69 G/T Gold (2.53% Cueq) at Kwanika in the Western Zone from 352.8 Metres
Northwest’s Western Zone infill drilling exceeded resource grades, highlighting the project’s potential while the pending PEA remains the key catalyst for valuation.
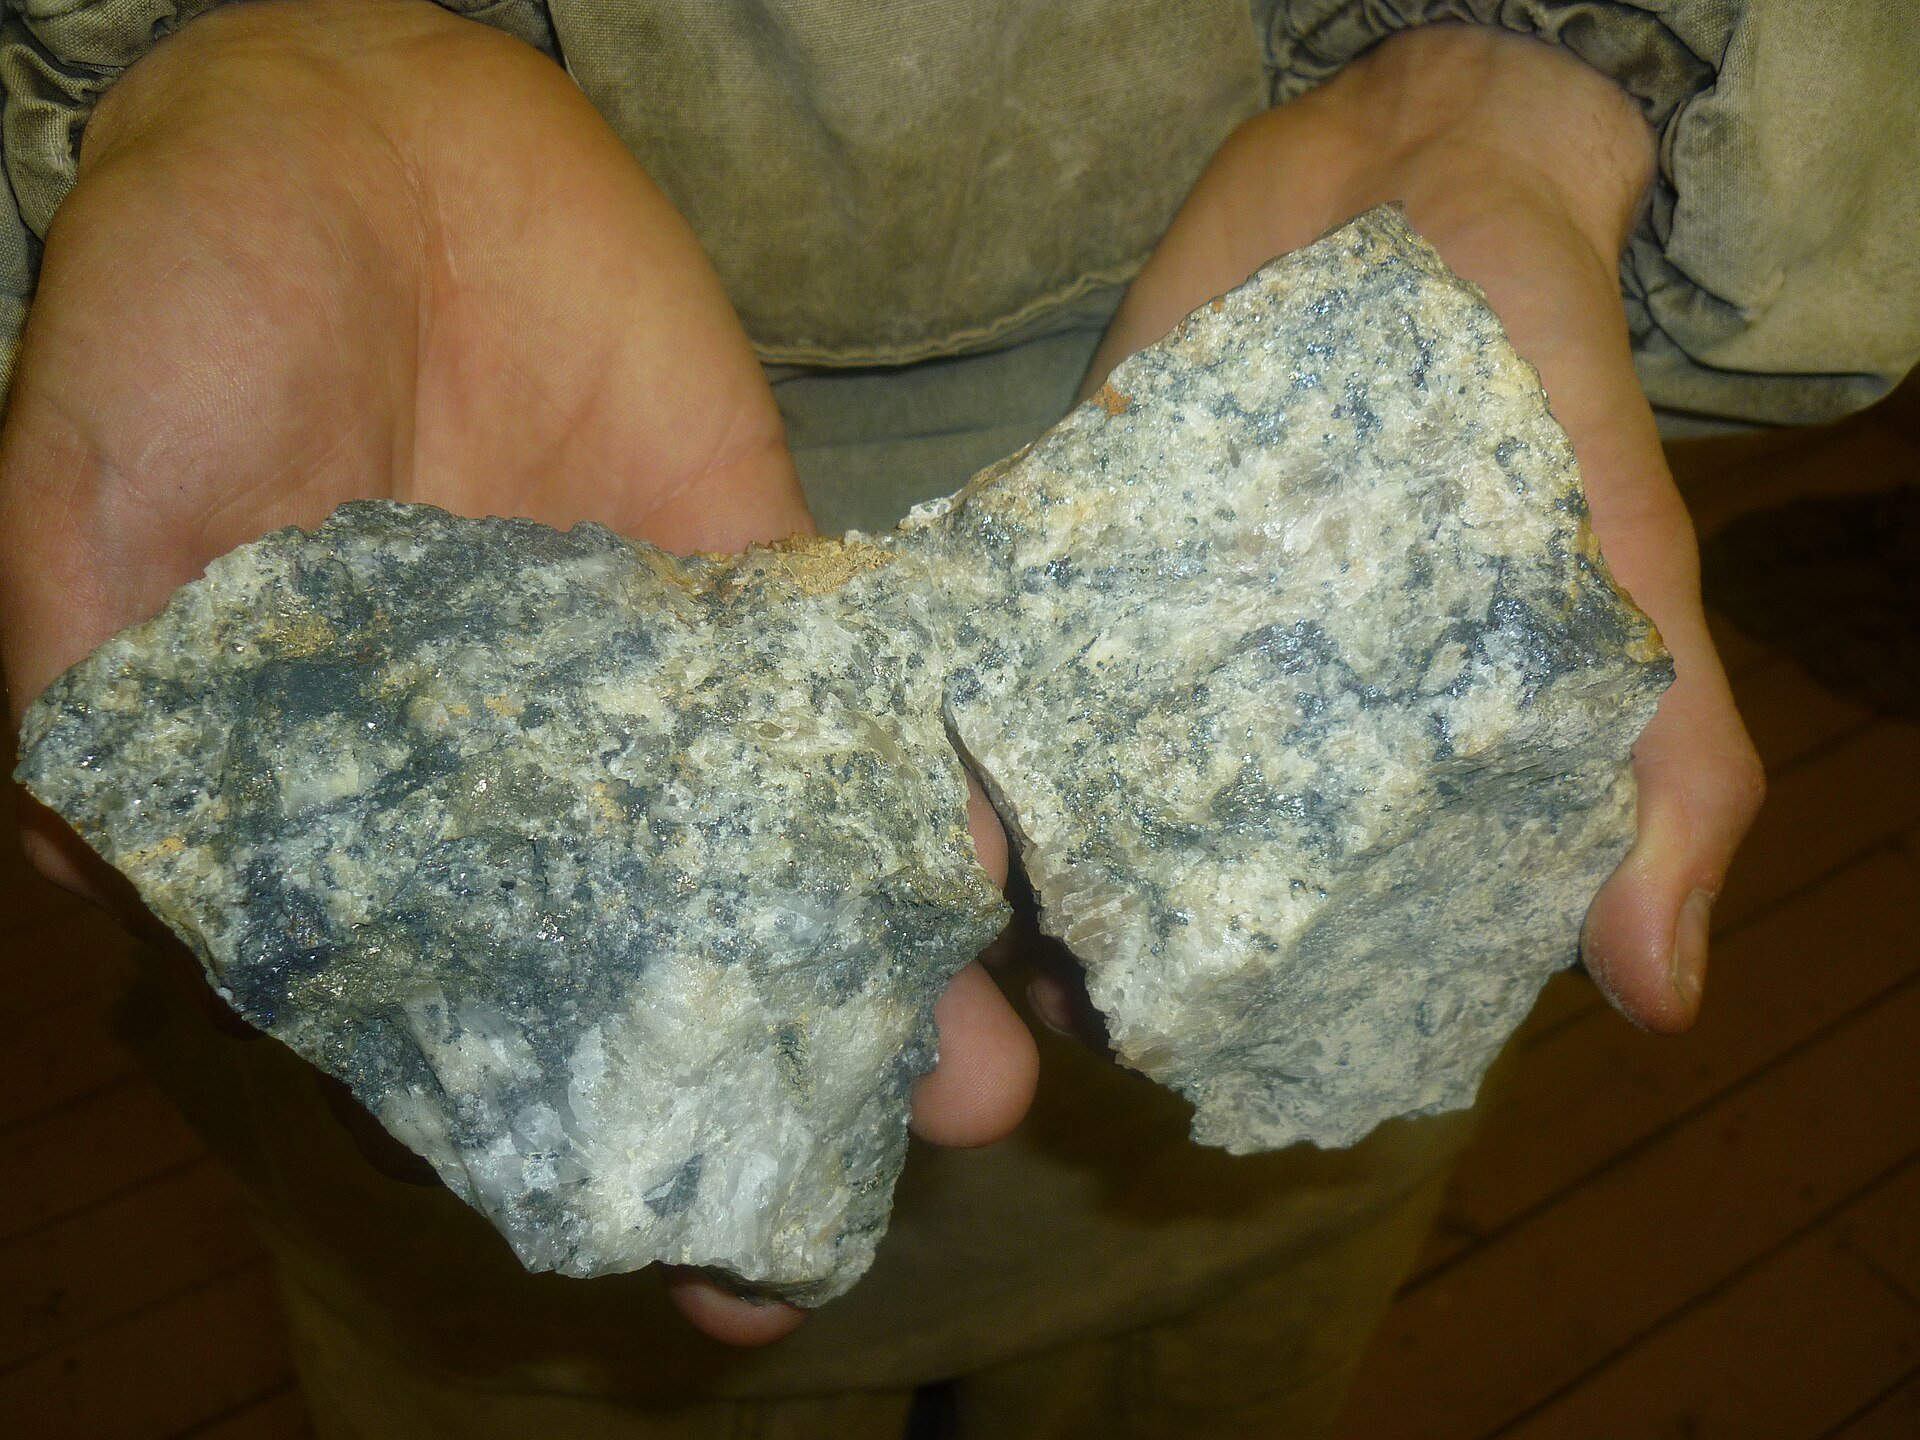
Northwest Copper Corp. (NWST) has released results from four infill drill holes at the eastern end of the Western Zone’s Kwanika Central deposit, located on cross-section 351400E. These results are part of a broader 2026 program comprising approximately 40 holes and 12,000 meters of drilling, with roughly 32 holes still pending release.
The company describes the drilling as infill at approximately 50-meter spacing, intended to convert resources to the Indicated category and support an updated mineral resource estimate for the pending preliminary economic assessment (PEA). Additionally, two short, deeper intersections of "primary copper-gold porphyry" (Unit 16) beneath the Western Zone have been identified as a new exploration target.
Key intercepts from the program include:
- K-26-263: 108.7 m @ 0.70% Cu, 1.69 g/t Au, 1.90 g/t Ag, 0.14 g/t Pd (2.53% CuEq) from 352.8 m; estimated true width 72.7 m. Includes 60.9 m @ 0.87% Cu, 2.39 g/t Au (3.46% CuEq).
- K-26-267: 26.6 m @ 0.27% Cu, 1.70 g/t Au (2.11% CuEq) from 476.0 m, true width 15.2 m; includes a 1.7 m sub-interval @ 0.54% Cu and 15.40 g/t Au (17.08% CuEq).
- K-26-268: 58.6 m @ 0.61% Cu, 0.92 g/t Au (1.61% CuEq) from 343.0 m, true width 33.6 m; plus 10.0 m @ 0.50% Cu, 0.25 g/t Au (0.78% CuEq) at 537 m in "primary porphyry" Unit 16.
- K-26-276: 51.5 m @ 1.15% Cu, 1.47 g/t Au (2.77% CuEq) from 312.5 m, true width 38.3 m; plus 47.0 m @ 1.10% Cu, 1.06 g/t Au (2.28% CuEq) from 381 m.
Northwest Copper Corp. (NWST) released infill and resource-conversion drilling results that confirm grades at or above the current resource estimate over meaningful true widths. The company noted that the deeper Unit 16 primary porphyry zone is too thin and low-grade to be considered material as reported. These results do not represent a discovery or step-out into new ground, nor do they exceed the high-grade data already incorporated into the March 2026 resource update.
The stock traded near $0.45 in December 2025 following earlier high-grade results, but has since round-tripped to the $0.23–$0.28 range by mid-2026. It currently sits at $0.28, near its 52-week low and below the approximate $0.31 book value per share. This pricing suggests the market has not yet embedded expectations for these specific drilling confirmations.
Northwest Copper is an advanced explorer and developer with no revenue, a market capitalization of approximately C$82 million, and roughly C$13 million in net cash. The company completed a fully subscribed capital raise in May 2026. While confirming Indicated resource conversion adds credibility to the Preliminary Economic Assessment (PEA), it does not alter the scale or grade relative to the disclosed resource table.
A more significant corporate development appeared in an October 7 release, in which the CEO acknowledged that the Kwanika-Stardust PEA has taken longer than originally anticipated. The project was previously guided for completion in mid-2026, followed by a timeline of "coming weeks." This delay in catalysts, rather than the drilling results themselves, is currently weighing on the equity.
Northwest Copper Corp. (TSX-V: NWST) is a British Columbia-based company that holds 100% ownership of more than 175,000 hectares of land. The company’s portfolio is royalty and stream-free at its Kwanika-Stardust property, although the Lorraine property carries a 2.25% net smelter return (NSR) with an option to buy it back to 1.25%.
The flagship Kwanika-Stardust project covers over 37,500 hectares. As of February 27, 2026, the Kwanika Central resource comprises an Indicated category of 16.22 million tonnes grading 0.63% copper, 0.74 grams per tonne gold, and 2.0 grams per tonne silver, equivalent to 1.27% copper equivalent, and an Inferred category of 28.97 million tonnes grading 0.48% copper, 0.63 grams per tonne gold, and 1.5 grams per tonne silver, equivalent to 1.05% copper equivalent. This resource is split between an open pit and a sub-level-cave underground component. The Stardust area hosts an additional higher-grade underground resource with an Indicated category of 1.6 million tonnes grading 1.49% copper, 1.63 grams per tonne gold, and 30.1 grams per tonne silver.
The Lorraine property spans over 65,800 hectares and hosts an open-pit resource consisting of an Indicated category of 13.0 million tonnes grading 0.55% copper and 0.16 grams per tonne gold, and an Inferred category of 45.5 million tonnes grading 0.43% copper and 0.10 grams per tonne gold. The East Niv property, covering over 43,000 hectares, is an early-stage porphyry discovery with joint venture, earn-in, and spin-out optionality.
The company’s processing concept involves a 7,000 tonnes per day operation utilizing an optimized pit, a high-grade starter pit, a top-down sub-level cave, XRT ore sorting, and tails leach. Metallurgical results from 2025-26 indicate copper recovery of approximately 89-90%, gold recovery of 94.6-96.3%, and silver recovery of approximately 96%.
The company currently generates no revenue. For the nine months leading to the prior period in Q3-2025, the net loss was C$3.2 million. Cash holdings were C$3.6 million as of September 30, 2025, and were subsequently replenished by a placement in May 2026 that raised approximately C$13.8 million, resulting in net proceeds of approximately C$13 million. The company carries no debt, and its book value per share is approximately C$0.31.