Patagonia Gold Announces Positive Preliminary Economic Assessment for the Calcatreu Gold-Silver Project
Patagonia’s Calcatreu PEA validates a 16-year mine life and strong economics despite critically tight liquidity.
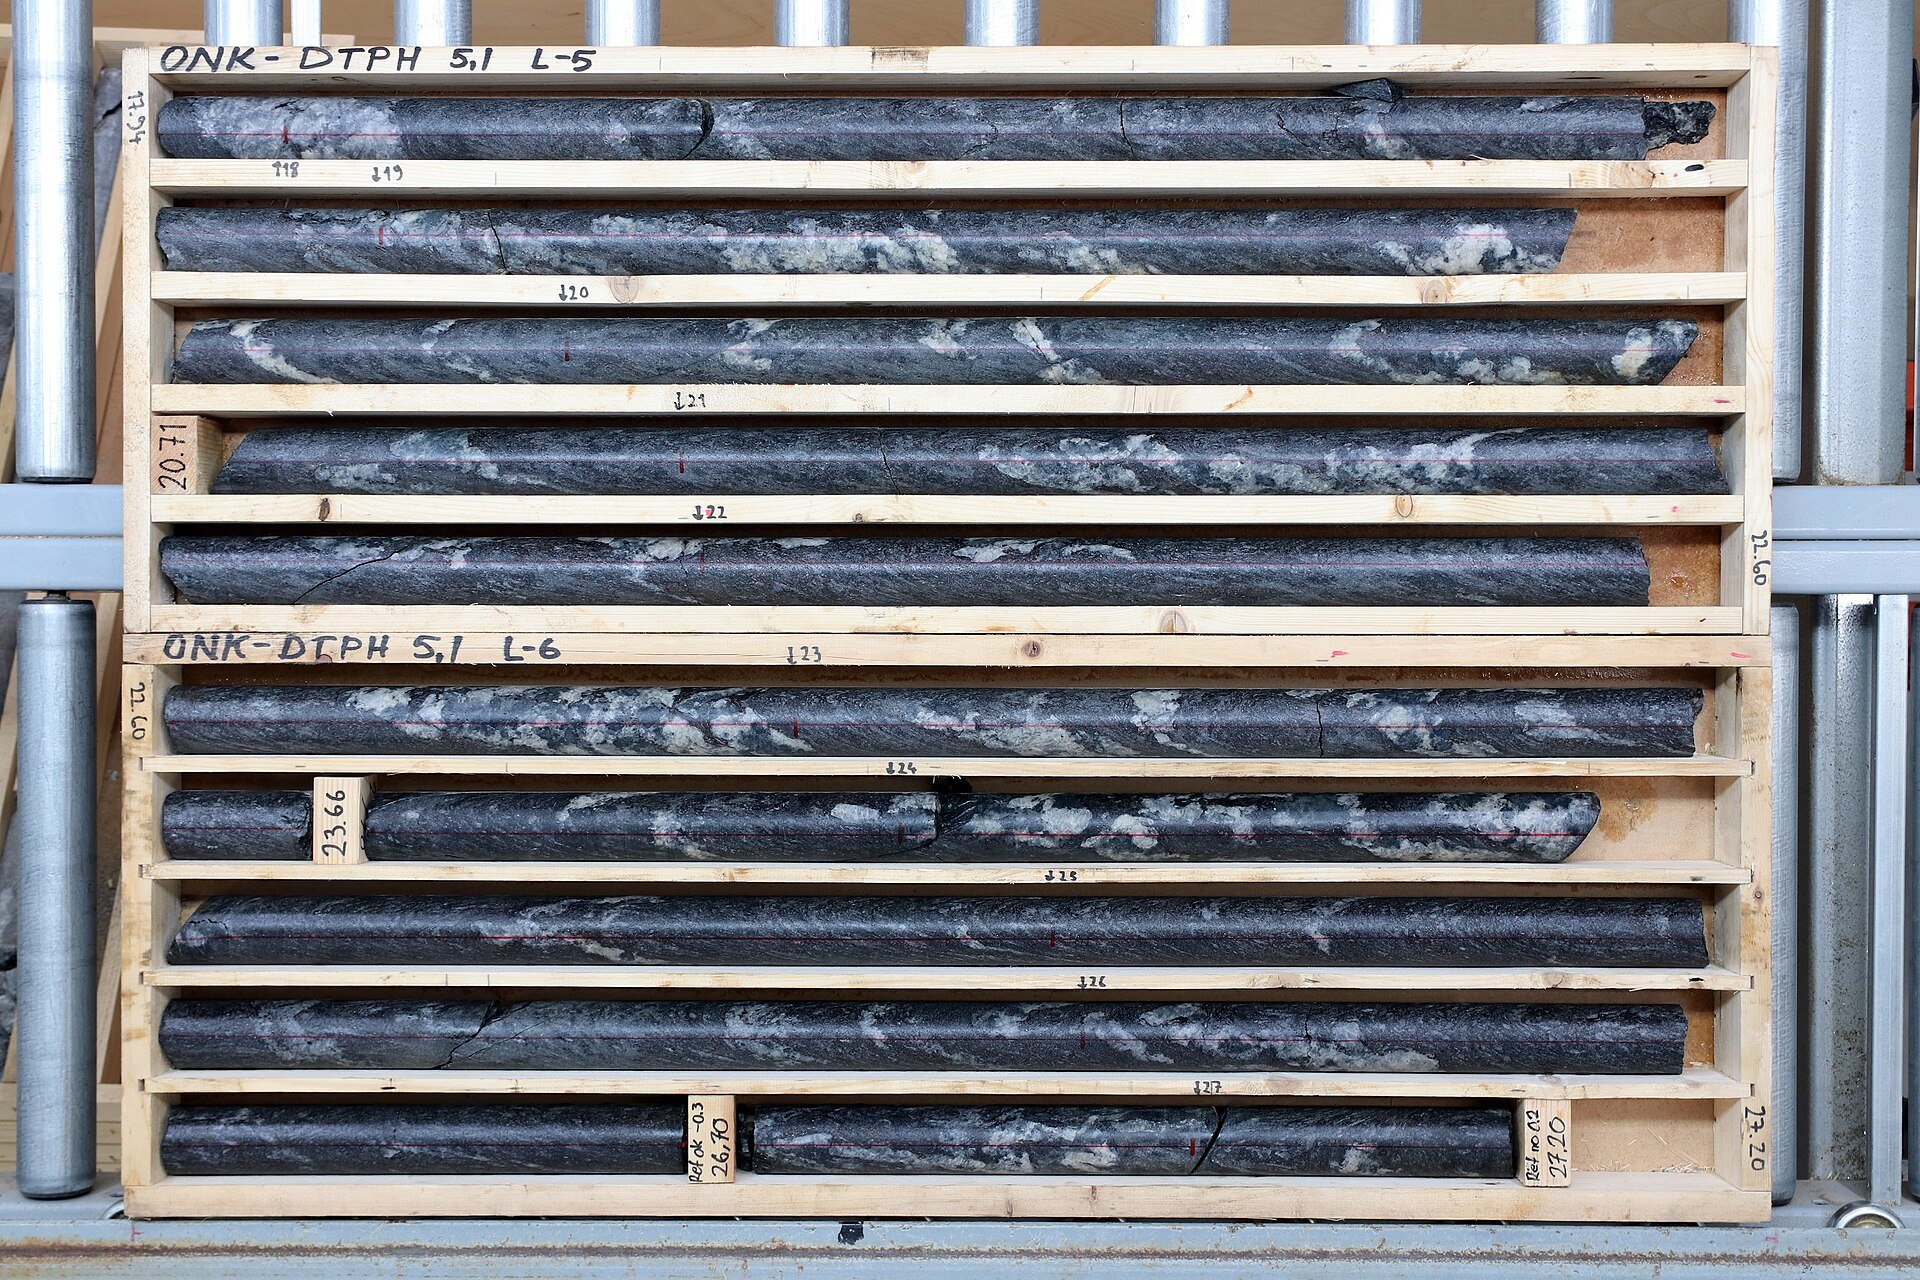
Patagonia Gold Corp. released an independent Preliminary Economic Assessment (PEA) for its flagship Calcatreu Gold-Silver Project in Argentina, prepared by NCL Ingenieria y Construccion SpA. The PEA outlines a 16-year mine life with an after-tax NPV (10%) of US$334 million, an after-tax IRR of 282%, and a payback period of 0.6 years. Life-of-Mine (LOM) production is estimated at ~483,000 ounces of gold and 3.25 million ounces of silver.
Economic metrics are based on gold at US$3,500/oz and silver at US$35/oz. At release, spot prices were significantly higher: gold at US$4,284/oz and silver at US$64.16/oz. The initial capital requirement is ~US$52.5 million, of which ~US$30.7 million was already incurred in 2025. Sustaining capital over LOM is ~US$47 million. Cash cost is US$2,139/oz and AISC is US$2,246/oz. Heap leach recoveries are 63% for gold and 30% for silver.
The updated Mineral Resource Estimate (MRE) totals 13.22 million tonnes grading 2.18 g/t AuEq. Approximately 84% of plant feed in the first five years is sourced from Measured and Indicated resources. Mining will be conventional open-pit, processing via crushing, heap leaching, and carbon-in-column (CIC).
Patagonia Gold Corp. (PGDC) has released a Preliminary Economic Assessment (PEA) that provides the first independent economic validation of the Calcatreu project, confirming it as a long-life, low-cost operation with strong margins at current metal prices. The reported economics are conservative, utilizing trailing 3-year average prices of $3,500 per ounce for gold and $35 per ounce for silver, which are well below current spot levels of $4,284 per ounce for gold and $64.16 per ounce for silver. A re-run of the model at spot prices would materially increase the net present value (NPV) and internal rate of return (IRR).
Despite the positive technicals, the market reaction has been muted to negative. The stock has declined from $1.33 in March to $0.41 in late September, indicating that investors are pricing in liquidity constraints, execution delays, and jurisdictional risks rather than the technical upside.
Patagonia Gold Corp. (PGDC) is a TSX Venture-listed precious metals producer focused on gold and silver projects in Argentina. Its flagship asset is the Calcatreu heap leach project in Rio Negro, which is transitioning from construction to early production. The company also operates the Cap-Oeste residual heap leach facility in Santa Cruz, which is generating declining gold-equivalent ounces.
Patagonia Gold holds exploration assets including La Manchuria in Santa Cruz, as well as the Tornado and Huracán projects, spread across a large land package in the Deseado Massif and Gastre Fault System. The company is strategically divesting non-core exploration assets via earn-in agreements, such as the arrangement with Astra Exploration at La Manchuria, to focus capital on Calcatreu.