i-80 Gold Announces Initial Assay Results From Mineral Point Open Pit Project in Nevada Including a Step-Out Hole of 1.33 g/t Au and 39.2 g/t Ag Over 225.6 Meters
i-80’s Mineral Point infill confirms the bulk oxide model while east step-outs hint at a one-kilometre strike length.
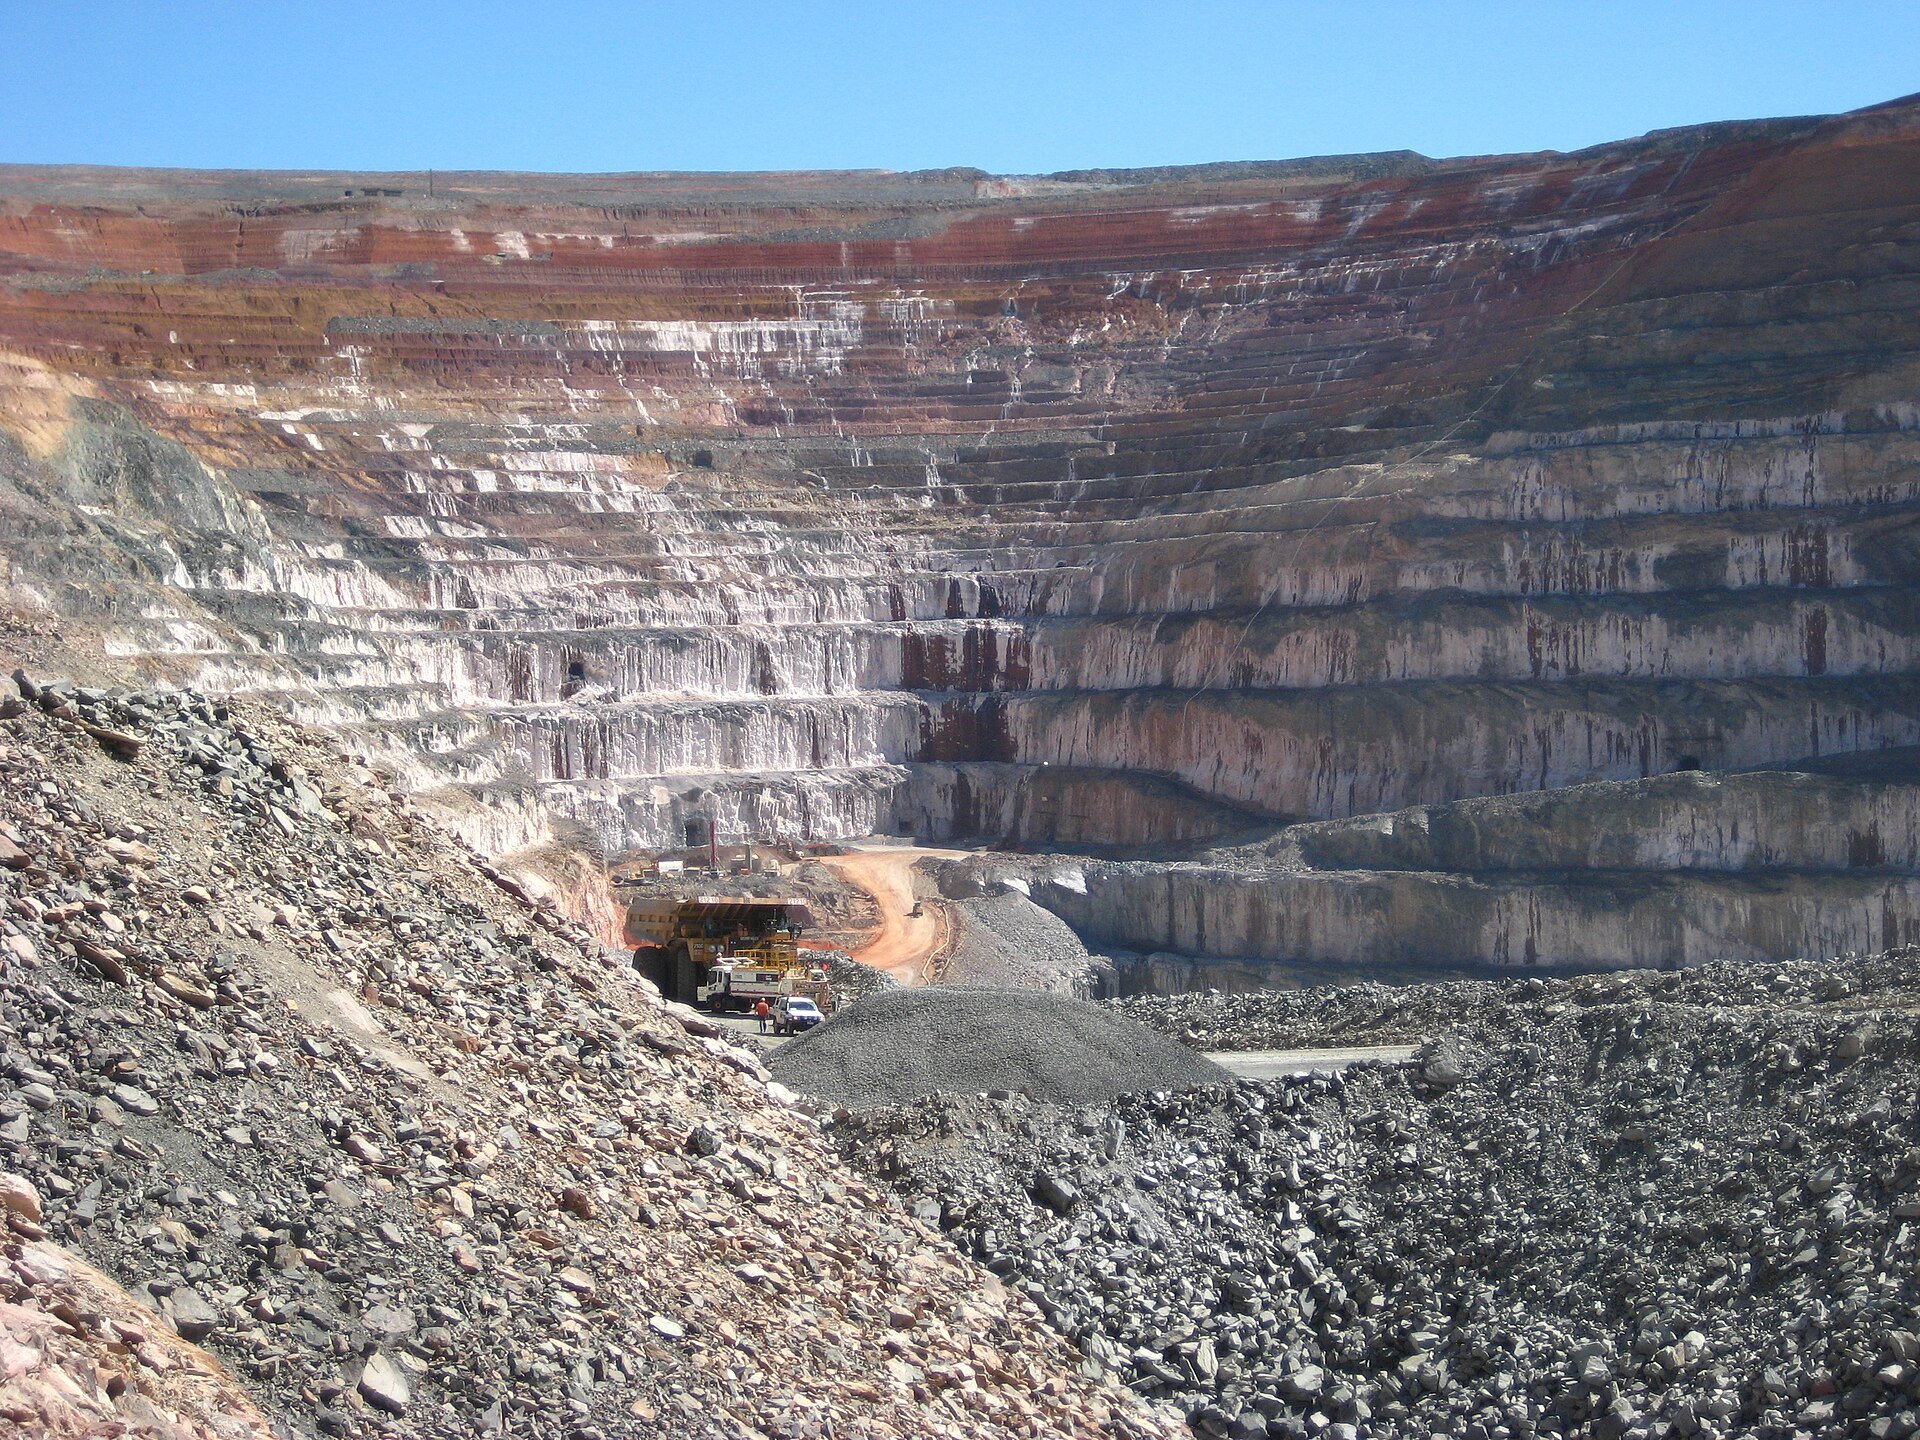
i-80 Gold Corp. (IAU) has released the initial assay results from the 2026 Mineral Point infill and step-out drilling program at its wholly owned Ruby Hill property in Nevada. The first batch of results includes 35 reported holes, with 19 identified as step-outs located outside the 2025 Preliminary Economic Assessment (PEA) pit shell. All 19 step-out holes intersected mineralization. Through the end of August, approximately 30,000 meters of the planned 130,000-meter, 300-hole program had been completed, with the revised completion date now set for the first quarter of 2027.
Key headline intercepts from the campaign include hole iMP26-07 (RC, step-out), which returned 1.33 g/t Au and 39.2 g/t Ag over 225.6 meters (216.4–442.0 m downhole). Hole iMP26-23 (RC, step-out) reported 1.70 g/t Au and 61.5 g/t Ag over 170.7 meters (249.9–420.6 m). Additional step-out results include iMP26-09, which returned 0.82 g/t Au and 40.1 g/t Ag over 202.7 meters (262.1–464.8 m), and iMP26-11, which returned 1.57 g/t Au and 72.5 g/t Ag over 71.6 meters (204.2–275.8 m).
Other reported intercepts include iMP26-32, which returned 0.36 g/t Au and 24.1 g/t Ag over 263.7 meters, and iMP26-35, which returned 0.52 g/t Au and 11.5 g/t Ag over 213.4 meters. Core drilling results include iRH26-05, which returned 0.99 g/t Au and 5.9 g/t Ag over 201.4 meters, and iMP26-17, which returned 0.85 g/t Au and 87.7 g/t Ag over 93.0 meters.
The 2025 PEA outlines a 17-year mine life with production of approximately 280,000 ounces of gold equivalent per year after ramp-up. At gold and silver prices of $2,175/oz and $26/oz respectively, the project yields an after-tax NPV(5%) of $614 million and an IRR of 12%. At higher prices of $3,000/oz for gold and $35/oz for silver, the NPV(5%) rises to $2.3 billion with an IRR of 29%. The current resource estimate at a 0.1 g/t Au cutoff includes Indicated resources of 217 million tonnes at 0.48 g/t Au and 15.0 g/t Ag (3.38 million ounces of gold and 104 million ounces of silver), and Inferred resources of 194 million tonnes at 0.34 g/t Au and 14.6 g/t Ag (2.12 million ounces of gold and 91 million ounces of silver).
The 2026 and 2027 Mineral Point program is budgeted at $40–45 million, plus approximately $5 million for technical and permitting costs, funded through proceeds from the Franco-Nevada royalty.
i-80 Gold Corp. (IAU) is a near-C$US2.1B developer and emerging producer holding $465M in cash and multiple projects, including a Preliminary Economic Assessment (PEA) already completed on Mineral Point. This is not a grassroots explorer discovery-hole situation, so the explorer upside rule does not apply.
The purpose of the recent drilling was to infill to upgrade Inferred resources and support a Preliminary Feasibility Study (PFS) scheduled for mid-2027, as well as to conduct step-outs to test expansion. The infill serves as a confirmation of a resource the market already prices, while the step-outs represent the only genuinely new element.
There is no prior Mineral Point drill anchor on this zone for the market to have paid for, as this is the first assay release of the 2026 program. The relevant anchor is the 2025 PEA resource grade of 0.48 g/t Indicated and its $614M net present value (NPV). The holes match or modestly beat that grade, and the largest hole's gram-metres are not a downgrade against anything previously demonstrated. The stock is up from the ~$1.26 low but has round-tripped from the $2.85 high, so no single Mineral Point result is embedded in the price.
The delta is neutral-to-mildly-positive on grade and width and genuinely positive on step-out expansion. However, it is early, with only 35 of ~300 holes drilled and most assays pending. The project is in Phase 3 with production expected in 2030 or later, and the PEA already assumes a large system. On a $2.1B equity, this does not change reserves, mine life, or NAV in a way that should re-rate the stock.
i-80 Gold Corp is a Nevada-focused gold company executing a three-phase plan toward mid-tier producer status, utilizing a hub-and-spoke strategy centered on the refurbished Lone Tree autoclave/CIL plant, which has a capacity of 2,268 t/d and cost approximately $430M. The company’s asset portfolio includes the Granite Creek Underground mine, which is currently in ramp-up following the release of its feasibility study; the project holds 556,500 oz of P&P reserves at 7.87 g/t, yielding an after-tax NPV of $118M at $2,750/oz. The Archimedes Underground project is in construction, with first gold targeted for Q4 2026, and contains an Indicated resource of 436 koz at 7.6 g/t and an Inferred resource of 988 koz at 7.3 g/t. The Mineral Point Open Pit represents the largest resource, comprising an Indicated estimate of ~3.4 moz Au and 104 moz Ag, alongside an Inferred estimate of ~2.1 moz Au and 91 moz Ag. Other assets include the Cove Underground, Granite Creek Open Pit, and Lone Tree open pit, while non-core FAD assets are being evaluated for sale.
As of June 30, 2026, i-80 Gold Corp reported approximately $464.6M in cash, total debt of ~$445.7M, and working capital of ~$454M. The company completed a recapitalization exceeding $1B in Q1 2026, which included a Franco-Nevada royalty, a gold prepay, and convertible notes. The company states that its going-concern flag is false.
Current production is under 50 koz. The company’s 2026 guidance calls for 30–40 koz from Granite Creek UG and ~10 koz from Archimedes/heap leach. Production is targeted to reach 150–200 koz by 2028 and 600 koz+ by the early 2030s.