Bravo Intercepts 54m at 2.8 g/t PGM+Au + 0.16% Ni, including 5m at 10.7 g/t PGM+Au + 0.40% Ni at Luanga
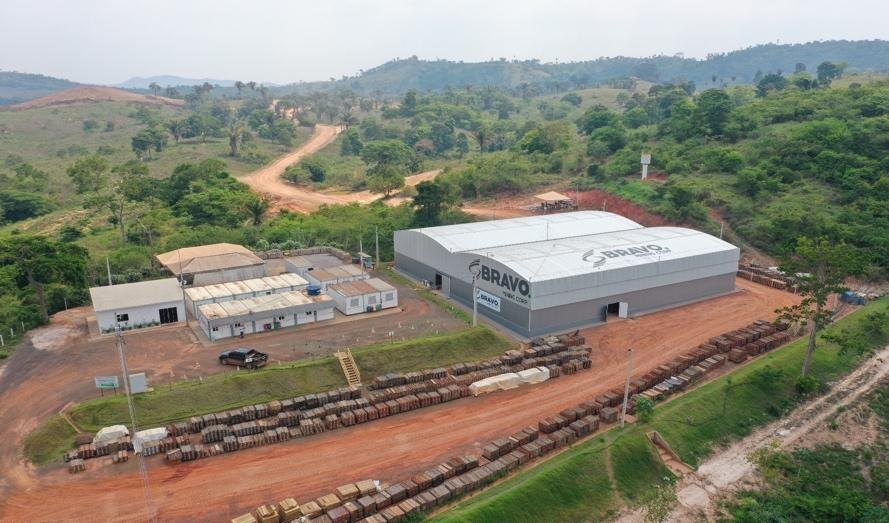
Bravo Mining Corp. (BRVO) completed eight diamond drill holes totaling 2,655 meters in an infill and extensional program at its Luanga project. The drilling targeted the Central Sector, where seven holes were drilled, and the North Sector, where one hole was completed.
Key reported intercepts include: * DDH26LU336: 53.85m @ 2.83 g/t PGM+Au + 0.16% Ni, including 5.01m @ 10.68 g/t PGM+Au + 0.40% Ni. * DDH26LU321: 39.75m @ 3.02 g/t PGM+Au + 0.32% Ni, including 2.21m @ 8.47 g/t PGM+Au + 0.03% Ni. * DDH26LU322: 16.35m @ 3.05 g/t PGM+Au + 0.23% Ni, including 4.62m @ 7.54 g/t PGM+Au + 0.32% Ni. * DDH26LU323: 52.45m @ 2.06 g/t PGM+Au + 0.11% Ni. * DDH26LU342: 36.65m @ 3.05 g/t PGM+Au + 0.32% Ni. * DDH26LU325: 22.00m @ 2.07 g/t PGM+Au + 0.09% Ni. * DDH26LU327: 23.95m @ 2.11 g/t PGM+Au + 0.24% Ni. * DDH26LU326: 23.10m @ 1.47 g/t PGM+Au + 0.20% Ni, plus a shallow oxide interval.
The company stated that the results are equal to or better than those from shallower drilling and will support resource conversion.
Bravo Mining Corp. (BRVO) is an advanced developer with a 10.4 moz PdEq Measured and Indicated resource, a Preliminary Economic Assessment showing a Base case NPV8 of US$1.25bn and an Alternate case of US$1.86bn, and a market capitalization around C$428M. The recent infill drilling results support upgrading Inferred resources to Indicated and may add depth to the Q1 2027 Mineral Resource Estimate, but they do not open a new district, define a new high-grade zone, or transform project economics.
The stock had already re-rated from roughly C$2.30 in early August to C$3.2-3.4 following the Babylon Ni/Cu release. This main-deposit infill release is unlikely to produce a 15%+ move.
Bravo Mining Corp. (BRVO) is focused on the 100%-owned Luanga PGM+Au+Ni deposit in the Carajás Mineral Province, Pará, Brazil. The company’s Measured and Indicated resource stands at 158 Mt @ 2.04 g/t PdEq for 10.4 moz, while the Inferred resource totals 78 Mt @ 2.01 g/t PdEq for 5.0 moz.
A preliminary economic assessment outlines a 17-year mine life, projecting an after-tax NPV8% of US$1.25bn under the Base case and US$1.86bn under the Alternate case, with an internal rate of return of approximately 49%. Beyond the primary deposit, Luanga also hosts the high-grade T5 IOCG copper-gold target and the emerging Babylon Ni/Cu target.
As of June 30, 2026, the company held approximately US$94M in cash per its investor presentation, with no operating revenue. Royalty obligations include 1% to Vale and 2% to BNDES. Luanga serves as the anchor project for the Barcarena Export Processing Zone.