Lundin Mining Announces Vicuna Integrated Technical Study Results Highlighting a World-Class Mining District
Lundin’s Vicuña District PEA Outlines a Multi-Generational Monster with a Massive $18 Billion Capital Hurdle
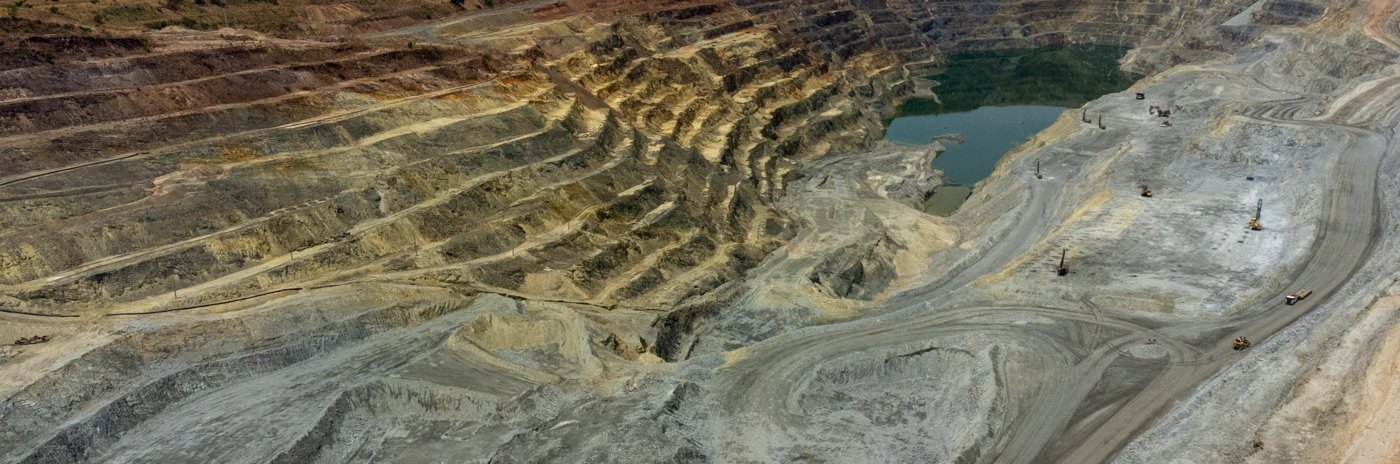
The most recent news (February 16, 2026) announces the results of the Integrated Technical Study (PEA) for the Vicuña Project, a 50/50 joint venture with BHP. The study outlines a staged development of the Filo del Sol and Josemaria deposits in Argentina/Chile. Key metrics include a 70-year mine life with an initial three-stage capital cost totaling $18.1 billion USD. Average annual production for the first 25 years is projected at 395,000 tonnes of copper, 711,000 ounces of gold, and 22.2 million ounces of silver. The project boasts a base case after-tax NPV8% of $9.5 billion USD and an IRR of 14.8% at $4.60/lb copper. Notably, cash costs net of by-products for the first 25 years are projected to be negative (-$0.20/lb), making it one of the lowest-cost copper assets globally if realized.
The news is Material - Positive but carries significant capital execution risk. - Scale and Longevity: A 70-year mine life and production profile ranking in the top five global copper-gold-silver mines transforms Lundin from a mid-tier producer to a global major. - Economic Sensitivities: While the 14.8% IRR at base case is somewhat lean for a project of this scale in Argentina, the sensitivity to spot prices (25.5% IRR and $28.8 billion NPV) highlights massive leverage to current metal prices. - Cost Structure: Negative net cash costs (-$0.20/lb Cu) for the first quarter-century of production provide a massive cushion against commodity price volatility. - Funding: The company concurrently announced commitments to upsize its credit facility to $4.5 billion USD, which management claims fully funds Lundin's share of initial Stage 1 construction ($3.55 billion USD).
Lundin Mining is a diversified base metals producer with operations in Chile (Candelaria, Caserones), Brazil (Chapada), and exploration/development in Argentina. Following the sale of its European assets and the Eagle mine, LUN is now a "pure-play" copper growth vehicle. The flagship project is the Vicuña District (50% interest), which combines the Josemaria and Filo del Sol deposits. The company aims to become a top-10 global copper producer with output exceeding 500,000 tonnes per year once Vicuña is fully operational.