Earnings
Hemlo Mining Corp. Reports Fourth Quarter and Year End 2025 Financial and Operating Results
Hemlo Mining Consolidates Balance Sheet Post-Acquisition but Production Guidance Remains Key Catalyst
Executive Summary
Financial Performance and Acquisition Context
- Acquisition Completion: Hemlo Mining Corp. completed the acquisition of the Hemlo Gold Mine from Barrick Mining Corporation on November 26, 2025, for approximately US$1.1 billion.
- Net Loss: Reported a net loss of $36.9 million for the full year 2025 and $36.2 million for Q4 2025.
- Loss Drivers: The losses are primarily driven by transaction costs ($15.9 million) related to the acquisition and a $11.4 million loss on revaluation of Contingent Consideration, rather than operational inefficiencies.
- Cash Position: Held $132.0 million in cash as of December 31, 2025.
- Debt Management: Repaid the full $75.0 million balance on its Revolving Credit Facility (RCF) in March 2026, reducing that portion to nil. A $150.0 million term loan remains outstanding with quarterly repayments beginning August 2026.
- Production: Achieved gold production of 16,503 attributable ounces at 4.71 g/t during the post-acquisition period (Nov 26 – Dec 31, 2025). Full Year 2025 attributable production was reported as 120,841 ounces in this release, contrasting with a previous announcement of 143,458 ounces.
Operational and Exploration Updates
- Drilling Program: Initiated a significant 130,000-metre exploration drilling program for 2026 focused on resource conversion (70,000m), de-risking mine plan (30,000m), and growth targets (30,000m).
- Infrastructure: Investing over $30 million in 21 new pieces of mobile equipment to modernize the fleet.
- Royalty Consolidation: Repurchased a 1.5% net smelter return (NSR) royalty interest associated with the David Bell property in 2026.
Material Impact
Evaluation of Most Recent News
- Financial Stability Confirmed: The repayment of the $75 million RCF demonstrates strong cash flow generation post-acquisition, validating the CFO's statement on financial discipline. This reduces leverage risk significantly compared to the initial acquisition financing structure.
- Loss Explanation: While a net loss is typically negative, the breakdown confirms it is non-recurring (transaction costs and contingent consideration revaluation). The operational performance appears stable with production meeting Barrick's guidance for the year.
- Production Discrepancy Risk: There is a notable discrepancy in Full Year 2025 production figures between the February release (143,458 ounces) and this April earnings release (120,841 ounces). This inconsistency requires scrutiny regarding attribution timing or accounting adjustments.
- Debt Service Pressure: The remaining $150 million term loan creates a fixed obligation with quarterly repayments starting August 26, 2026 ($7.5 million each). With cash at $132 million, the company has a buffer, but sustained production is required to service debt without further dilution or refinancing.
- Market Expectation: The market had already priced in the acquisition (December 2025) and the drilling upside (February 2026). This earnings release confirms execution but does not introduce new speculative catalysts, resulting in a "Routine" classification rather than "Material".
Comparison to Historical News
- Debt Repayment: The April 15 news confirms the April 2 announcement of RCF repayment. It adds context that cash remains healthy ($132M) despite the acquisition outflow.
- Exploration: The 130,000-metre program announced in January is confirmed as active. No new drill results are included here, deferring value realization to future releases (H2 2027 technical report).
- Valuation Context: The stock price has corrected from the February highs ($8.05) to current levels ($6.10), suggesting the market is digesting the earnings loss and waiting for FY2026 guidance expected in Q3 2026.
HMMC · Price
Company Overview
Asset Profile
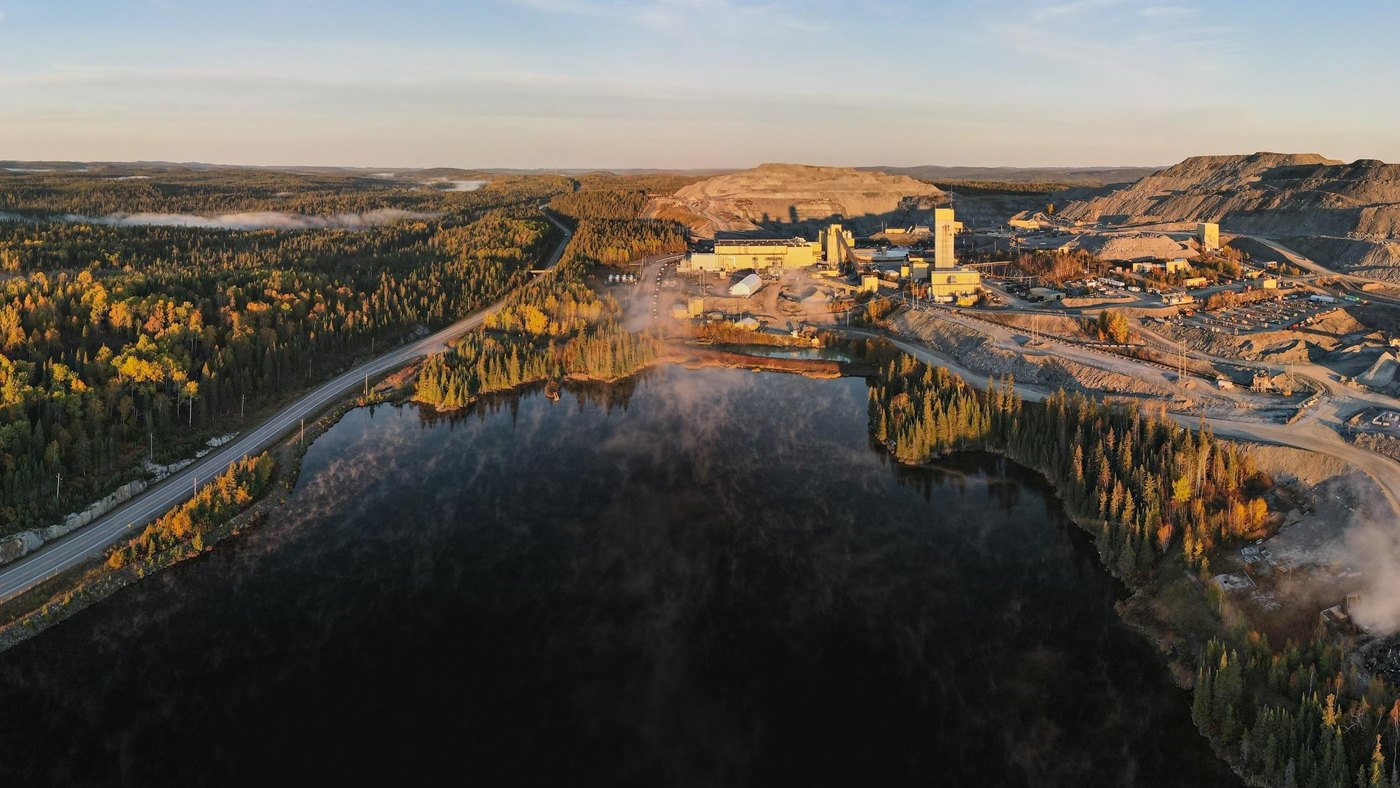
- Flagship Project: Hemlo Gold Mine (Ontario, Canada).
- Status: Producing underground mine with planned open-pit restart.
- History: Produced ~25 million ounces of gold since 1985; acquired from Barrick Mining Corporation in November 2025.
- Infrastructure: Under-utilised underground infrastructure and mill capacity capable of ramping to 4,800 tpd without major upgrades; potential to reach historic 10,000 tpd.
- Cost Structure: Life-of-Mine (LOM) AISC guidance is approximately $1,395/oz Au.
Strategic Positioning
- Model: Hybrid owner-operator transition with Manroc Developments Inc. to improve cost control and workforce stability.
- Exploration Focus: Brownfield exploration around the Hemlo camp and adjacent "Rocky Shore" land package.
- Production Guidance: Technical Report average 138 koz Au/yr (approx. 2.1 Moz LOM production from 2P reserves).
More from Hemlo Mining Corp.
Oct 21, 2026 · 06:30