Earnings
Hemlo Mining Corp. Reports First Quarter 2026 Operating Results
Hemlo Mining Corp.
Executive Summary
- Event: Hemlo Mining Corp. reported First Quarter 2026 Operating Results on April 28, 2026.
- Production: Total gold production of 34,764 oz (29,699 oz attributable). Williams Mine produced 24,630 oz; Interlake Claims produced 10,129 oz.
- Operations: Successfully transitioned to an owner-operated model on March 16, 2026, two weeks ahead of schedule. 97% of contractor workforce retained.
- Financials: Net debt reduced significantly from $93M (Dec 31, 2025) to $26.2M (March 31, 2026). Cash balance stands at $123.8M. Revolving credit facility fully repaid.
- Exploration: Launched a 130,000-metre drill program in Q1 focused on resource conversion and growth.
- Safety: No Lost Time Injury (LTI) events for 33 consecutive months; awarded John T. Ryan Trophy.
Material Impact
- Confirmation of Prior Announcements: The debt reduction reported here ($93M to $26M) largely confirms the April 2, 2026 announcement regarding the $75 million repayment of the revolving credit facility. The market had already priced in this deleveraging action.
- Operational Validation: The transition to an owner-operated model ahead of schedule is a positive operational milestone, reducing reliance on contractors and potentially improving long-term cost control (AISC target ~$1,395/oz). However, one quarter of data is insufficient to confirm sustained efficiency gains.
- Production Ramp-Up: Attributable production nearly doubled from the partial Q4 2025 period (16,503 oz) to full Q1 2026 (29,699 oz). This aligns with management's guidance for a ramp-up but does not exceed expectations significantly enough to be considered "Material - Positive" in isolation.
- Cash Flow Strength: The ability to pay down $67M of net debt while maintaining cash reserves above $100M demonstrates robust free cash flow generation, mitigating near-term dilution risk.
- Risk Assessment: While positive, the news is expected following the acquisition close and previous financing updates. It validates the thesis rather than altering it fundamentally.
HMMC · Price
Company Overview
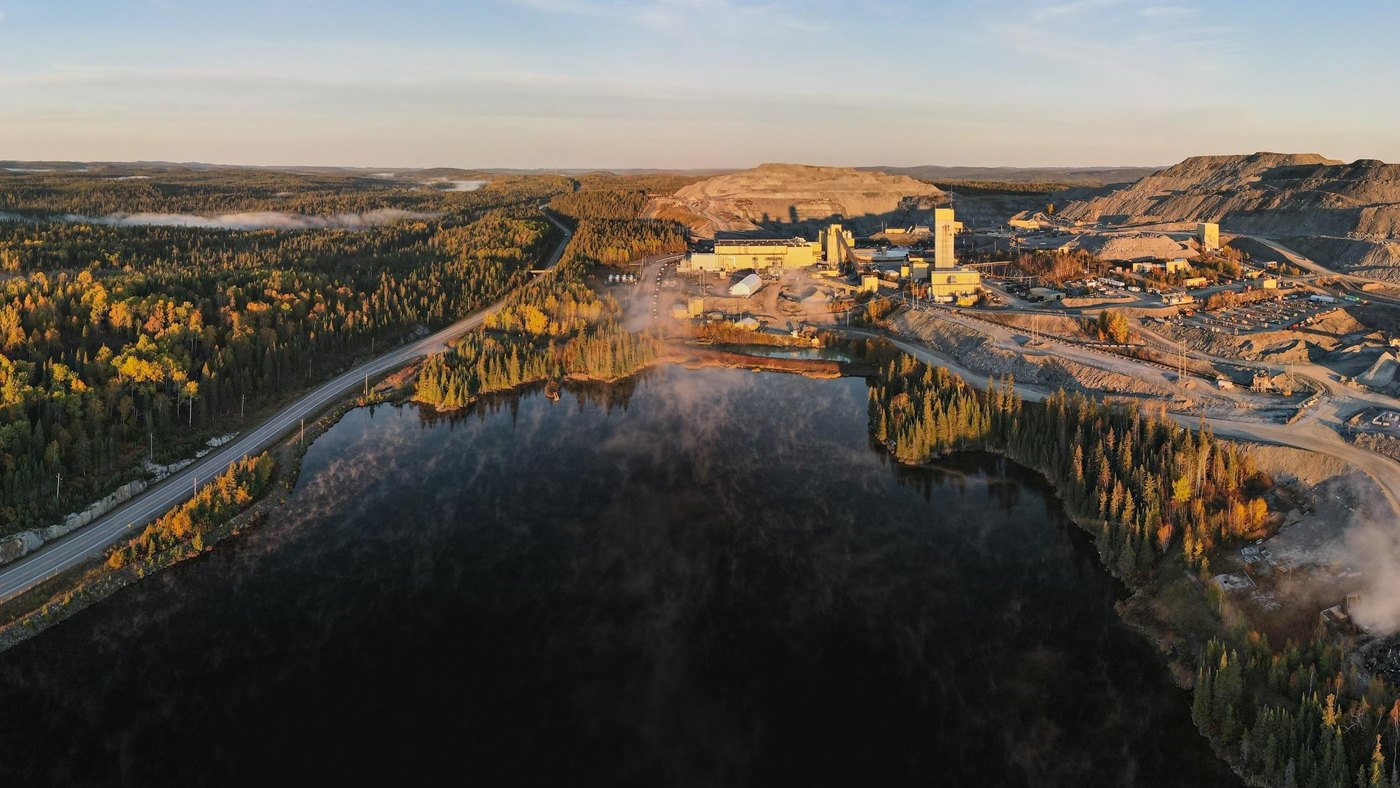
- Company: Hemlo Mining Corp. is a Canadian mid-tier gold producer focused on the Hemlo Gold Mine in Ontario, Canada.
- Flagship Project: The Hemlo Gold Mine (Williams and Interlake operations). Historically produced ~25 million ounces since 1985.
- Status: Producing underground with plans to re-establish open-pit mining (Williams pit push-back) starting ~2028.
- Strategy: "Fit-for-purpose" optimization, leveraging under-utilized infrastructure and aggressive brownfield exploration to extend mine life and increase reserves.
More from Hemlo Mining Corp.
Oct 21, 2026 · 06:30