Earnings
Minera Alamos Reports First Quarter 2026 Gold Production of 8,734 Ounces; Cash Balance Increased to $46 Million
Minera Alamos Cash Buoyed by Credit Line as Nevada Output Holds Steady
Executive Summary
- Date: April 13, 2026
- Headline: Minera Alamos Reports First Quarter 2026 Gold Production of 8,734 Ounces; Cash Balance Increased to $46 Million
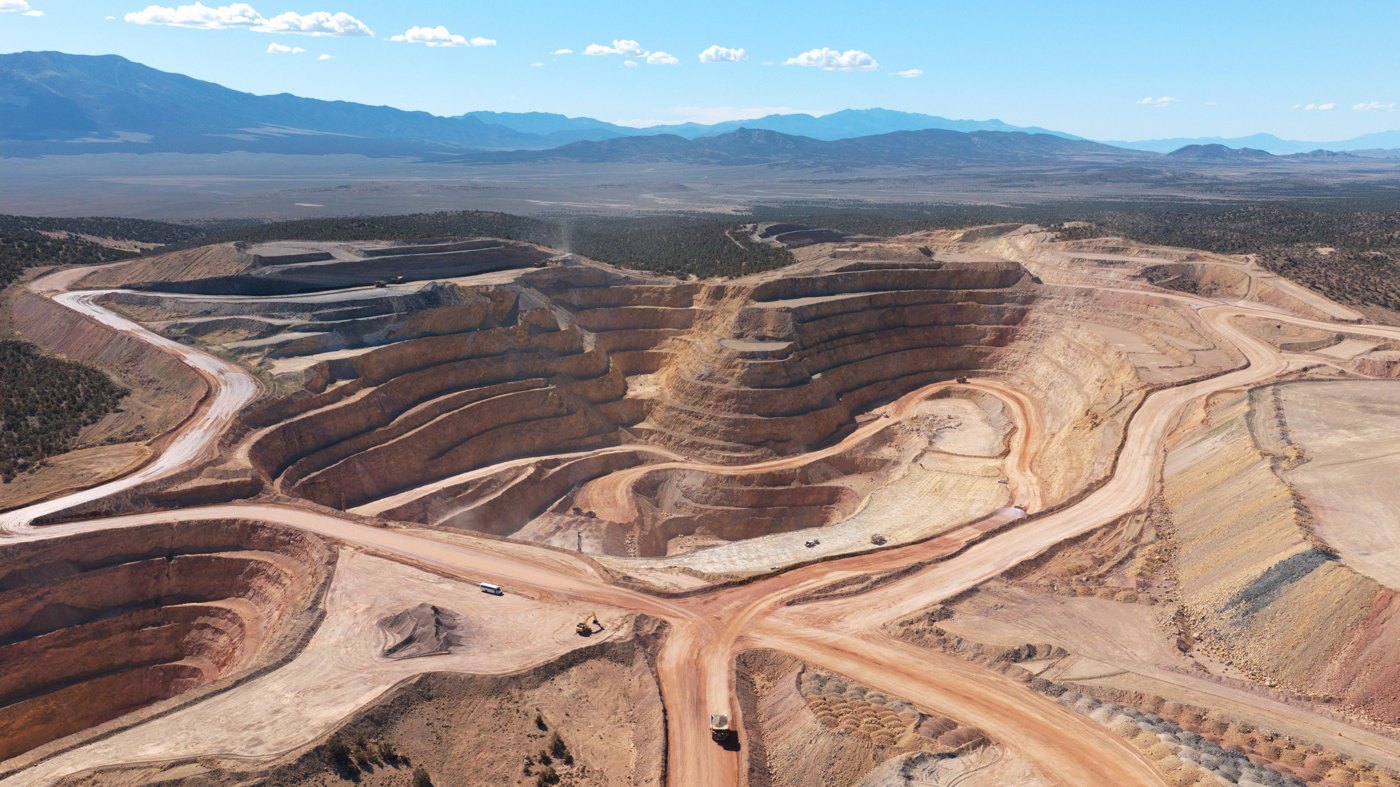
- Production: Q1 2026 gold production was 8,734 ounces from the Pan mine (Nevada). Sales were 9,134 ounces.
- Financials: Unrestricted cash balance increased to $46 million as of March 31, 2026, up from $34 million at year-end 2025.
- Guidance: Full-year 2026 production guidance remains unchanged at 32,000–38,000 ounces.
- Liquidity: Company cites cash flow and a term sheet for a $75 million revolving credit facility (Scotiabank/National Bank) as sources of ample liquidity.
- Context: This update follows the March 31 announcement regarding the executed term sheet for the credit facility intended to replace a $25 million gold prepayment loan.
Material Impact
- Routine Nature: The production figure (8,734 oz) is consistent with the full-year guidance of 32,000–38,000 ounces (implying ~8,000–9,500 oz per quarter). It does not exceed expectations significantly nor miss them materially.
- Cash Position: The increase in cash to $46 million is positive but expected given the operational cash flow and the previously announced credit facility term sheet from March 31, 2026.
- Financing Confirmation: The news reiterates the liquidity position secured via the $75 million revolver term sheet announced two weeks prior. This confirms execution but does not introduce new capital market events.
- Cost Inflation Risk: While production is steady, previous guidance (Feb 2026) indicated rising AISC ($1,850–$2,000/oz vs Q4 2025 actual of $1,604/oz). This news does not address cost mitigation, leaving margin pressure as a lingering risk.
- Conclusion: The update validates the company's operational trajectory and liquidity management but offers no new catalysts to re-rate the stock significantly higher than current levels.
MAI · Price
Company Overview
- Overview: Minera Alamos is transforming into a U.S.-focused intermediate gold producer following the acquisition of the Pan Operating Complex from Equinox Gold (closed Oct 1, 2025).
- Flagship Project: Pan Mine (Nevada). Open-pit heap-leach operation producing ~35,000 oz/year. Acquired for $88M cash + equity.
- Development Pipeline:
- Copperstone (Arizona): Underground project; PEA shows high IRR (152% @ $2,800/oz). PFS expected Q4 2026.
- Gold Rock (Nevada): Adjacent to Pan; potential to extend mine life via integration.
- Cerro de Oro (Mexico): Open-pit heap-leach; permitting pending.
More from Minera Alamos Inc.
Oct 13, 2026 · 06:31