Other
Minera Alamos Announces Partial Repurchase of a Royalty on Its Cerro de Oro Project
Minera Alamos Clears Path for $75M Revolver with Royalty Buyback
Executive Summary
- Transaction: Minera Alamos announced an option exercise to repurchase a 0.75% Net Smelter Return (NSR) royalty on its Cerro de Oro project in Mexico from Auramet Capital Partners, L.P.
- Consideration: The purchase price is US$4.5 million, settled via the issuance of 895,572 common shares at C$6.91 per share (subject to TSXV approval).
- Strategic Context: This repurchase is a mandatory condition precedent for closing the proposed US$75 million revolving credit facility with Scotiabank and National Bank of Canada.
- Timing: The announcement follows the May 11, 2026 news regarding management changes and name change to "Mining Americas Inc.", which highlighted the imminent closing of the credit facility.
Material Impact
- Financing Progress: This news confirms active progress toward securing the US$75 million revolving credit facility (RCF) announced in March 2026. The removal of the royalty simplifies the security package required by lenders, reducing execution risk on the debt closing.
- Dilution Impact: The issuance of ~895k shares represents approximately 0.8% dilution to the existing share base (~108M outstanding). This is negligible relative to the company's market capitalization and significantly less dilutive than an equity raise would have been for similar funding.
- Asset Quality: Removing a royalty on Cerro de Oro improves the long-term margin profile of that specific project, though it does not immediately impact cash flow from the Pan mine which is the current production engine.
- Expectation Alignment: The market was already aware of the RCF term sheet (March 31) and expected closing conditions (May 11). Therefore, this news validates a known path rather than introducing new strategic direction. It is incremental progress on an anticipated milestone.
MAI · Price
Company Overview
- Strategy: Transformation into a U.S.-focused intermediate gold producer, shifting focus from development to production via the Pan Operating Complex acquisition.
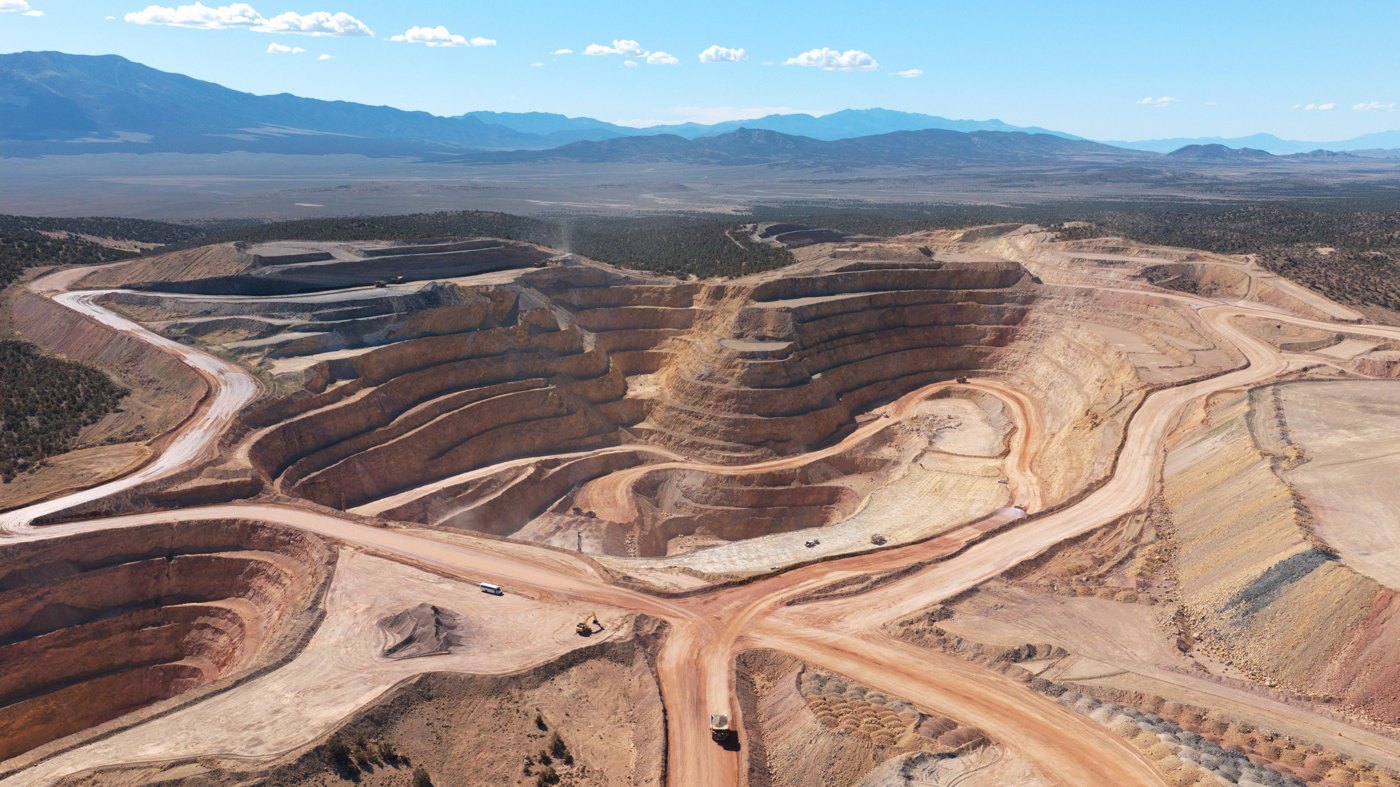
- Flagship Project: The Pan Mine in Nevada (Pan Operating Complex) is the primary cash-flow engine. It is an open-pit heap-leach operation producing ~35-40 koz annually.
- Pipeline: Includes Copperstone (Arizona), Gold Rock (Nevada), and Cerro de Oro (Mexico). These projects are intended to be funded by Pan mine cash flow and the new RCF, targeting >150 koz annual production long-term.
- Production Guidance: 2026 guidance for Pan Mine is 32,000–38,000 ounces of gold with AISC of US$1,850–2,000/oz.
More from Minera Alamos Inc.
Oct 13, 2026 · 06:31