Minera Alamos Moves to Strengthen Balance Sheet with Executed Term Sheet for US$75 Million Revolving Credit Facility from Scotiabank and National Bank
Minera Alamos Secures Tier-1 Bank Backing to Retire High-Cost Debt and Fuel U.S. Expansion
The most recent news (March 31, 2026) announces that Minera Alamos has executed a term sheet for a US$75 million senior secured revolving credit facility (RCF) with Scotiabank and National Bank. The three-year facility carries an interest rate of SOFR + 3.25–4.25%. The primary immediate use of proceeds is to repay a US$25 million gold prepayment facility with Auramet. This effectively replaces a physical gold delivery obligation (7,830 ounces) with a cash-settled debt instrument. Secondary uses include funding the Copperstone Gold Project (Arizona) and the Gold Rock Project (Nevada) without further equity dilution.
This is a Material - Positive development for several reasons: - Cost of Capital: Transitioning from a gold prepayment facility (which often carries high effective interest rates and caps upside during gold bull markets) to a traditional bank RCF significantly lowers the cost of debt. - Institutional Validation: Securing a US$75M facility from Tier-1 Canadian banks (Scotiabank and National Bank) represents a major "graduation" for the company, signaling that the Pan Mine acquisition has successfully de-risked the corporate profile in the eyes of conservative lenders. - Anti-Dilutive Growth: The facility provides the liquidity needed to advance Copperstone and Gold Rock toward production in 2026/2027 without issuing more shares, protecting existing shareholders after the heavy dilution of the 2025 acquisition. - Operational Flexibility: The RCF structure allows the company to draw and repay as needed, unlike the rigid delivery schedule of the Auramet facility.
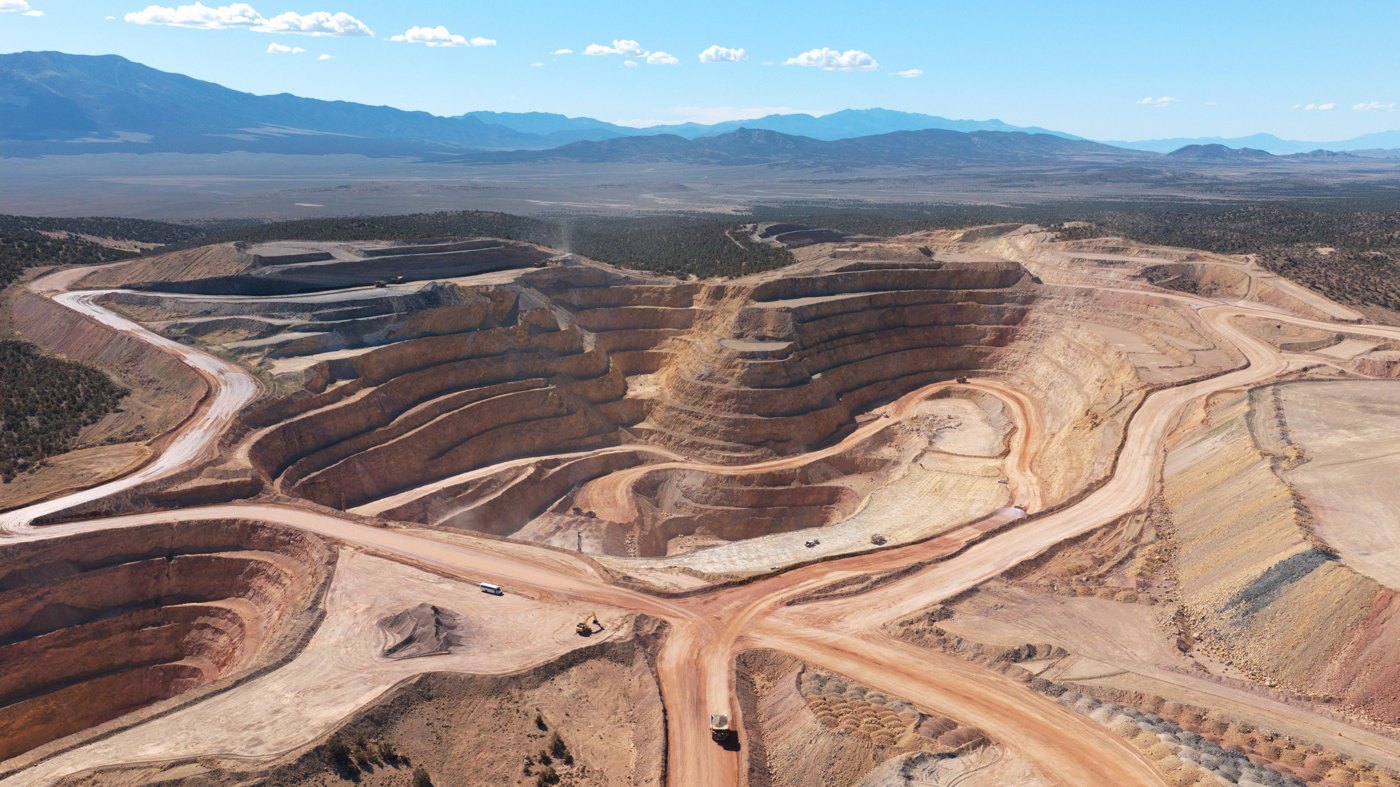
Minera Alamos is a gold producer transitioning from a junior developer to a mid-tier producer. - Flagship Project: The Pan Gold Mine (Nevada), acquired from Equinox Gold in late 2025. It is an open-pit, heap-leach operation producing ~30,000–40,000 oz/year. - Growth Pipeline: Includes the Copperstone underground project (Arizona) and the Gold Rock project (Nevada), which is adjacent to Pan and offers significant synergies. - Secondary Assets: Santana (Mexico) and Cerro de Oro (Mexico), the latter being a high-return heap leach project currently in the permitting phase.