Production / Operations
Equinox Gold Delivers Strong First Quarter with 197,628 Ounces of Gold Production, $990 Million of Debt Reduction and Inaugural Dividend Payment
“Debt‑free dividend debut fuels bullish outlook for Canada‑centric gold producer”
Executive Summary
- Q1 2026 production: 197,628 oz Au (Canadian assets 87,402 oz).
- Debt reduction: Repayment of US$990 M during the quarter, bringing net debt to roughly US$75 M.
- Shareholder return: Inaugural quarterly cash dividend of US$0.015 per share paid 26 Mar 2026; NCIB approved for up‑to 5% of shares.
- Operations update: Valentine Phase 2 expansion budget $414 M, 24‑month build funded by cash flow/credit line; Greenstone operating above nameplate on many days.
- Exploration: High‑grade “Minotaur” discovery at Valentine (8 km north of mill) and continued mineralization in the Frank Zone.
- Guidance outlook: Canadian production expected to average 543,000 oz/yr for 2026‑2036 based on updated technical reports.
Material Impact
| Aspect | Prior expectation | New information | Impact |
|---|---|---|---|
| Production | Q1 2025‑26 guidance ~700–800 k oz annual, with ramp‑up of Valentine | Delivered 197.6 k oz in Q1 2026, Canadian output strong and above nameplate on many days | Positive – confirms operational execution and supports higher‑end guidance |
| Debt profile | Net debt ≈ US$1.5 bn (drawn) | Repayment of US$990 M; net debt now ~US$75 M | Materially positive – dramatically improves balance sheet, lowers interest expense, frees cash for growth and returns |
| Dividend & NCIB | No dividend history; share‑repurchase pending | First quarterly dividend declared; NCIB approved up to 5% of shares | Positive – signals confidence in free cash flow and commitment to shareholder return |
| Exploration | Ongoing drilling at Valentine | New high‑grade Minotaur zone discovery (8 km from mill) | Positive – adds upside potential for future production, especially Phase 2 expansion |
| Overall market perception | “Outperform” rating; price range $7–9 in early 2025 | Stock now trading >$21 after debt reduction and dividend news | Game‑changer element but the primary driver is the material improvement to balance sheet and cash flow, thus classified as Material – Positive rather than a full game‑changer. |
The news aligns with the strategic narrative presented in the investor presentation (focus on deleveraging, cash returns, and Canadian growth) and materially improves the company’s financial flexibility.
EQX · Price
Company Overview
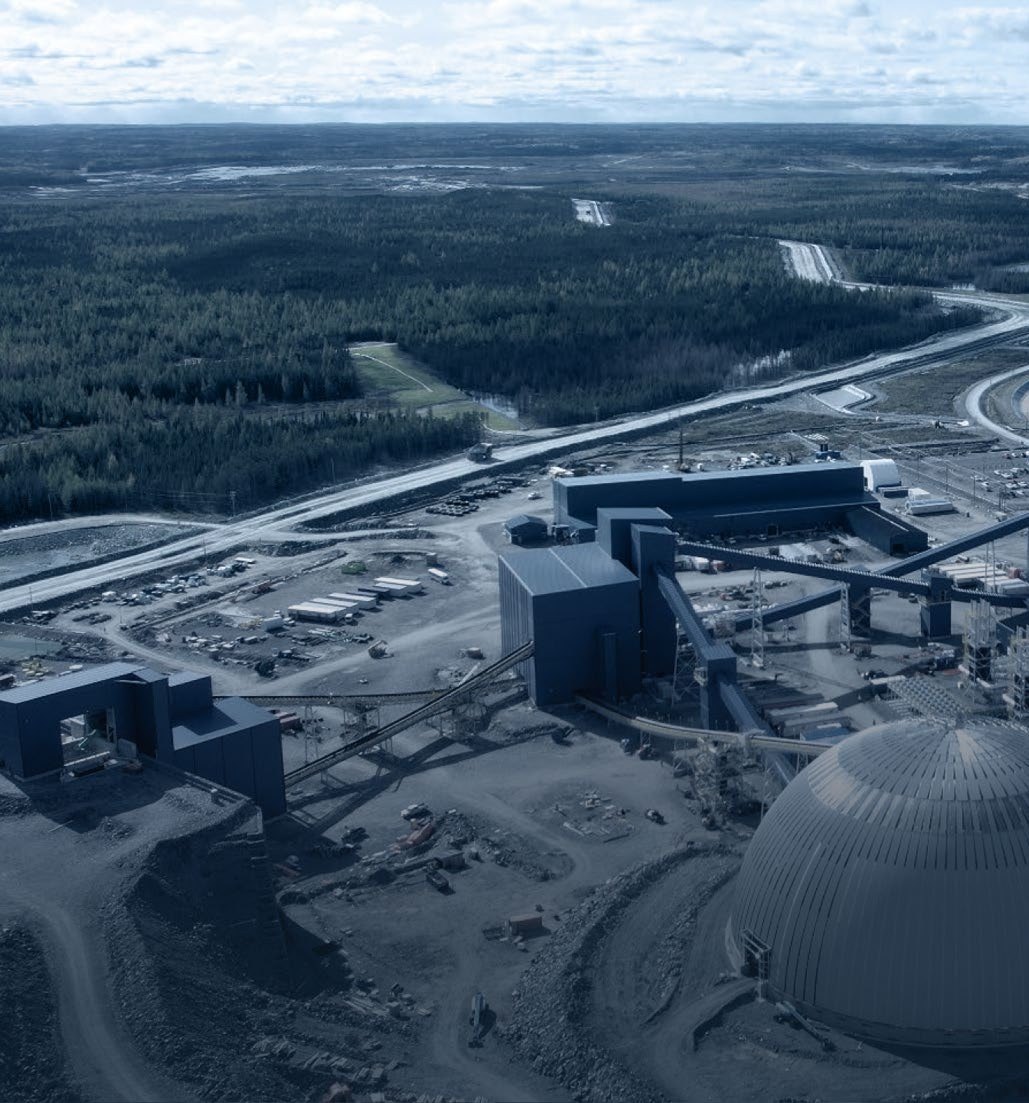
Equinox Gold is a mid‑tier gold producer focused on high‑margin, low‑cost assets in Tier 1 jurisdictions (Canada, USA, Mexico). Flagship projects are Greenstone (Ontario) – an open‑pit mine delivering >300 kt/yr at ~US$1.7k oz cash cost, and Valentine (Newfoundland) – a newly commissioned underground operation targeting 150–200 kt/yr with Phase 2 expansion to double throughput.
More from Equinox Gold Corp.
Oct 13, 2026 · 06:30