M&A / Property
G Mining Ventures Announces Uniquely Synergistic Acquisition of G2 Goldfields, Creating a Tier-One Gold Mining Hub in Guyana and One of the Largest, Lowest-Cost Gold Operations in the Americas
G Mining Ventures’ $3 bn Oko merger catapults G2 into tier‑one gold producer
Executive Summary
- Date: 2026‑04‑09
- Event: G Mining Ventures Corp. (GMIN) will acquire 100 % of G2 Goldfields Inc. via a court‑approved plan of arrangement, creating a combined “Oko” project in Guyana.
- Deal economics: Implied offer price C$10.84 per G2 share (72 % premium), equity value ≈ C$3.0 bn (ex‑G3 SpinCo). Post‑closing ownership: ~80.1 % GMIN shareholders, 19.9 % former G2 shareholders.
- Synergies & scale: >C$1 bn of quantified synergies (≈C$850 m capital cost avoidance, C$275 m operating cost savings). Combined Measured & Indicated resources rise to 7.0 Moz Au; Inferred to 2.3 Moz Au. Projected LOM average production >500 koz gold.
- Financing: GMIN cash on hand US$288 m and undrawn revolving credit facility US$350 m; free cash flow from Tocantinzinho (Brazil) will help self‑fund Oko development.
- Timeline: Transaction expected to close Q2 2026, subject to ≥66⅔ % G2 shareholder approval and court sanction. First production at Oko West targeted H2 2027; expanded production target H1 2029.
Material Impact
- Magnitude: The transaction more than triples the scale of G2’s flagship asset, moving it from a high‑grade exploration project to a tier‑one, low‑cost gold mine with >500 koz annual output.
- Market expectations: Prior to the announcement, investors anticipated a spin‑out (G3) and modest financing but not a full acquisition that creates a combined 7 Moz resource base. The premium and synergy estimate are well above consensus, making this news materially positive.
- Balance sheet effect: G2 will become part of a larger, cash‑rich entity; the CVR (up to US$200 m) adds upside for shareholders while limiting downside risk.
- Risk considerations: Completion hinges on shareholder approval and court sanction; integration risk exists but synergies are quantified and largely cost‑avoidance.
Conclusion: The acquisition is a material, positive catalyst that fundamentally upgrades G2’s valuation outlook.
GTWO · Price
Company Overview
- Corporate name: G2 Goldfields Inc. (TSX: GTWO) – Canadian‑registered gold explorer focused on Guyana’s Oko‑Ghanie district.
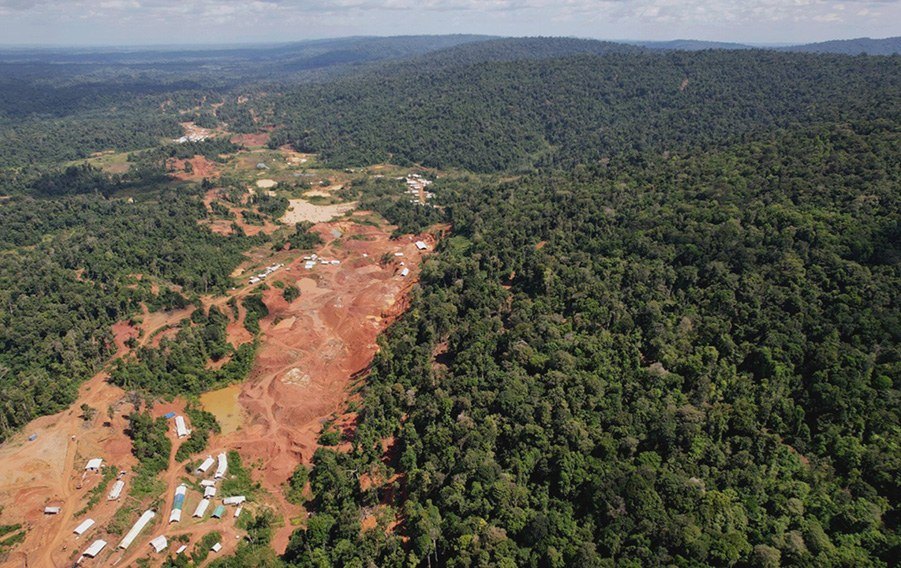
- Flagship asset: Oko‑Ghanie Gold Project (≈362 km² land package). Current resources: 7.0 Moz Measured & Indicated, 2.3 Moz Inferred; high‑grade underground zones (>10 g/t) and low‑cost open‑pit potential.
- Exploration pipeline: New Oko discovery (720 m strike, 350 m depth), Peters Mine (historic producer, early‑stage drilling), multiple near‑surface targets (Sands, Birdcage, RED Zone).
More from G2 Goldfields Inc.
Jul 29, 2026 · 09:34