Aston Bay Announces Pre-Feasibility Study Results and Maiden Mineral Reserve for the Storm Copper Project, Nunavut
Aston Bay’s Storm project pre-feasibility study shows a net present value of C$165 million, matching capital expenditure, with a 20% carried interest for C$30,000.
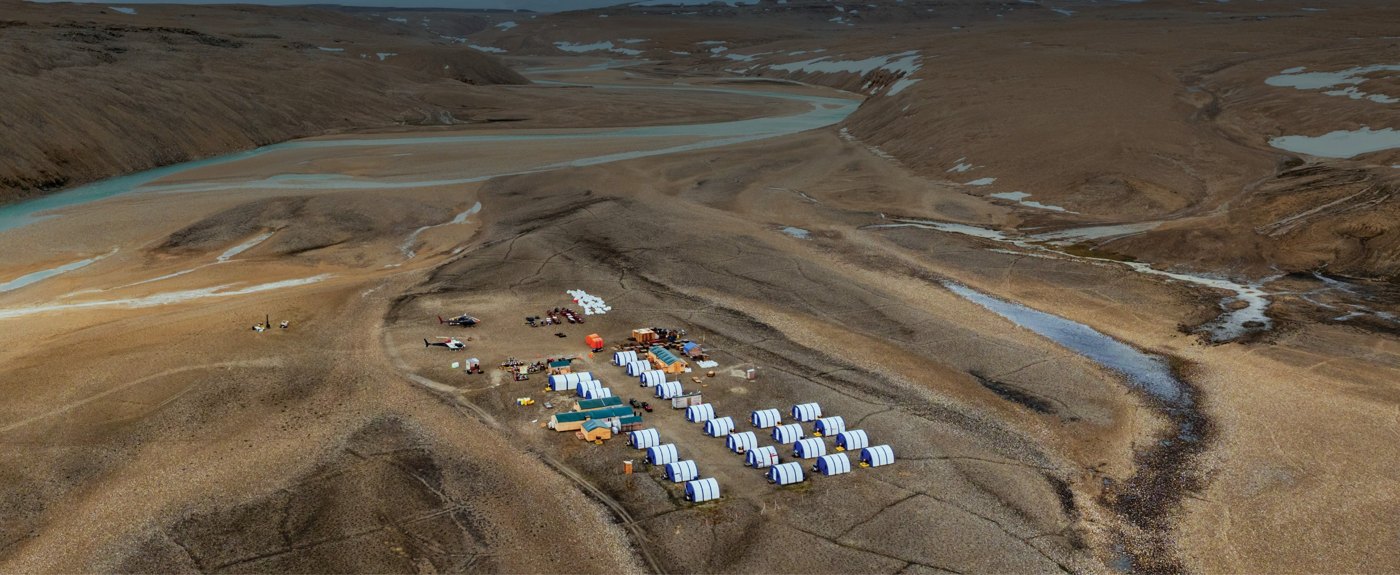
Aston Bay Holdings Ltd. (BAY) released the Pre-Feasibility Study and the first-ever Mineral Reserve Estimate for its Storm Copper Project on 10 November 2026. The study was prepared by Sacré-Davey for the 80/20 joint venture, in which American West Metals is the operator and Aston Bay holds a 20% interest, free-carried to a decision to mine.
Effective 1 November 2026, the project holds Probable Mineral Reserves of 12.58 million tonnes at 1.20% copper and 3.7 g/t silver, containing approximately 151,351 tonnes (334 million pounds) of copper and 1.50 million ounces of silver. There are no Proven Reserves or Measured Resources. The Probable Reserve captures approximately 89% of the copper contained in the Indicated Resource. The Mineral Resource estimate, effective 23 December 2025, includes an Indicated category of 14.11 million tonnes at 1.21% copper and 3.8 g/t silver (376 million pounds of copper, 1.71 million ounces of silver), and an Inferred category of 6.56 million tonnes at 1.01% copper (146 million pounds of copper, 0.68 million ounces of silver). All 6.56 million tonnes of Inferred material, including 2.35 million tonnes at Cirrus and Lightning Ridge at 1.98% copper, is treated as waste and contributes no tonnes, metal, or revenue.
On a 100% project basis, the base case assumes copper at US$5.30/lb, silver at US$50/oz, and an exchange rate of C$1.39/US$. This scenario yields an after-tax NPV7% of C$165.1 million (US$118.9 million), an after-tax IRR of 32.8%, and a payback period of 3.6 years. The pre-tax NPV7% is C$194.9 million. The after-tax IRR is slightly higher than the pre-tax IRR of 32.2% because pre-development capital of C$37.9 million is excluded from the NPV and IRR calculations, while its tax deductions and credits are included. The valuation date is 30 September 2029, meaning the NPV is struck three years forward.
Sensitivity analysis based on spot prices on 2 November 2026, when copper was US$6.53/lb, shows an after-tax NPV7% of C$323.8 million, an IRR of 55.1%, and a payback of 2.7 years. This sensitivity applies to the same reserve and mine plan and is not a forecast. Life-of-mine net revenue after treatment and refining charges is C$1,525.6 million, with LOM EBITDA at C$478.2 million, after-tax free cash flow at C$249.1 million, income taxes of C$86.6 million, and investment tax credits of C$36.2 million. Excluding all investment tax credits, whose eligibility is unconfirmed with tax authorities, the after-tax NPV7% falls to US$100.6 million and the IRR drops to 26.5%, representing a approximately 15% reduction in NPV.
Total capital expenditure is C$164.69 million, including C$23.66 million in contingency. This comprises pre-development capital of C$37.90 million (October 2028–March 2029), initial capital of C$112.58 million (October 2029–March 2030), and expansion capital of C$14.21 million (October 2031–March 2032). The estimate carries an AACE Class 4 accuracy of −30%/+50% with no escalation. At American West’s direction, sustaining capital, a water treatment plant, and owner’s costs beyond C$0.90 million are excluded. Closure and reclamation are covered by a C$9.70 million allowance provided by American West.
Life-of-mine site costs are C$72.00 per tonne processed, broken down into mining at C$47.70/t (including pre-stripping at a C$7.21/t mined contractor rate), processing at C$13.29/t, and G&A at C$11.01/t. The C1 cash cost is US$3.45/lb, and the AISC is US$3.73/lb for payable copper after silver credits. The strip ratio is 5.6:1, involving 83.28 million tonnes of total material and 70.70 million tonnes of waste. The total funding requirement is C$174.5 million (US$125.6 million), consisting of US$108.3 million in pre-development and initial capital, US$3.3 million in pre-production costs, and US$14.0 million in initial working capital.
The project features a contractor-operated open pit at Cyclone, Chinook, Corona, and Thunder. Mining is scheduled from January 2030 to July 2038 (8.6 years), with processing running from April 2030 to April 2040 (10.5 years to the last shipment). Dry sensor-based sorting plus jigging rejects approximately 79% of plant feed before grinding, meaning less than 10% of feed is milled and floated. The designed concentrate grade is 15% copper.
Production is estimated at 688,290 dry metric tonnes of concentrate at 14.97% copper and 45.8 g/t silver. Recovered metal includes 103,035 tonnes (227.2 million pounds) of copper and 1.01 million ounces of silver. Life-of-mine recoveries are 68.24% for copper and 67.52% for silver, with copper recovery dropping to 55.8% in years 10–11 due to
Aston Bay Holdings Ltd. (BAY) released its Preliminary Feasibility Study (PFS) on 10 November 2026, marking a formal economic assessment of the project. The study’s release came approximately six weeks after the company’s June 2026 guidance targeting a third-quarter 2026 completion, and significantly later than the "early 2026" timeline suggested in earlier investor presentations. The PFS establishes a maiden reserve and provides a formal economic baseline, representing a step up in project maturity from the earlier Preliminary Economic Assessment (PEA) era.
The company’s June 2026 guidance outlined a PFS in Q3 2026, an Ocean Partners facility for up to 80% of initial capital, 100% offtake, a 2028 regulatory approval target, and a project-wide structural and geochemical review. The PFS, the offtake agreement, and the indication of 80% debt financing appeared as promised, though the PFS slipped past the guided quarter. Permitting has moved backward in the sense that the Northwest Territories Environmental Impact Review Board (NIRB) process is now paused, awaiting further information.
Resource estimates have grown materially since the February 2025 investor presentation, which cited 8.2 million tonnes (Mt) Indicated at 1.47% copper and 3.3 Mt Inferred at 1.30% copper, containing approximately 164,000 tonnes of contained copper. The December 2025 estimate delivered 14.11 Mt Indicated at 1.21% copper plus 6.56 Mt Inferred at 1.01% copper, containing roughly 237,000 tonnes of contained copper. While tonnage has increased sharply, grade has decreased in both categories. The maiden Probable Reserve of 151,351 tonnes now represents approximately 92% of the entire previous resource.
Cost framing in the PFS differs from earlier narratives. The previous presentation cited operating costs of US$24.00 per tonne (mining US$5, processing US$7, G&A US$12) and a US$4.00 per pound copper assumption. The PFS carries a life-of-mine (LOM) site cost of C$72.00 per tonne processed (approximately US$52 per tonne at a C$1.39 exchange rate) and requires a US$5.30 per pound copper price for its base case. Scope differences, including contractor mining, pre-stripping, a staged plant, and different tonnage assumptions, prevent a clean like-for-like comparison, but the headline Net Present Value (NPV) rests on a materially higher cost base and copper price than the company's prior investor messaging.
The PFS introduces the first reserve tonnage and grade table, the first capital expenditure estimate of C$164.69 million, the first operating expenditure and C1/AISC figures, the first NPV, Internal Rate of Return (IRR), and payback period, the reserve-conversion ratio of 89%, the recovery profile of 68.2% (with 55.8% in the tail), and a 10.5-year production life. The study discloses the scale of exclusions, noting that sustaining capital, the water treatment plant, and the owner's mining team are outside the estimate. Pre-development capital is excluded from the NPV and IRR basis. These categories are standard for a Feasibility Study and typically increase the capital requirement.
On a 100% project basis, 20% of the after-tax NPV is approximately C$33 million, or C$0.13 per share, based on the 30 September 2029 valuation date. Discounted three years at 7%, this equates to approximately C$0.11 per share, compared to a C$0.06 share price. This valuation is conditional on Aston Bay funding its 20% share. The free-carry arrangement runs only to a decision to mine; from that point, Aston Bay must contribute approximately 20% of initial and expansion capital (C$25 million) or 20% of the full C$174.5 million funding requirement (C$35 million). With C$29,638 in cash at 30 June 2026, this is not a fundable obligation, making dilution of the interest—referencing a possible conversion to a 2% Net Smelter Return (NSR)—the realistic path. A 2% NSR on C$1,525.6 million of LOM net revenue represents approximately C$30.5 million nominal spread over 2030–2040, worth perhaps C$0.04–0.05 per share on rough discounting, which is essentially the current share price. The equity is thus priced between the funded-20% outcome and the residual-royalty outcome. The PFS does not resolve which scenario materialises; the debt commitment and Aston Bay’s own financing will determine the outcome.
The study reports a 32.8% after-tax IRR and a 3.6-year payback period. The maiden reserve converts most of the Indicated resource into mineable material, advancing de-risking without changing the ownership, funding, or permitting structure of the joint venture. No post-release share price exists in the provided data, as the series ends on 9 November 2026, so market reaction cannot be observed.
Aston Bay Holdings Ltd. (TSXV: BAY, OTCQB: ATBHF) is a Toronto-based, pre-revenue explorer and developer with no operating mine and no revenue. Its value is concentrated in two copper-silver assets in Nunavut.
The company’s flagship Storm Copper Project is located on Somerset Island in the Qikiqtaaluk Region, approximately 120 km south of Resolute. The project covers ~2,300 km² of claims and includes four deposits in the pre-feasibility study mine plan: Cyclone, which represents the bulk of the reserve; Chinook, the highest-grade deposit mined first; and Corona and Thunder. Aston Bay holds a 20% free-carried interest in an 80/20 joint venture with American West Metals (ASX: AW1), which serves as the operator. The 20% interest remains free-carried until a decision to mine is made following a bankable feasibility study.
The proposed processing flowsheet involves a conventional open pit mined by a contractor, followed by three-stage crushing. The process includes dry sensor-based sorting of the coarse fraction, wet jigging of the intermediate fraction, and flotation of the fines to produce a concentrate containing ~15% Cu and ~46 g/t Ag. The concentrate is exported during a five-week late-summer sealift. Infrastructure includes a marine laydown area on Aston Bay, all-weather roads, a 1,000 m airstrip, a fully catered fly-in/fly-out camp, on-site diesel generation, and a filtered tailings storage facility near the plant.
Recent exploration activity at Storm included a 17 November 2025 announcement of a new 4.1 km × 0.7 km Chevron soil anomaly exceeding 250 ppm Cu, along with Squall intercepts of 4.5 m @ 1.4% Cu / 2.6 g/t Ag. In June 2026, the company conducted a project-wide structural and geochemical review across a >110 km belt, targeting Chevron, Midway-Storm-Tornado (>20 km strike), and Tempest, where grab samples returned up to 38.2% Cu and 30.8% Zn.
The Epworth Copper-Silver Project is in the early exploration stage. The property covers 1,040.7 km² after staking 18.7 km² in August 2026, spanning ~94 km of strike. Aston Bay can earn an 80% interest from Emerald Geological Services by spending US$3 million over four years. The 2025 field program identified 17 new showings, including Greenback, which returned 29.2% Cu with 217 g/t Ag, and Expert, which returned 5.42% Cu with 1.89 g/t Au. Historic boulders on the property have returned up to 61.2% Cu and 5,600 g/t Ag.
In August 2026, two independent 3-D inversions (MVI and resistivity) over 126 km² converged on large near-surface targets. Ground geophysics and mapping are scheduled for fall 2026, with permits initiated and fuel and camp supplies pre-positioned for a 2027 drill program. There is currently no resource estimate or study for Epworth.
The company has terminated its Virginia projects due to challenging business conditions and FX costs, leaving it with Canada-only assets.