Imperial Reports Third Quarter 2026 Financial Results
Near-zero Q3 profit, Mount Polley guide cut 15%, cash cost swings to +$1.66/lb
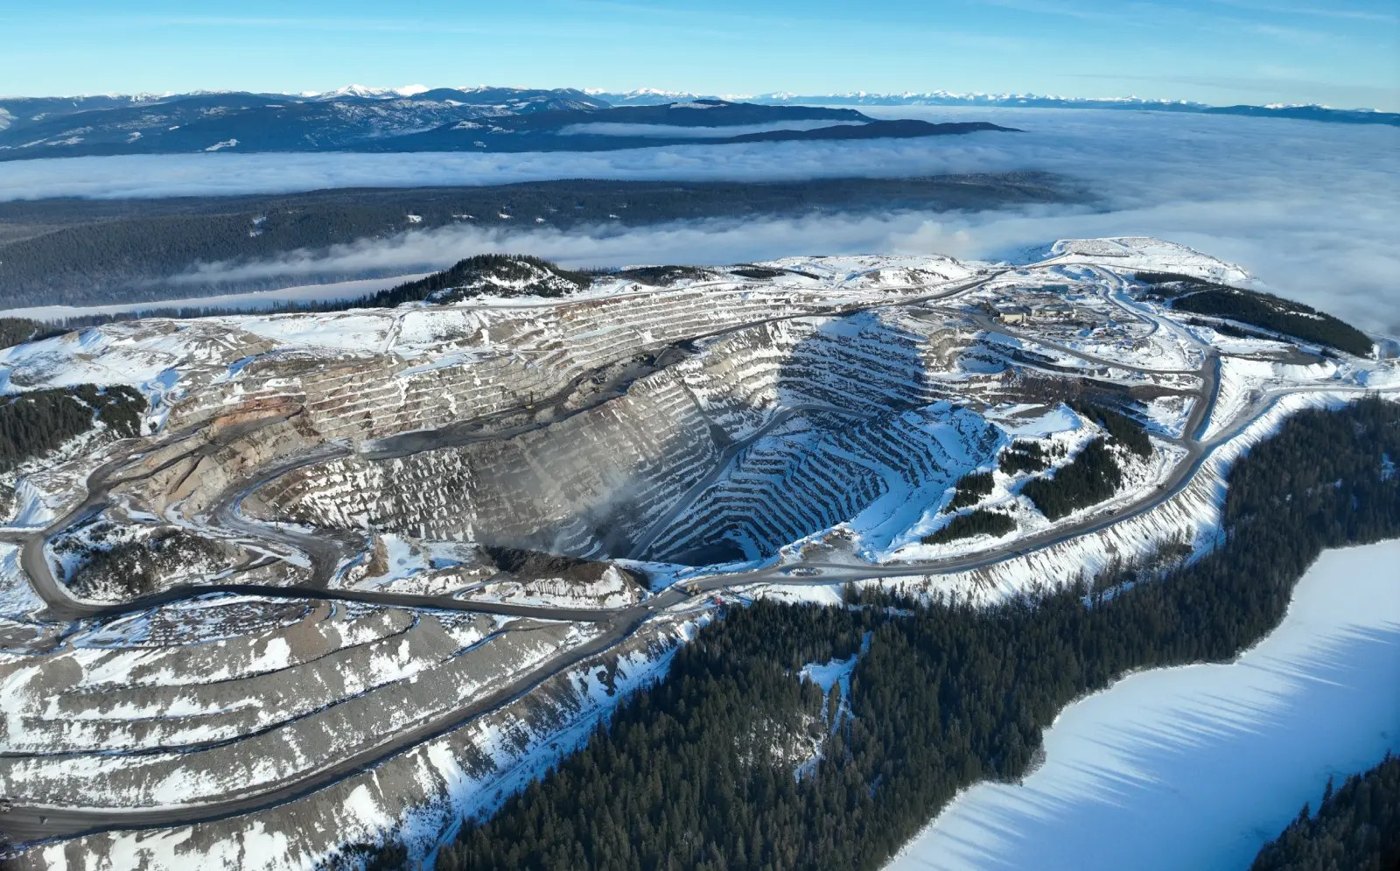
Imperial reported Q3 2026 (quarter ended September 30, 2026) results on November 5, 2026. This is the formal earnings book for a quarter whose production numbers and Mount Polley guidance cut were already pre-released on October 22, 2026. The incremental content in this release is the financial outcome, cash cost detail, and the disclosure of the Red Chris Block Cave capital framing.
The headline facts:
- Total revenue $149.9M vs $168.8M in Q3 2025 (-11.2%), despite copper averaging US$6.41/lb (vs US$4.44) and gold US$4,266/oz (vs US$3,454).
- Net income $1.2M ($0.01/share) vs $38.5M ($0.23/share) — a 97% decline.
- Income from mine operations $22.9M vs $72.1M — down $49.2M, a 68% collapse.
- Adjusted EBITDA $45.1M vs $92.5M (-51%); cash earnings $44.9M vs $90.4M (-50%).
- Consolidated production 8.536 Mlb Cu (Q3 2025: 13.925 Mlb, -38.7%) and 11,648 oz Au (15,783 oz, -26.2%).
- Composite cash cost US$1.66/lb Cu vs a negative US$0.07/lb in Q3 2025 — a US$1.73/lb deterioration in a single year.
- Mount Polley 2026 guidance formally restated at 16.0–18.0 Mlb Cu and 30,500–33,700 oz Au (was 19.0–21.0 Mlb and 40,000–44,000 oz).
- Red Chris Block Cave full funds investment decision now "expected in early 2027", construction 2027, commercial production 2033. Total development capital is still withheld pending an NI 43-101 technical report.
- Capex $64.6M vs cash earnings $44.9M.
Management's framing is the Block Cave ("starting to reveal a combination of scale, quality and growth potential") and the sequential improvement at Mount Polley (copper +21%, gold +16% vs Q2). Both are true. Neither is a cash flow fact. The release is silent on Q3 free cash flow, silent on cash at September 30, and silent on the size of Imperial's 30%-share funding obligation for the Block Cave.
The component of this release that is genuinely new is the earnings and cash cost outcome. Production and the Mount Polley cut were pre-announced on October 22, and the Block Cave FID slip to early 2027 was also in that release. The market has already marked the stock down roughly 20% from $7.55 (October 21) to $6.05 (November 5).
What is new and negative:
- Net income of $1.2M on $149.9M of revenue, with copper at US$6.41/lb and gold at US$4,266/oz. A copper-gold producer earning a 0.8% net margin at those prices is revealing a cost and grade problem, not a price problem.
- The composite cash cost swing from -US$0.07/lb to +US$1.66/lb. Mount Polley went from -US$1.26/lb to +US$0.83/lb; Red Chris (30% share) from US$1.39/lb to US$2.43/lb (+75%). The by-product credit engine that made Imperial a negative-cost copper producer has stalled because gold ounces fell 26% and gold grades fell (MP 0.19 vs 0.23 g/t; Red Chris 0.30 vs 0.56 g/t).
- Capex of $64.6M against cash earnings of $44.9M — the quarter was free-cash-flow negative by roughly $20M while total debt rose to $250.9M and the working capital deficiency stood at $82.9M.
- An effective tax rate of roughly 90% (tax $10.3M against pre-tax income implied at ~$11.5M), which fully explains why mine operating income of $22.9M became $1.2M of net income. Even if this is a timing/valuation-allowance artifact, it is not explained in the release.
- The revised Mount Polley guidance itself requires Q4 copper of 5.8 Mlb (+41% vs Q3's 4.104 Mlb) and gold of 11,000 oz (+39% vs 7,931 oz). Imperial is asking the market to believe a second-half ramp for the second consecutive quarter.
Offsetting, and already known: Red Chris is locked in for its 2026 guide; the throughput fix at Mount Polley is real (22,875 tpd in August/September vs 17,260 tpd January–July); the $500M federal contribution is progressing; the Boundary pit (592,039 t at 0.65% Cu, 0.58 g/t Au) is being developed ahead of schedule.
Net: the release books a near-total earnings wipeout and a full-year guidance miss at the company's 100%-owned mine, and confirms that the transformational Block Cave decision has slipped a year while its capital cost remains undisclosed. That is material and negative.
Imperial Metals is a Vancouver-based copper-gold producer and developer listed on the TSX (III).
- Mount Polley (100%, operator). Open-pit copper-gold mine in central BC. The largest single contributor to consolidated copper. Currently in a grade trough as the Springer Pit Phase 5 pushback is developed; processing a 46% stockpile feed. TSF permitted to 987 m, supporting mining through 2034. This is the asset that missed guidance.
- Red Chris (30%, Newmont 70% and operator). High-grade open-pit copper-gold mine in the Golden Triangle, BC, in transition to block caving. The Block Cave is the company's principal value driver: >1.8 Blb Cu and 3.0 Moz Au over an initial 13-year cave life, ramp to 145–187 Mlb Cu and 275,000–325,000 oz Au per year in 2035–2040, up to 70 years of mine life, first production targeted 2033.
- Huckleberry (100%). On care and maintenance since August 2016. 22 holes drilled in Q1 2026 all intersected Cu-Mo-Ag-Au; reopening plan targeted end of 2026. Idle cost $1.9M/quarter. Optionality, not an asset today.
- Greenfield portfolio. The release's boilerplate states 21 greenfield exploration properties in BC; the July 2, 2026 release stated 23. Minor, but a reminder to check disclosure consistency. Porcher Island (100%) is the most actively promoted, with an ore-sorting/direct-shipping concept under study.