Canagold Drills 69.8 g/t Gold (Au) over 2.6m; Within 4.64m Averaging 52.8 g/t Au and 0.83% Antimony (Sb)
Canagold reports 52.8 g/t gold repeats in its latest three holes while antimony grades have vanished from the results.
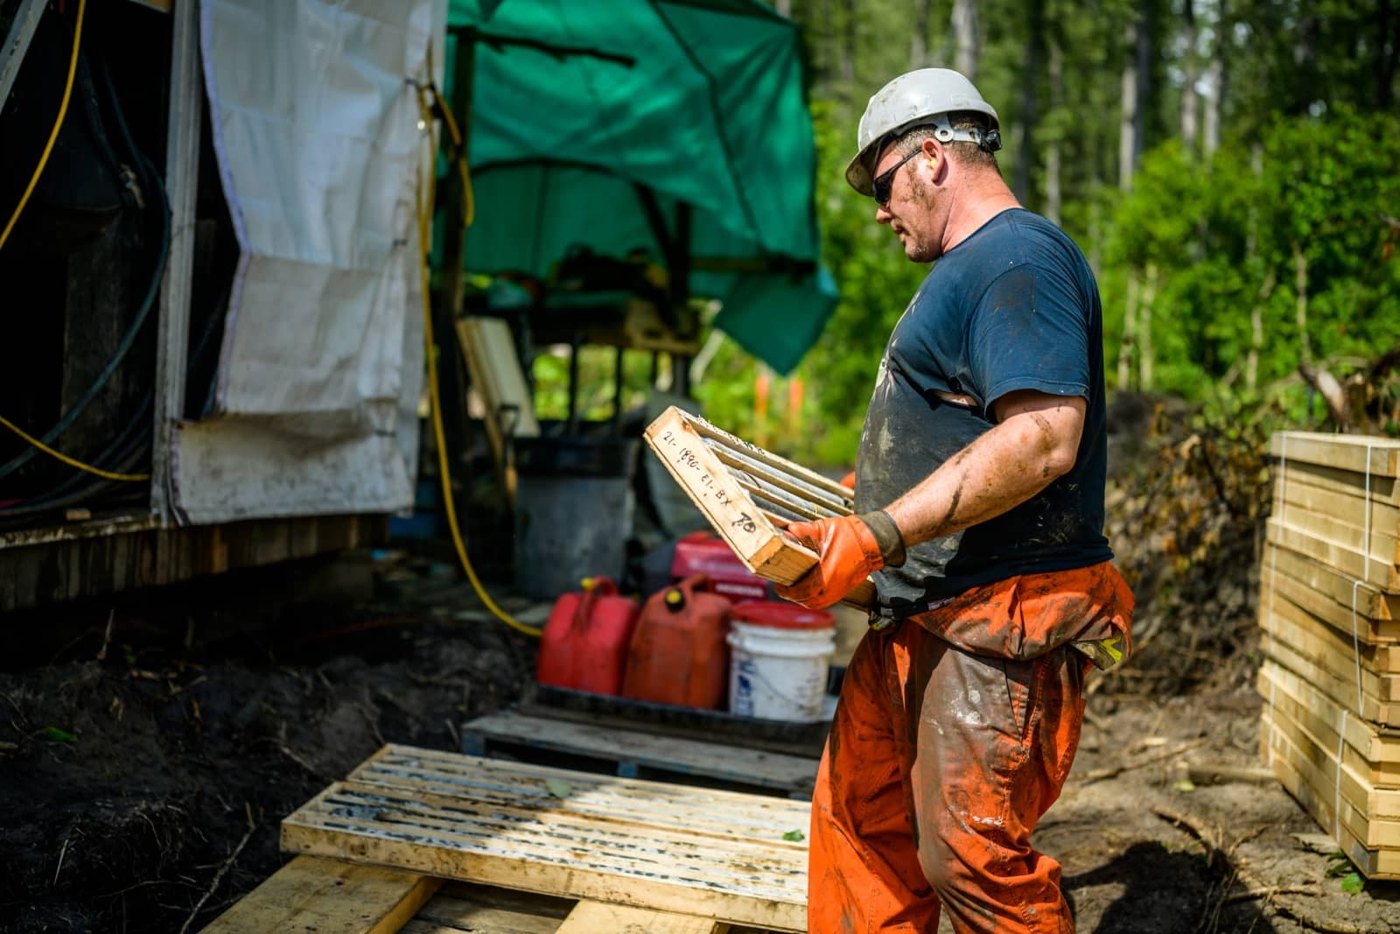
Canagold Resources Ltd. (CCM) has released the third tranche of assay results from its completed 14-hole, 7,277-meter "resource infill and expansion" program at the 100%-owned New Polaris gold-antimony project in northwestern BC. The company reported results for three holes: NP26-07, NP26-08, and NP26-09.
Key intercepts include: - NP26-08: 4.64 m core length at 52.8 g/t Au and 0.83% Sb from 503.00 m downhole, consisting of 2.64 m at 69.8 g/t Au / 0.13% Sb (from 503.00 m) and 2.00 m at 30.4 g/t Au / 1.75% Sb (from 505.64 m). - NP26-07: 7.33 m at 24.6 g/t Au / 0.01% Sb from 458.52 m, including 1.18 m at 70.4 g/t Au. - NP26-07 (upper zone): 10.00 m at 8.04 g/t Au / 0.09% Sb from 294.00 m. - NP26-09: 6.92 m at 6.50 g/t Au / 0.01% Sb from 231.08 m.
The company stated that all intercepts are core length and noted that "insufficient drilling and modelling has taken place to determine the true dip and strike orientation of the veins being intercepted." No cutoff grade was disclosed.
Collar data shows that NP26-07 and NP26-09 were collared from the identical coordinate (579322E / 6507110N, elevation 30.5 m), fanned at azimuth 138°/-89.7° and 22.7°/-82.1°. NP26-08 is located at 579330E / 6507077N (azimuth 86.3°, dip -82.0°), roughly 34 m away from the other two.
Quality assurance and quality control procedures involved half-core saw-cut sampling processed by MSA Labs in Terrace with assays conducted in Langley. The protocol included CRM standards, blanks, and duplicates at one in ten intervals, with the ISO 17025/9001 lab maintaining a security-tagged chain of custody. Garry Biles, P.Eng., President & COO, serves as the Qualified Person.
CEO Garry Biles stated that most high-grade intervals "are not included in the current mineral resource model or mine plan," suggesting resource expansion and that the "scale and extent… may be substantially greater than previously understood."
Canagold Resources Ltd. (CCM) is a post-PFS, pre-construction developer with an equity value of roughly C$137-million at the latest close. The company’s feasibility study outlines a C$793-million after-tax NPV, a 30.9-47.3% after-tax IRR depending on the deck cited, US$181-million in pre-production capex, an 8.3-year mine life, and a 1.7-year payback period. The binding constraints on the share price remain financing, permitting, and the construction decision, rather than drill metres. High-grade infill and expansion intercepts do not move net asset value until they are converted into resource, reserve, and mine plan.
The purpose of the recent drilling was explicitly resource infill and expansion. On that basis, 52.8 g/t over 4.64 m and 24.6 g/t over 7.33 m at an underground gold mine are at or above any plausible plan grade, and three of the four reported intervals fall into the good-to-excellent band for the deposit type.
The anchor result is the 1-Oct-2026 release (NP26-01: 13.20 m at 19.38 g/t Au and 3.83% Sb = 256 g·m Au, 50.6 %·m Sb). The stock closed at $0.71 on 1 October, $0.75 on 6 October, and $0.64 on 21 October, sitting approximately 17% below its 18-September high of $0.77. The market faded the anchor rather than paying up for repetition, so it does not set a bar today's release must clear. The new best hole is not materially better in grade-and-width substance than what the company already demonstrated on 1 October; it is roughly equal on gold gram-metres (245 vs 256) and drastically weaker on antimony (3.85 vs 50.6 %·m).
The release represents a genuine, creditable, high-grade gold confirmation at a project where high grades are expected. There is zero antimony support for the antimony-growth narrative that has been the marketing centrepiece since February, no true width, no cutoff, no resource update, and no change to the permitting and financing story that actually drives this equity. If the remaining six holes plus a resource update add high-grade tonnes at these grades and widths, or if the antimony-bearing parts of the system turn out to be more extensive than the Oct 1 holes suggested, the cumulative programme could matter. This release alone does not.
Canagold Resources Ltd. (TSX: CCM; OTCQB: CRCUF; FSE: CANA), a Vancouver-based pre-revenue company, holds the 100%-owned New Polaris gold-antimony project in northwestern British Columbia, located approximately 100 km south of Atlin, BC, and 60 km northeast of Juneau, Alaska. The company completed a feasibility study for the project in July 2025. Subsequent regulatory and strategic milestones include filing an environmental assessment application with the BC Environmental Assessment Office in March and April 2026, designating New Polaris as a BC priority major project in May 2026, adding the asset to Canada's Critical Metals Advanced Projects Map in March 2026, and including it in the Canada Investment Summit Prospectus in September 2026. While the company states it aims to acquire advanced projects, no additional assets are described in the provided materials.
The feasibility study cited in prior releases and the MD&A reports an after-tax net present value (NPV) of C$793-million, a 47.3% after-tax internal rate of return (IRR), and a payback period of 1.7 years. The study indicates an NPV-to-initial capital expenditure ratio of 3.2x, US$181-million in pre-production capital expenditure, an 8.3-year mine life, and after-tax free cash flow of US$1,145-million. These figures, which vary by gold-price deck and study date across sources, are prior-period statements and were not disclosed in today’s release.
Regarding ownership and balance sheet, Sun Valley Investments AG held 49.75% of shares outstanding following the September 2026 placement, which resulted in 113,495,947 shares held by the investor. Total shares outstanding were 213,949,766 as at 30 June 2026. According to provided financials, which are reported in USD, total equity stands at US$38.6-million with a book value of approximately US$0.18 per share. Revenue is nil, with a first-half 2026 net loss of US$428,000 and negative operating cash flow of US$684,000. The company holds US$2.64-million in cash and a working-capital surplus of US$1.64-million, all based on prior-period context from the H1-2026 filing.