LUCA MINING ANNOUNCES BINDING EQUITY COMMITMENT FROM GOLDGROUP MINING INC.
Luca takes a 19.9% stake as Trafigura’s backstop exits, marking a dilutive transaction rather than a validation of the project.
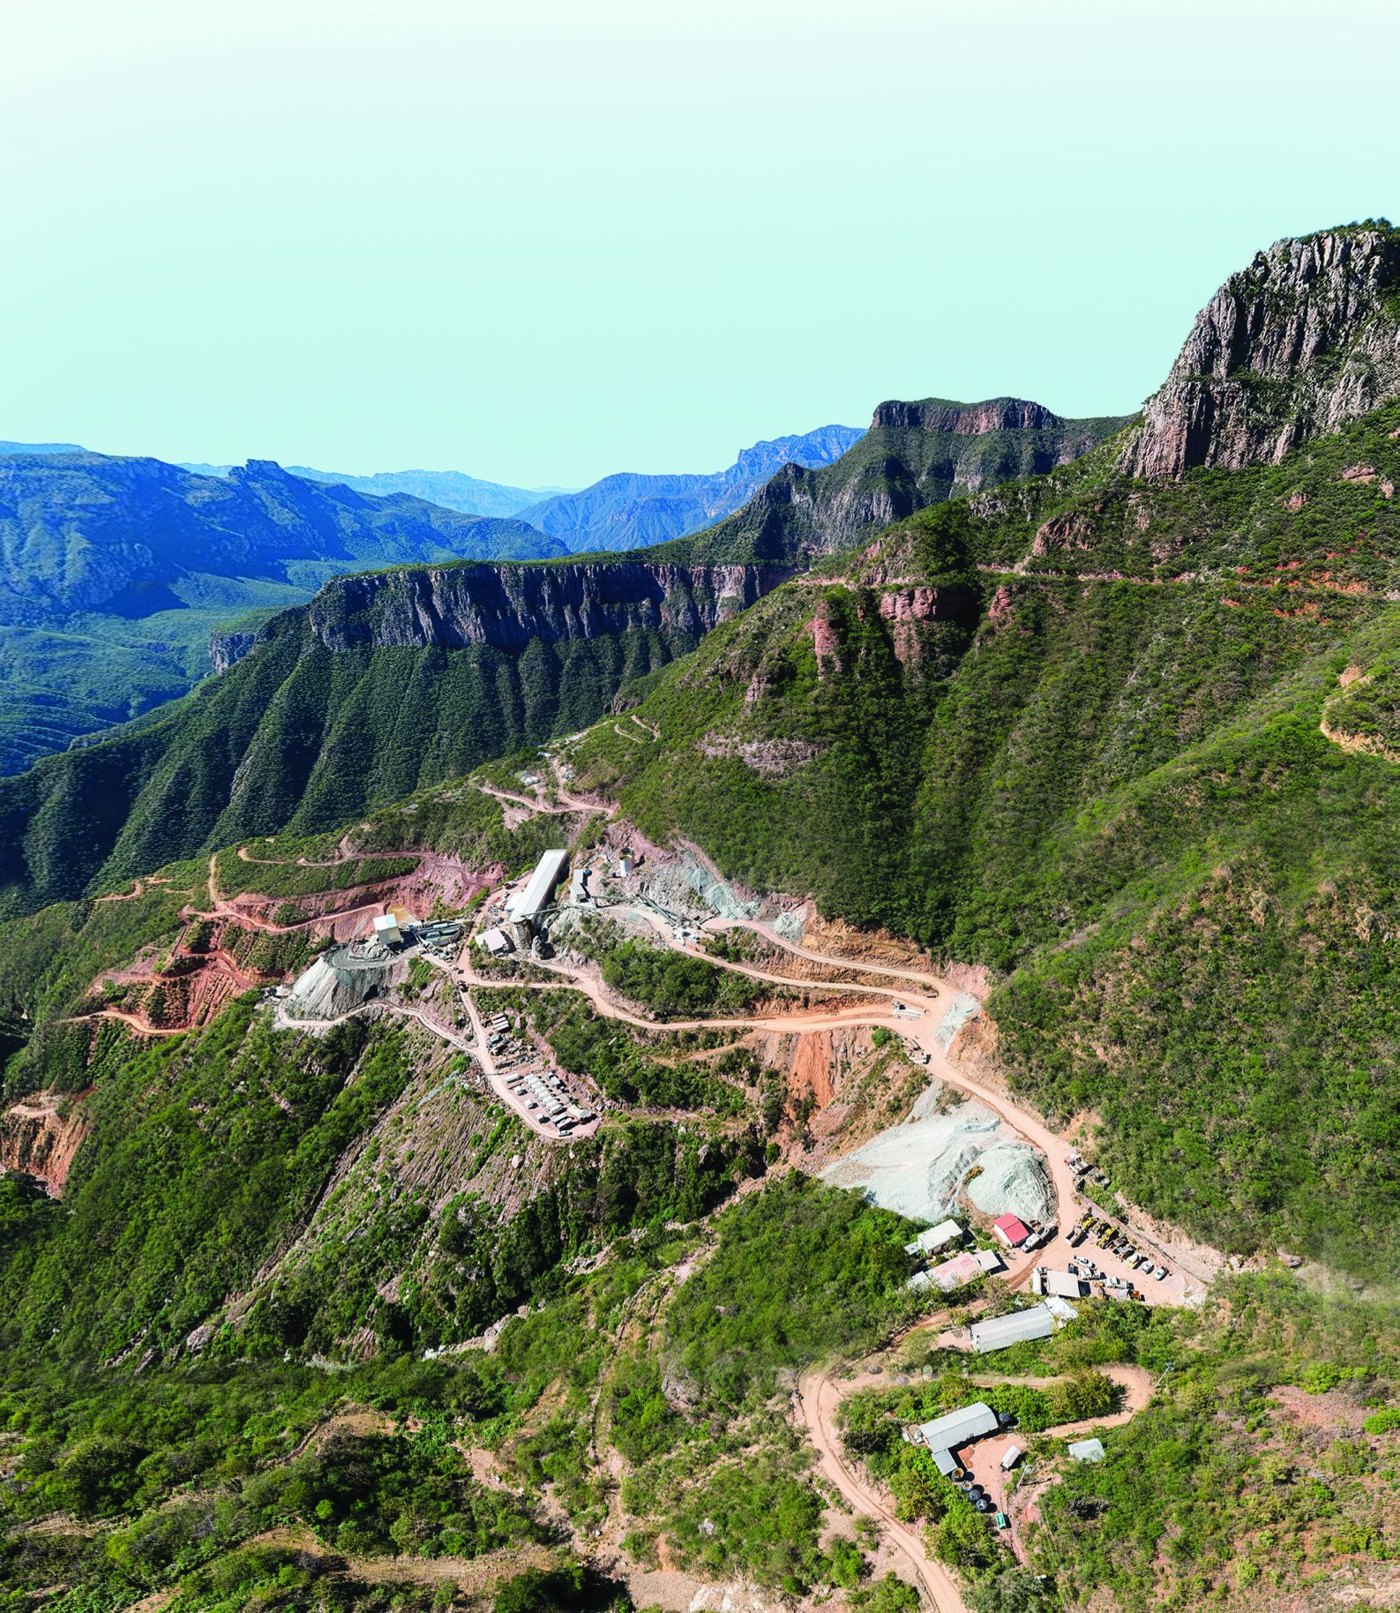
Luca Mining Corp. (LUCA) announced a binding equity commitment from Goldgroup Mining Inc. for gross proceeds of US$75 million into its previously announced $110 million brokered private placement of subscription receipts, originally announced on September 21, 2026. The commitment represents a 19.9% ownership interest in Luca on a non-diluted pro forma basis after giving effect to the Cozamin transaction, or "such other amount" representing that percentage.
The release states that Trafigura Pte Ltd. and Goldgroup have agreed that the Financing Commitment replaces the $75 million equity backstop previously provided by Trafigura. The total offering size, the C$1.00 subscription receipt price, and the use of proceeds remain unchanged. Subscription receipts convert into one Luca share on the earlier of satisfaction of escrow release conditions, including completion of the Cozamin acquisition and all regulatory approvals, or Goldgroup's election to convert, provided conversion does not push Goldgroup above 19.9% or trigger a shareholder approval requirement.
Luca granted investor rights for so long as Goldgroup holds at least 10% of outstanding shares, including two board nominees, equity participation rights, and anti-dilution rights. Closing of the offering and the grant of investor rights remain subject to TSXV approval.
Signed by CEO Dan Barnholden, the release re-states, but does not update, the Cozamin (acquired from Capstone for $290M upfront plus up to $95M deferred/contingent) and El Barqueño (from Agnico Eagle) transactions, both targeted to close in Q4 2026. The release does not provide information on Goldgroup's financial capacity or funding source for the US$75 million, nor does it indicate any change to deal size, price, or economics. It also does not mention any changes to the $40 million concurrent private placement (Wheaton/Taurus), the $125 million senior secured facility, or the $25 million incremental Wheaton silver stream.
Luca Mining Corp. (LUCA) has executed a financing-counterparty substitution rather than raising new capital. The total offering remains $110 million, with Goldgroup’s US$75 million investment occupying the slot previously backstopped by Trafigura. The terms of the Cozamin purchase price, the equity price of C$1.00, the debt package, and the streams remain unchanged.
The primary updates involve the identity of the 19.9% shareholder, the grant of two board seats, equity participation, and anti-dilution rights, and the removal of Trafigura from the capital structure. Goldgroup is a junior Mexican-focused precious metals producer, not a marquee strategic name, and the funds are not incremental to the previously announced raise.
The substitution presents mixed implications regarding counterparty quality. Trafigura is a major global trading house, whereas Goldgroup’s capacity to fund US$75 million is not disclosed in the release. A binding commitment is only as strong as the counterparty’s ability to fund it; if the commitment fails, escrow release conditions may not be met, placing the Cozamin acquisition at risk. Conversely, the arrangement offers governance stability. A firm 19.9% holder with two board seats represents a party with stated skin in the game, and the conversion mechanics allow Goldgroup to convert before closing if it elects to do so.
A governance concern arises from the 19.9% cap, which is explicitly structured so that Luca does not have to obtain shareholder approval for the Brokered Offering. Existing shareholders will therefore absorb roughly an 82% increase in share count without a vote.
Market reaction to the broader Cozamin announcement was muted. The stock moved from a close of C$1.04 on September 18 to C$1.19 on September 22, a gain of approximately 14%, before fading to C$1.13 by September 25. Given that a transformational acquisition, a $300 million financing, and a new strategic shareholder produced only a mid-teens percentage move that half-unwound within three sessions, the market appears to be discounting the story heavily. This follow-on detail is unlikely to move the stock more than a few percent on its own.
Luca Mining Corp. (TSXV: LUCA; OTCQX: LUCMF; Frankfurt: Z68) is a Vancouver-headquartered Canadian company operating two wholly owned underground mines in Mexico's Sierra Madre belt. Its Campo Morado mine in Guerrero State covers 121 km² and is an underground VMS polymetallic operation producing zinc, copper, gold, silver, and lead. Throughput has increased from under 1,200 tpd in late 2023 to over 2,000 tpd, approaching the plant’s capacity of 2,400 tpd, while copper recovery has risen from 60% to 80%. A two-phase Campo Morado Expansion study, involving bulk sulphide flotation with ultrafine regrinding followed by cyanide leach of pyrite concentrate to doré, is currently with Ausenco, targeting an NI 43-101 report in H2 2026.
The company’s Tahuehueto mine in Durango State covers more than 100 km². This newly constructed underground epithermal gold-silver mine declared commercial production in March 2025, with a copper concentrate circuit added and a copper-lead separation circuit commissioned.
Luca Mining is also pursuing pending acquisitions scheduled for Q4 2026, subject to approval. These include Cozamin in Zacatecas, an underground copper-silver-zinc-lead mine with 20 years of continuous production and a capacity of up to 4,400 tpd (averaging 3,670 tpd over five years), where paste backfill and filtered tailings were completed in 2022. Additionally, the company is acquiring El Barqueño in Jalisco, a property spanning more than 32,000 ha. Acquired from Agnico Eagle, this exploration and development property is currently unpermitted for exploration.
An investor deck provided by the company contains internal inconsistencies and stale data. It lists Dan Barnholden as "VP Financial," whereas every news release names him CEO. It identifies Adam Melnyk as COO, despite Nick Shakesby being appointed COO effective April 2026. The deck dates cash holdings of US$24.7 million to "Dec 31, 2024," while the FY2024 close per the April 2026 release was US$10.2 million. Its C$300 million market capitalization is derived from 275.6 million shares, implying a price of roughly C$1.09 consistent with a CAD price series, but the deck cannot be relied upon for current corporate data.