Mako Mining Completes Acquisition of Mt. Hamilton in Nevada
Mako transforms into a multi-asset producer through strategic Nevada acquisition and debt-free operations.
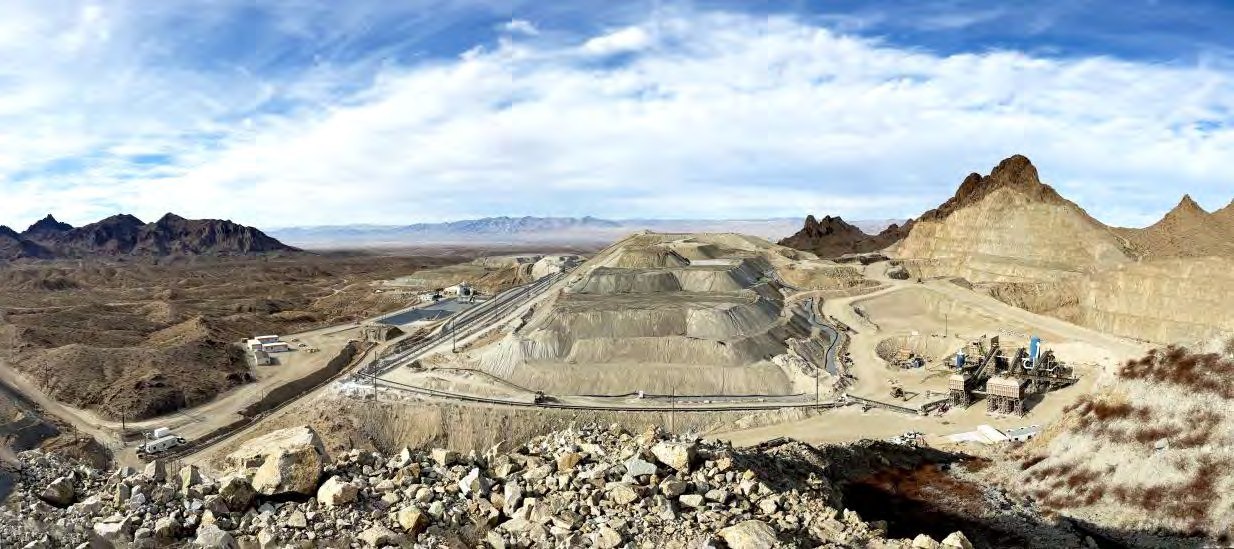
The most recent news (March 24, 2026) confirms the completion of the 100% acquisition of the Mt. Hamilton project in Nevada from Sailfish Royalty Corp. The US$40 million purchase price was satisfied via a gold stream agreement rather than equity dilution. For the first 60 months, Mako will deliver 341.7 oz of gold per month to Sailfish at 20% of the LBMA PM Fix price (subject to a US$2,700 floor and US$3,700 cap). This follows the March 4, 2026, shareholder approval where 99.99% of votes favored the deal. Notably, the deal was restructured in February 2026 to remove a 2% NSR royalty on all minerals to preserve flexibility for a potential tungsten-copper-molybdenum target on the property, which is now viewed as a strategic critical minerals asset.
The impact is Routine - Positive. While the acquisition is strategically significant, it was widely expected following the definitive agreement in November 2025 and the overwhelming shareholder approval earlier in March 2026. - Financial De-risking: The use of a gold stream instead of equity prevents dilution for existing shareholders. Mako’s strong cash position (US$78.1M as of Dec 31, 2025) and record Q4 revenue (US$50M) provide a robust cushion for the US$40M obligation. - Operational Diversification: Mako has successfully transitioned from a single-asset developer in Nicaragua to a three-mine producer/developer with assets in Nicaragua (San Albino), Arizona (Moss Mine), and Nevada (Mt. Hamilton), plus a development project in Guyana (Eagle Mountain). - Strategic Optionality: By removing the NSR on non-gold minerals, Mako retains 100% exposure to the tungsten target, aligning with new U.S. critical mineral policies.
Mako Mining is a gold producer focused on high-margin operations. - Flagship Project: San Albino (Nicaragua) is a high-grade open-pit mine that achieved commercial production in 2021. It remains the primary cash flow engine, with grades exceeding 10 g/t Au. - Secondary Assets: The Moss Mine (Arizona) was acquired in early 2025 and is currently ramping up to steady-state production. Mt. Hamilton (Nevada) is the newest addition, fully permitted for gold/silver heap leach with significant tungsten potential.