i-80 Gold Closes $250 Million Royalty Financing with Franco-Nevada and Completes Retirement of Certain Legacy Debt Obligations
i-80 Gold Secures $500M Lifeline to Bridge the Gap to Owner-Operator Status
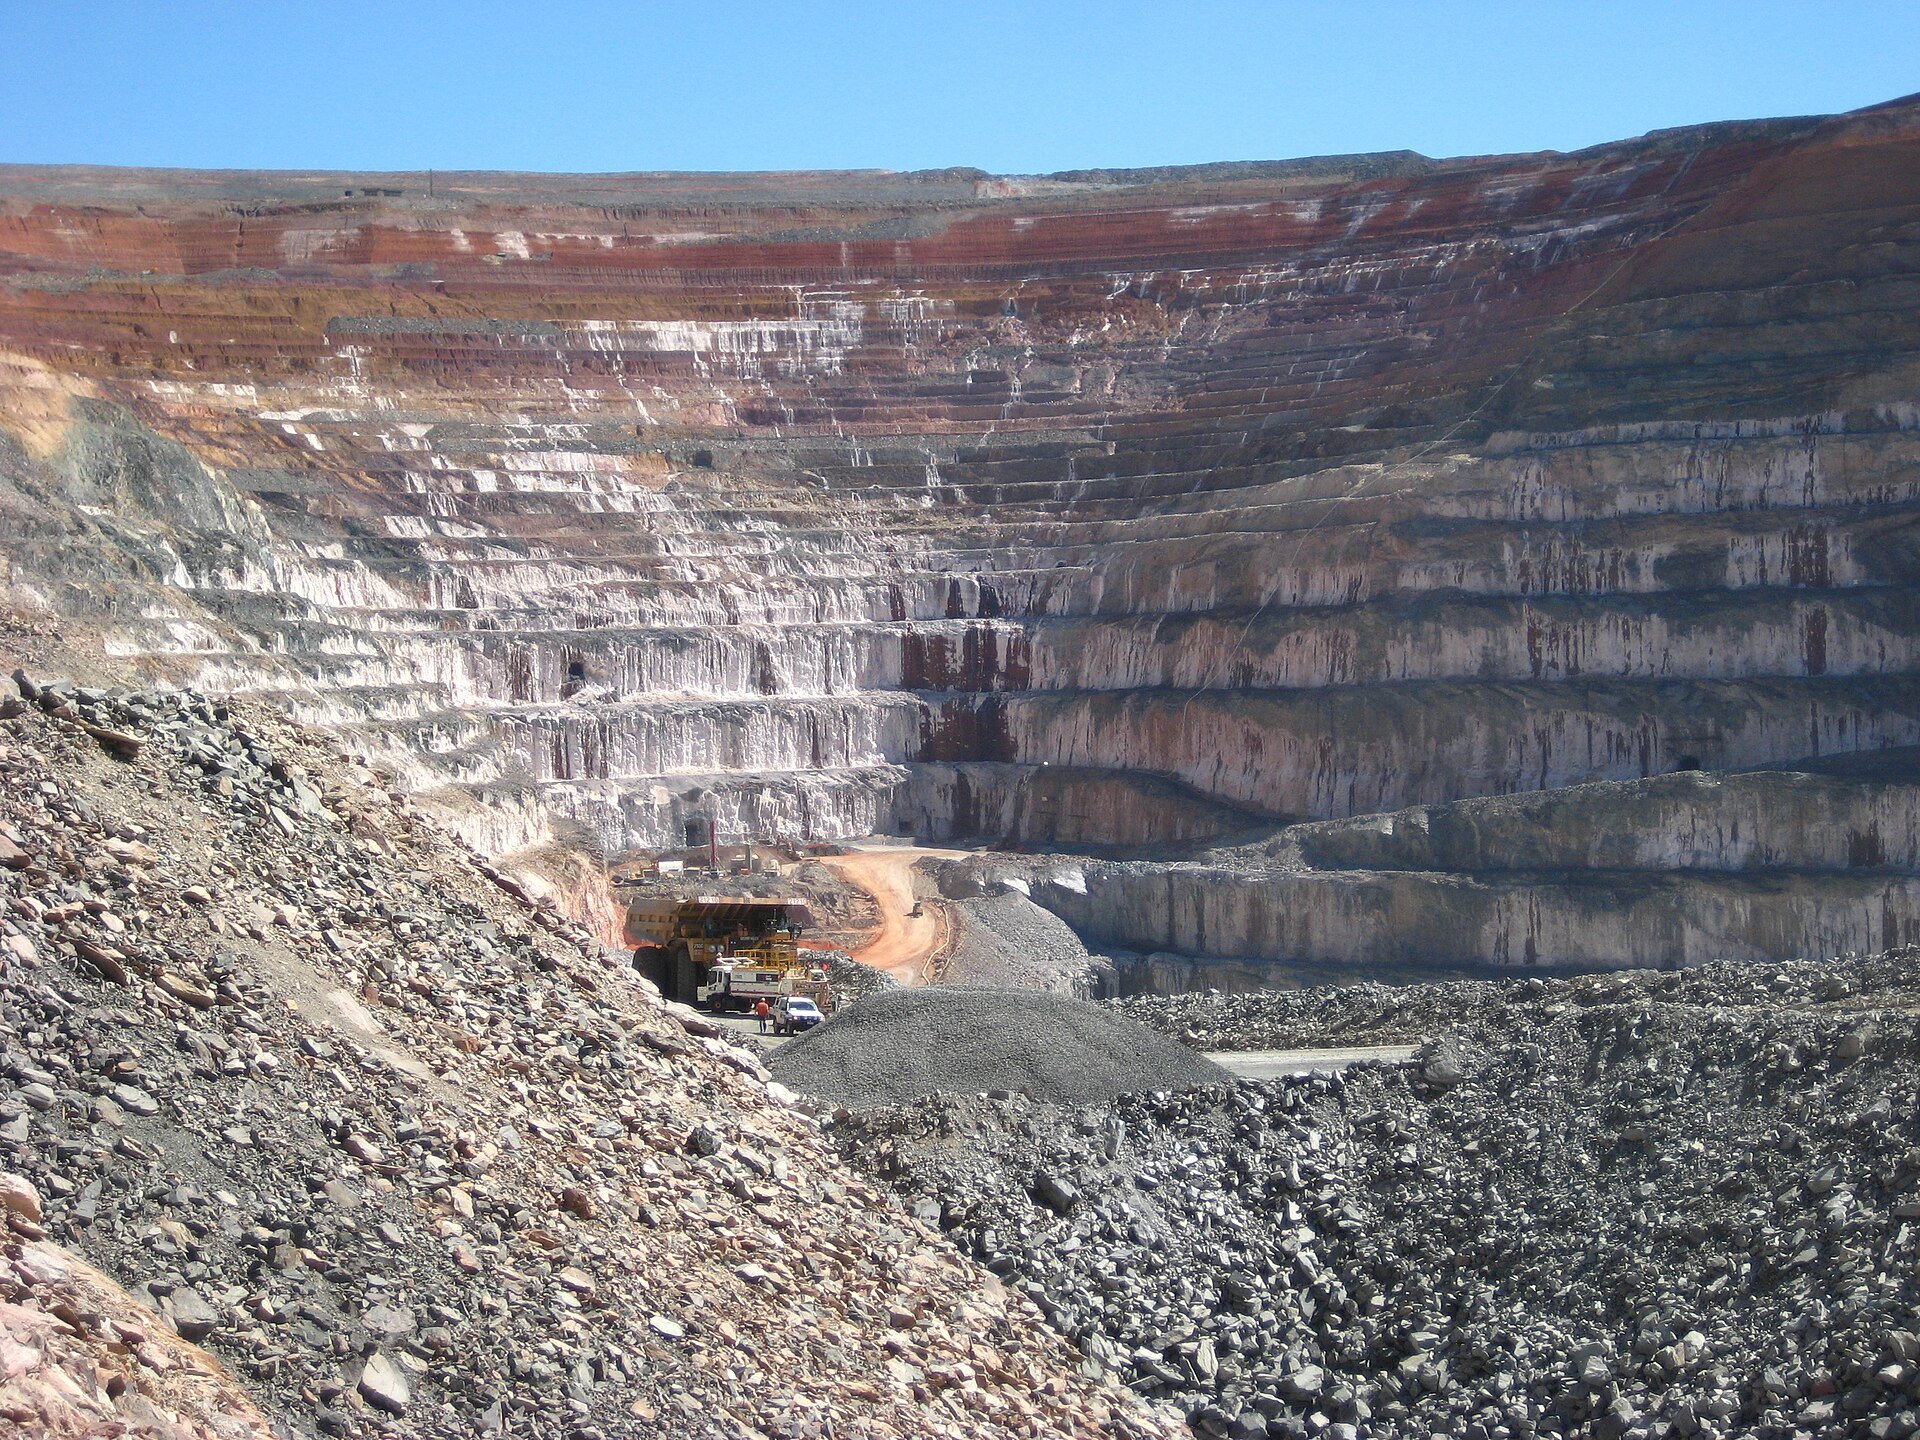
The most recent news (March 16, 2026) confirms the closing of a $250 million royalty financing with Franco-Nevada. This is part of a larger $500 million package that includes a $250 million gold prepayment facility with National Bank of Canada and Macquarie. Crucially, i-80 used $165 million of these proceeds to immediately extinguish legacy debt, including $92 million to Orion Mine Finance and $73 million in convertible debentures. The remaining funds are earmarked for the $430 million refurbishment of the Lone Tree autoclave and the advancement of the Archimedes and Mineral Point projects.
- Financial Risk Mitigation: This is a material positive for survival. The company was facing a liquidity crunch with high interest expenses and looming debt maturities. Extinguishing the Orion debt and convertible debentures removes immediate default risks.
- Cost of Capital: While the financing provides necessary cash, the cost is high. The Franco-Nevada royalty starts at 1.5% but doubles to 3.0% in 2031 across the entire portfolio. This creates a permanent headwind for future margins.
- Operational Shift: The funding allows the company to move from expensive third-party toll milling ($275-$280/tonne) to an owner-operator model at Lone Tree, which management expects will increase margins by $1,000-$1,500 per ounce.
- Dilution: The debt retirement involved issuing 11.1 million shares, and the company is relying on the exercise of 185.5 million warrants (at $0.70) to reach its $1 billion recapitalization goal.
i-80 Gold is a Nevada-focused developer aiming to become a mid-tier producer (600koz/year). - Flagship Project: The Lone Tree Autoclave. It is the "hub" that makes the "spokes" (Granite Creek, Archimedes, Cove) economically viable by allowing the company to process refractory ore in-house rather than paying competitors for toll milling. - Key Producing Asset: Granite Creek Underground (currently ramping up).