Technical Study
Borealis Files NI 43-101 Technical Report for the Sandman Gold Project
BOGO · Price
Executive Summary
- Borealis Mining filed a NI 43‑101 technical report on SEDAR+ that supports its previously announced PEA for the Sandman Gold project.
- The PEA shows strong economics: post‑tax NPV of ~US$203 M (6% discount), IRR ≈ 105%, payback ≈ 1.1 years, and average annual cash flow of ~US$36 M.
- Sensitivity analysis indicates that at a gold price of US$4,550/oz the project’s post‑tax NPV could rise to ~US$696 M with an IRR of ≈ 289%.
Key Details
- Technical Report: “NI 43‑101 Technical Report – Sandman Gold Property, Nevada, USA – Preliminary Economic Assessment”; effective date Jan 5 2026, dated Feb 19 2026; available on SEDAR+ and company website.
- PEA Highlights (Base Case, $2,600/oz Au):
- Net Present Value (6% discount, post‑tax): ~US$203 M
- Internal Rate of Return (post‑tax): ~105%
- Payback period: ~1.1 years from first production
- Undiscounted cumulative cash flow: ~US$290 M
- Average annual cash flow: ~US$36 M
- All‑in sustaining cost: ~US$1,823/oz Au
- Initial capital requirement: ~US$36 M
- Total life‑of‑mine (LOM) capital: ~US$57 M
- LOM gold production: ~340,000 oz over ≈9 years (≈38,000 oz/year)
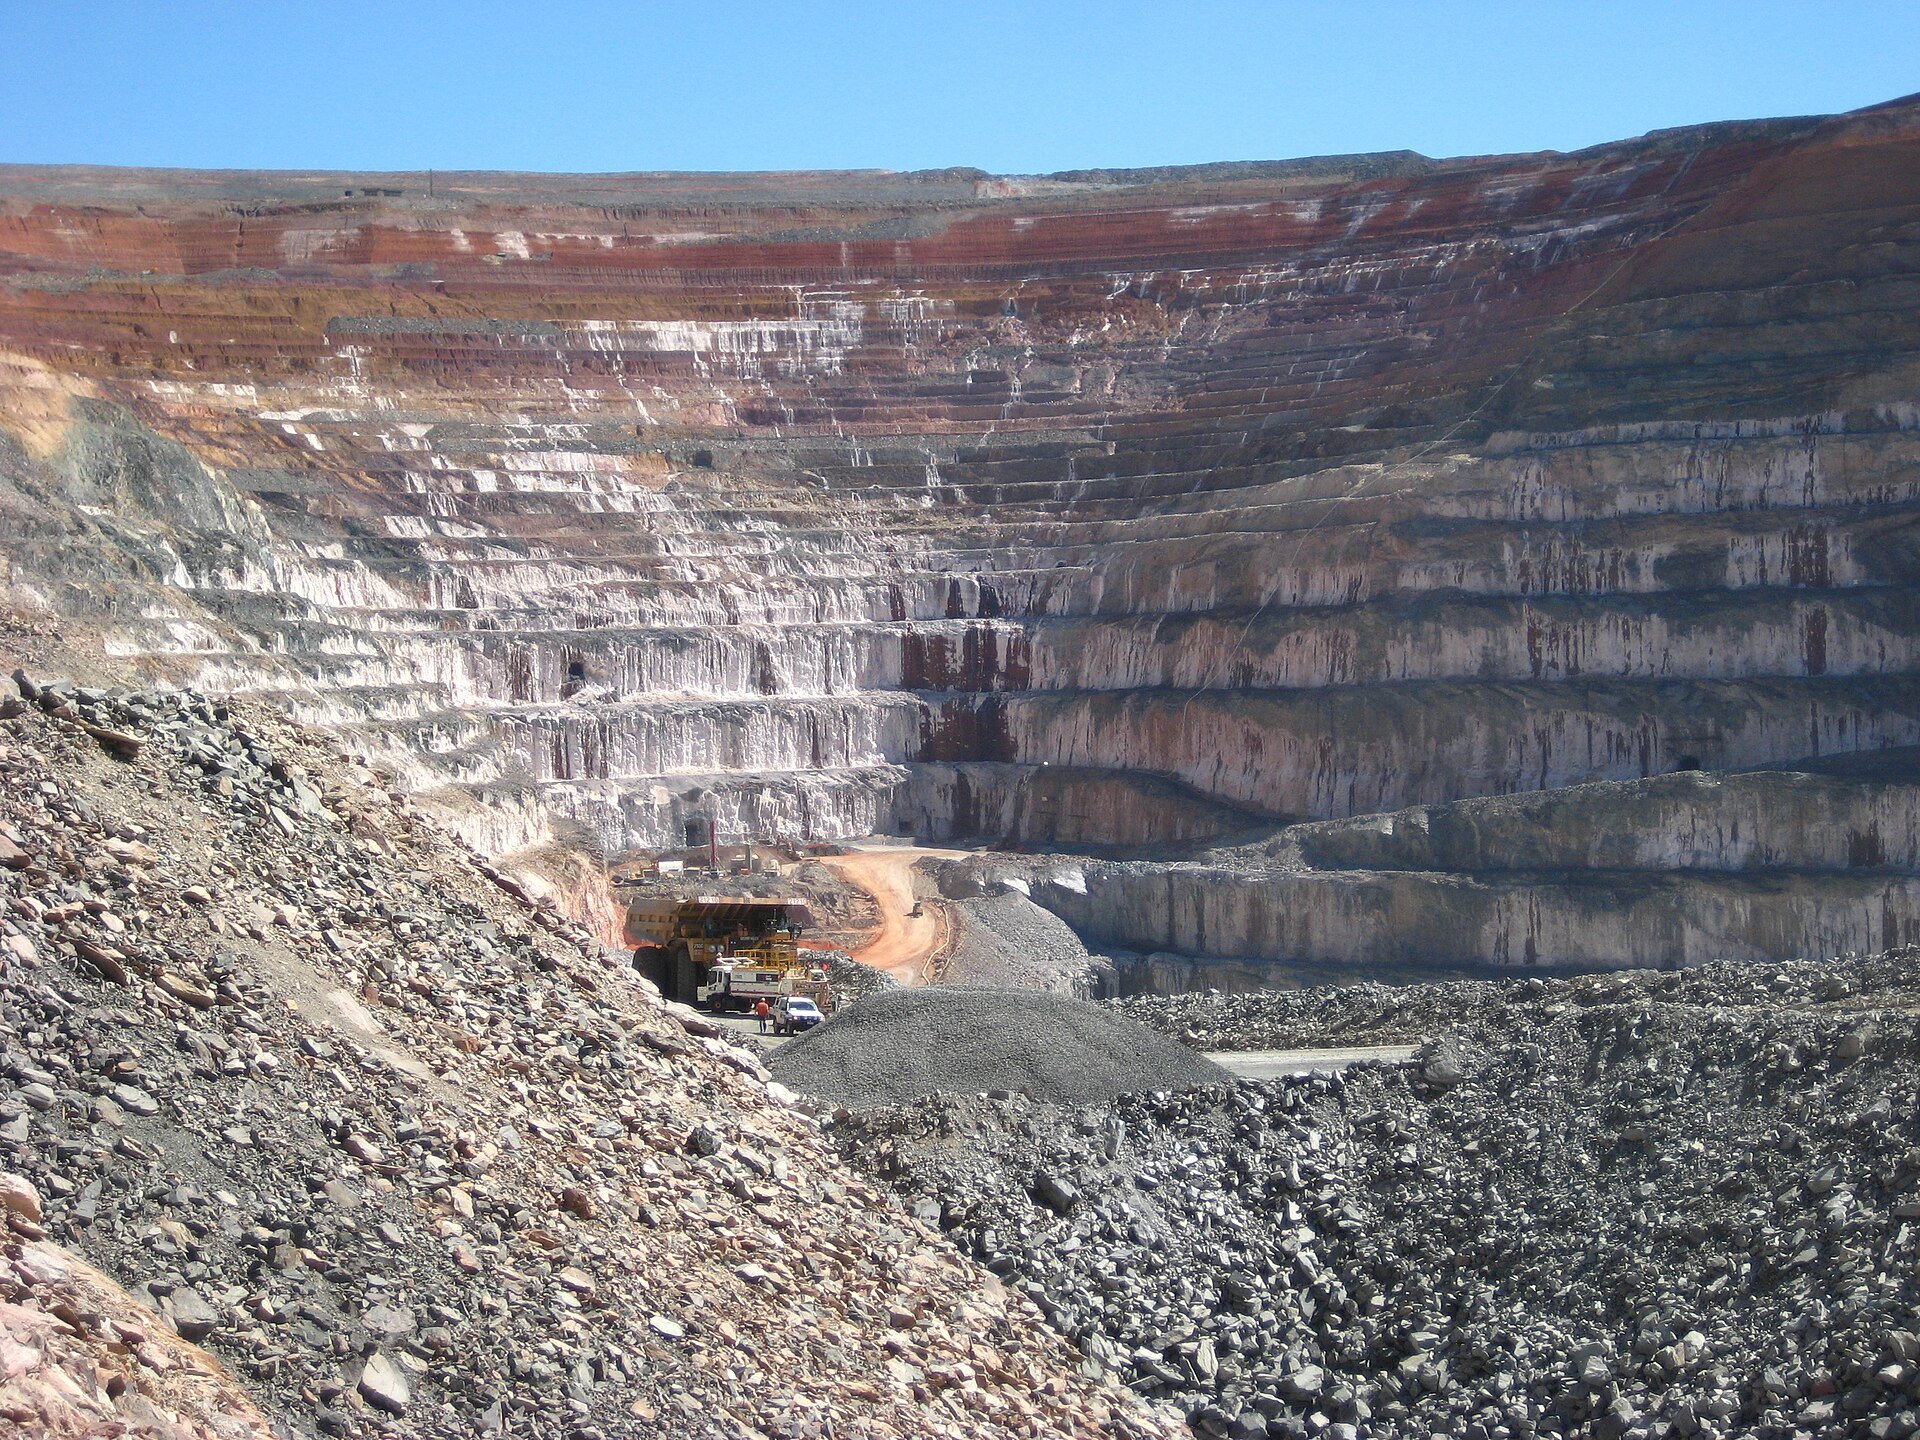
- Project Design: Conventional open‑pit heap‑leach operation; low strip ratio ≈2.2:1.
- Sensitivity to Gold Price ($4,550/oz):
- Post‑tax NPV (6% discount): ~US$696 M
- Post‑tax IRR: ~289%
- Strategic Advantage: Potential use of Borealis’ existing ADR facility to process loaded carbon from Sandman, offering a capital‑efficient development pathway.
- Qualified Person: Jerod Eastman, President of DJ 6E Consulting LLC, reviewed and approved the technical report and PEA.
- Cautionary Statement: The PEA is preliminary, based on inferred resources; no guarantee of economic viability.
Notable Quotes
- “The Sandman PEA demonstrates compelling economics and strong leverage to gold price, reinforcing our confidence in advancing this project toward development.” – Kelly Malcolm, President & CEO, Borealis Mining Company Limited.
More from Borealis Mining Company Limited
Oct 22, 2026 · 07:31