Skeena Gold & Silver Announces Pricing of US$750 Million Senior Secured Notes Offering to Refinance Former Project Financing and to Fund Partial Buyback of Existing Gold Stream
Skeena de-risks Eskay Creek with US$750M debt pivot and massive stream buyback to capture gold upside.
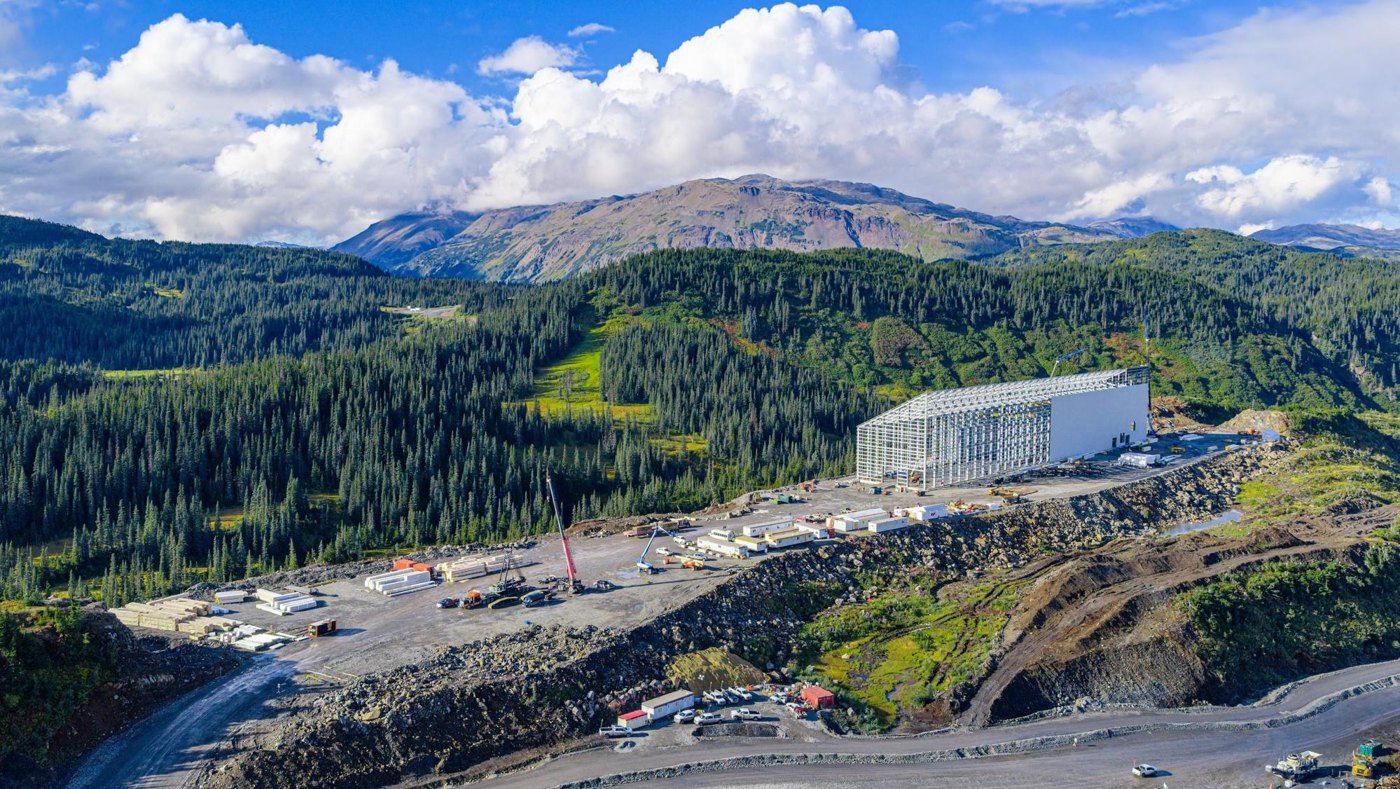
The most recent news (April 2, 2026) confirms the pricing of a US$750 million Senior Secured Notes offering at an 8.500% interest rate, due 2031. This follows the March 31 announcement of the offering and a project update. Key components include: - Stream Buy-Down: US$184 million will be used to buy back 66.67% of the existing gold stream held by Orion Resource Partners. - Debt Refinancing: The new notes replace a previously undrawn US$350 million senior secured term loan. - Project Progress: Eskay Creek is 49% complete as of February 28, 2026, with 66% of costs committed. - Cost Inflation: The construction budget increased by US$99 million (18%) to US$659 million, though leasing arrangements offset US$94 million of upfront cash needs. - Timeline: Initial production remains on track for Q2 2027.
The news is Material - Positive because it fundamentally shifts the project's future profitability. By buying down two-thirds of the gold stream, Skeena retains significantly more exposure to record-high gold prices, which outweighs the 8.5% interest cost on the notes. - Margin Expansion: Reducing the stream royalty is a permanent improvement to the Life of Mine (LOM) All-In Sustaining Costs (AISC). - Liquidity Buffer: The US$750M raise provides a massive cash cushion. After the stream buyback (~US$184M) and interest reserve (~US$94M), the company has roughly US$472M for remaining construction (estimated at US$354M net of leasing). - Cost Overruns: While the US$99M budget increase is a negative, it was largely anticipated due to global inflation and is effectively neutralized by the new financing and leasing structures.
Skeena is developing the Eskay Creek Gold-Silver Project in the Golden Triangle of British Columbia. It is a past-producing mine being redeveloped as an open-pit operation. - Flagship Stats: 4.6 Moz AuEq Reserves at 3.6 g/t AuEq. - Production: Expected 450,000 oz AuEq/year (Years 1-5). - Economics: LOM AISC (net of silver) of US$300/oz Au, making it one of the lowest-cost potential producers globally.