Silver X Mining Closes C$69M Brokered Private Placement of Secured Convertible Debentures
Silver X secures C$69M to transform from junior producer to district-scale silver powerhouse
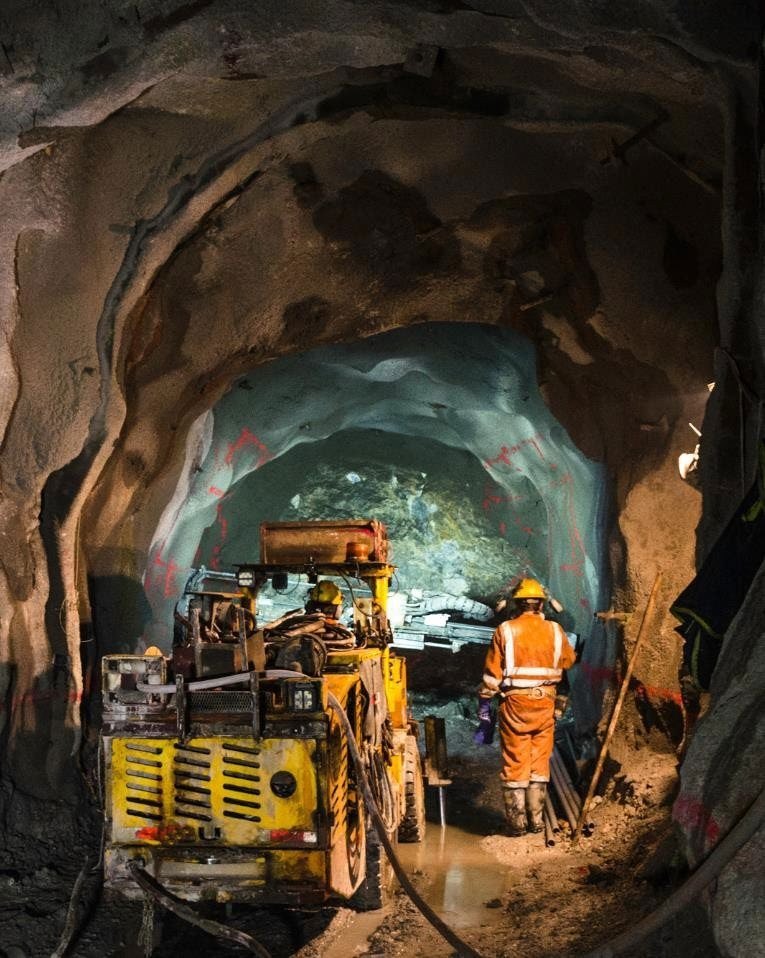
The most recent news (March 18, 2026) announces the closing of a C$69,000,000 brokered private placement of secured convertible debentures. This includes a full exercise of the 15% overallotment option. The debentures carry a 10% annual interest rate, mature in five years, and are convertible into common shares at C$1.62 per share. This follows a series of operational successes, including being ranked 8th on the 2026 TSX Venture 50 and reporting record production growth in Q4 2025.
The impact is Material - Positive. While the 10% interest rate is high and the debt is secured against company assets, the sheer scale of the capital (C$69M) relative to the company’s previous market cap (~C$73M) is transformative. - Funding Certainty: This provides the "financial platform" (as per CEO Garcia) to execute the 2025 PEA, which requires US$82M in initial CAPEX to reach 6.2M oz AgEq annual production. - Validation: The full exercise of the overallotment option suggests strong institutional appetite. - Conversion Premium: The conversion price of C$1.62 is significantly higher than the C$0.50 financing price seen in late 2025, suggesting management and lenders anticipate substantial share price appreciation. - Operational De-risking: The funds support the 40,000-meter drill program and the expansion of the Nueva Recuperada plant to 3,000 tpd.
Silver X operates the Nueva Recuperada Silver Project in Huancavelica, Peru. It is a district-scale asset (20,795 hectares) with over 500 identified veins. - Tangana Mining Unit: Currently producing (~600-720 tpd). - Plata Mining Unit: High-grade unit under development for 2026/2027 restart. - PEA Highlights: 14-year mine life, US$440M NPV (5%), and 69% IRR, aiming for 6.2M oz AgEq per year.