Other
Imperial Announces Normal Course Issuer Bid
Imperial Metals Initiates Small Buyback Amidst Production Headwinds
Executive Summary
- Imperial Metals Corporation received TSX acceptance for a Normal Course Issuer Bid (NCIB).
- Program allows repurchase of up to 890,855 common shares (~0.5% of outstanding).
- Funding source is working capital; duration May 28, 2026 to May 27, 2027.
- Primary purpose is to satisfy obligations under Non-Management Directors’ Plan and Share Purchase Plan.
- Previous bid approved for 814,089 shares; historical repurchase in last 12 months was 166,500 shares at $6.08 VWAP.
- Q1 2026 earnings (May 6) showed revenue decline ($154.6M vs $196.6M) and net income drop ($14.4M vs $41.3M) due to lower metal production, despite higher commodity prices.
- Production guidance for 2026 remains unchanged despite significant year-over-year volume declines at Mount Polley (Copper -51%) and Red Chris (Copper -18%).
Material Impact
- Size of Impact: The NCIB represents only 0.5% of total outstanding shares, which is immaterial to the overall capital structure or market cap.
- Strategic Intent: The bid is primarily administrative (Director Plans) rather than a strategic signal of undervaluation or aggressive capital return.
- Financial Health: Funding from working capital indicates liquidity remains sufficient post-debt repayment in 2025, but does not offset the operational decline seen in Q1 earnings.
- Market Sentiment: While buybacks are generally viewed positively, the context of declining production volumes (Mount Polley copper down 51% YoY) dampens the positive sentiment. The market may view this as a maintenance move rather than a growth catalyst.
- Conclusion: The news is not material enough to drive significant price appreciation on its own; it serves as a minor liquidity management tool amidst operational headwinds.
III · Price
Company Overview
- Flagship Projects: Mount Polley Mine (BC) and Red Chris Mine (BC). Huckleberry Mine is on care and maintenance.
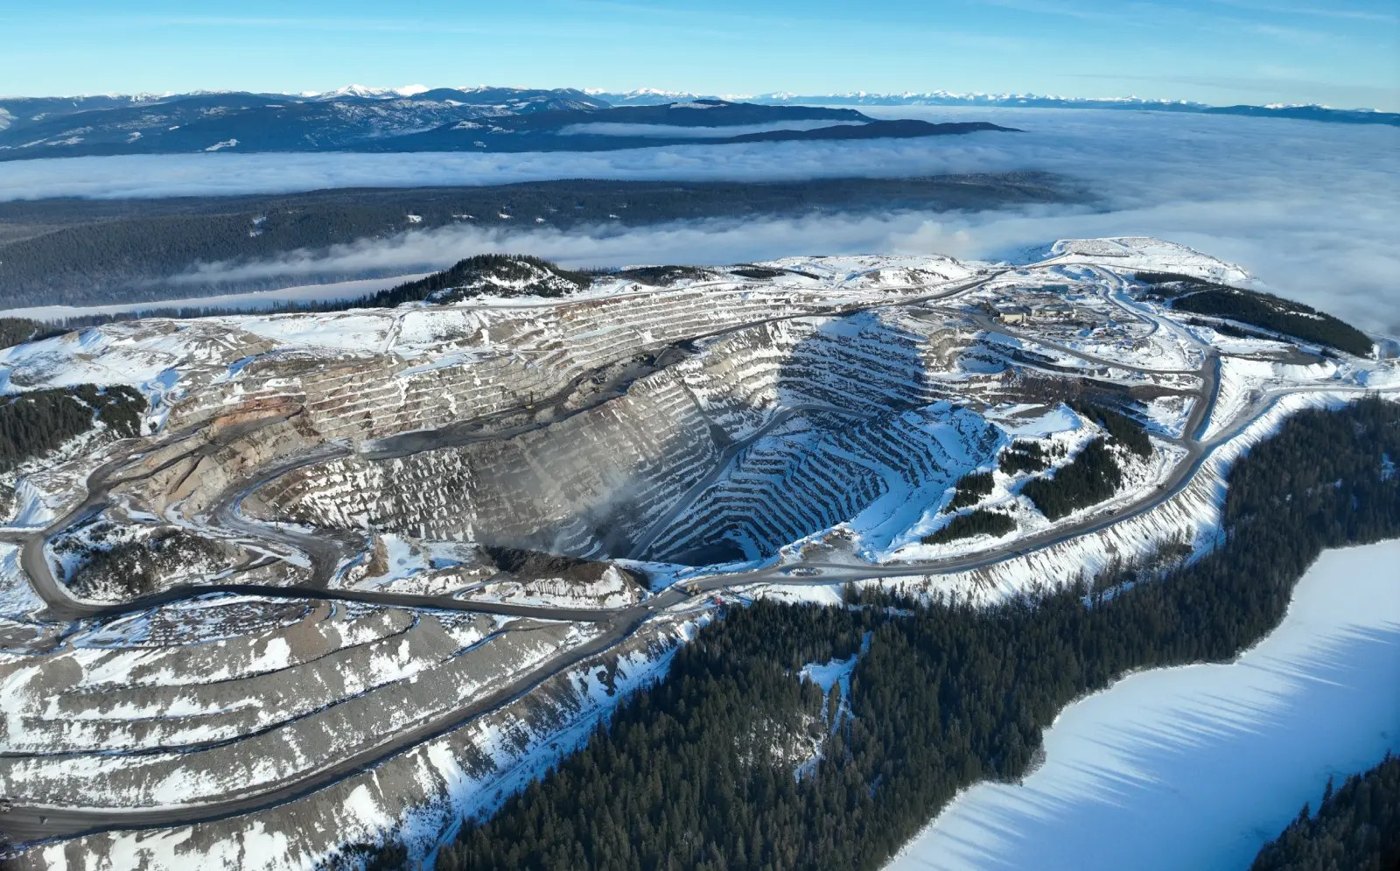
- Mount Polley: Open-pit copper-gold mine. Facing grade depletion; 2026 guidance remains 19-21M lbs Cu, but Q1 production was down 51% YoY.
- Red Chris: Copper-gold mine (30% interest). Block cave feasibility study advancing for H2 2026 completion. Production down 18% YoY in Q1.
- Operations: Both mines remain on track to meet full-year guidance despite quarterly volume declines, driven by higher metal prices offsetting lower volumes.
More from Imperial Metals Corporation
Aug 06, 2026 · 18:52