Spanish Mountain Gold Expands Higher Grade Near Surface Mineralization Starting at 16 M Down the Hole Intersecting 40.7 M of 1.26 g/t Gold and Files Updated Preliminary Economic Assessment
Spanish Mountain confirms bulk continuity in 21 infill holes, with the best gram-metres representing one-third of the prior release.
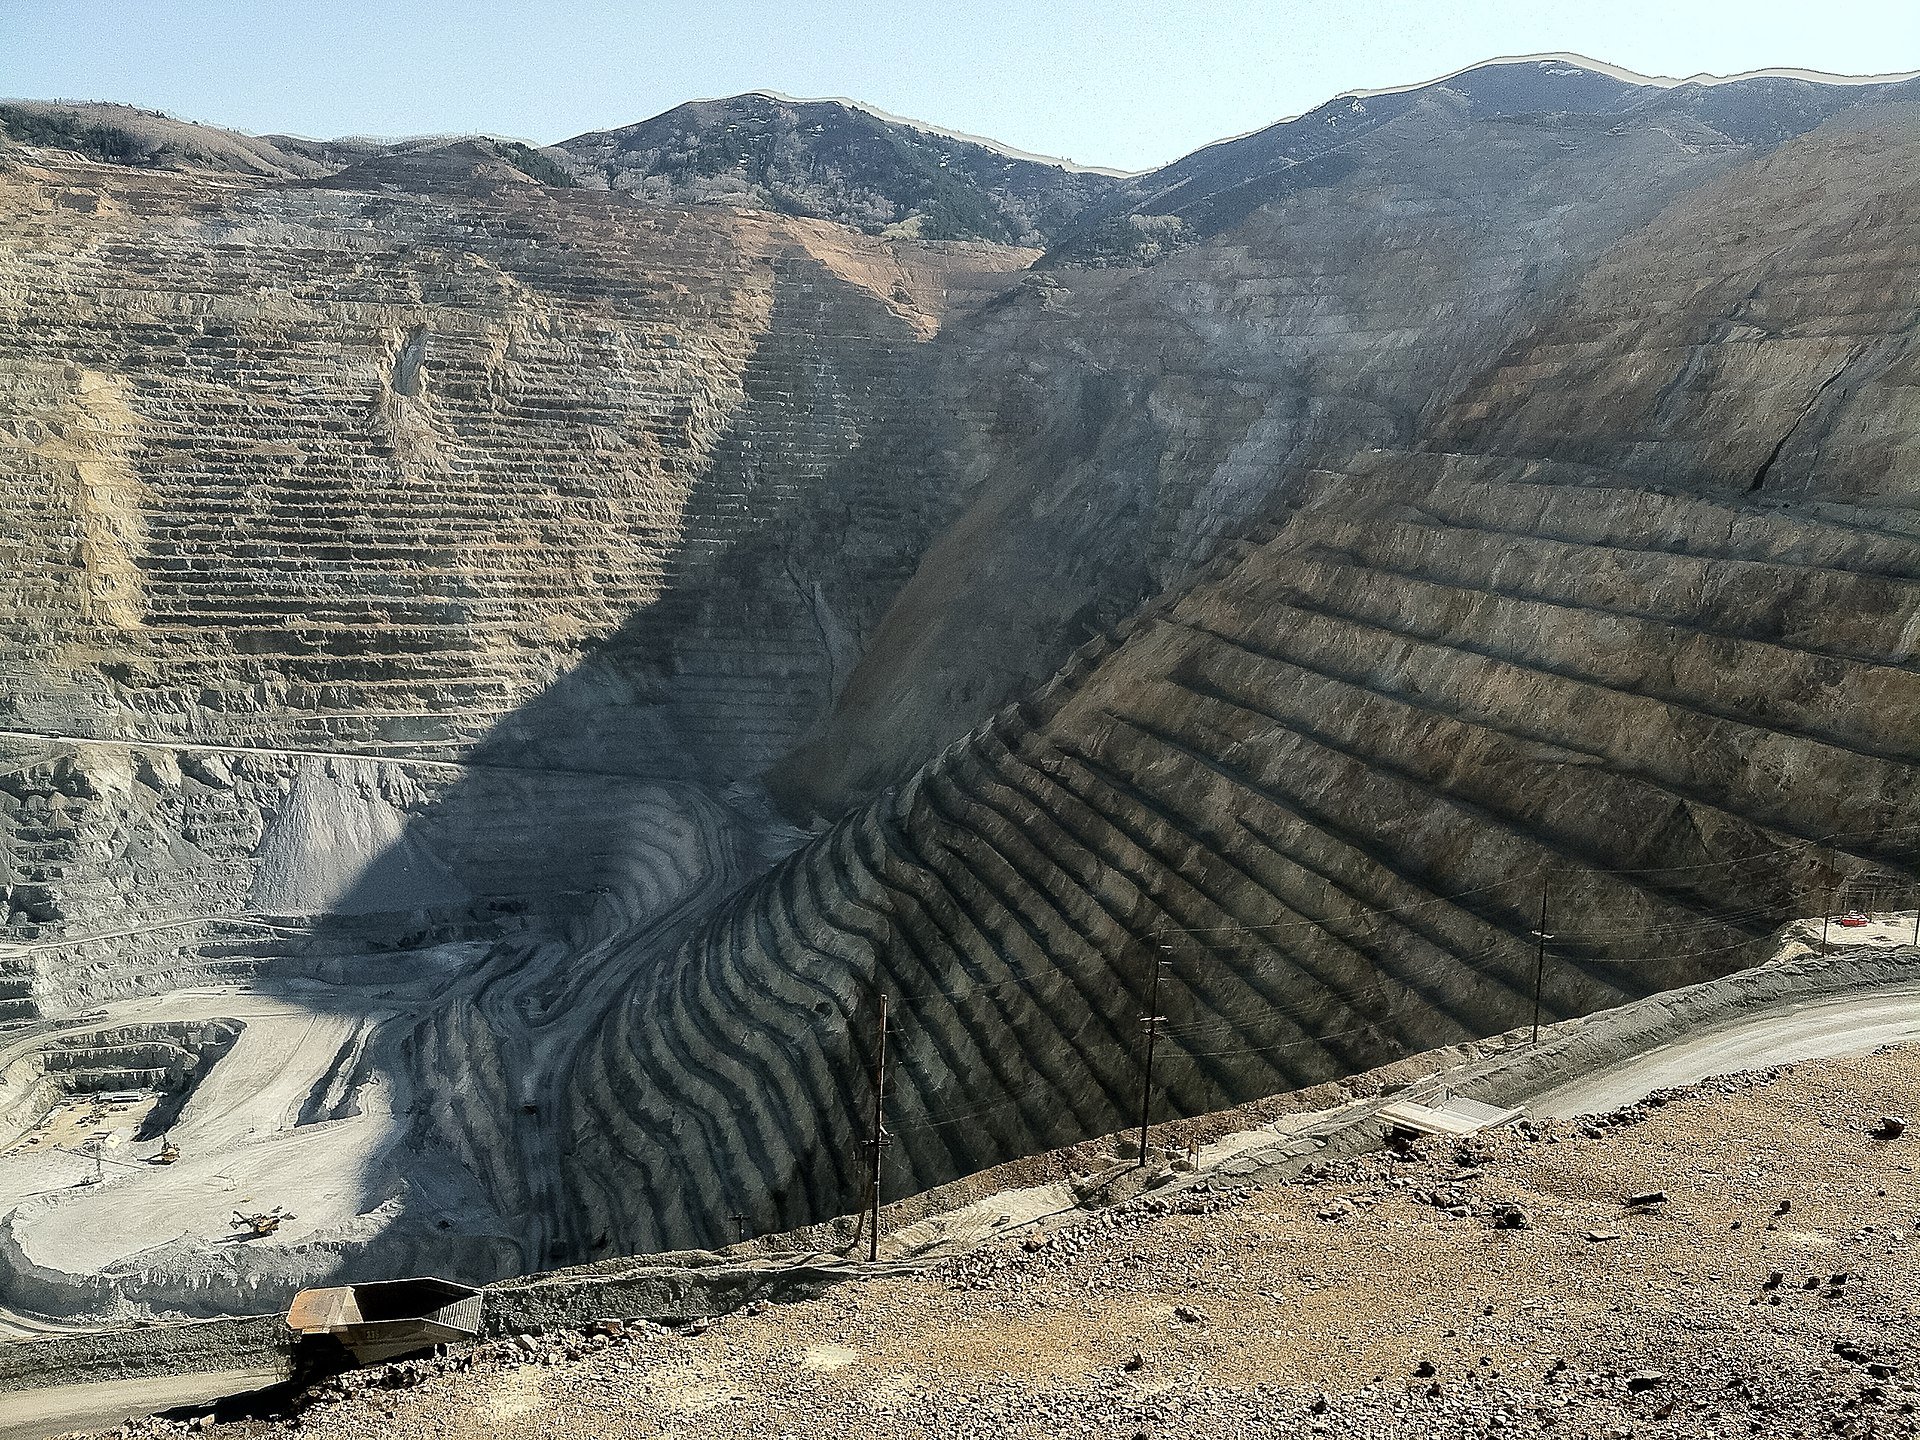
Spanish Mountain Gold Ltd. (SPA) released a comprehensive update on November 9, 2026, encompassing drill assay results, the filing of a preliminary economic assessment, and a royalty buyback agreement. The company reported that 47,011 meters of the planned 60,000-meter 2026 Feasibility Drill Program have been completed. Assays were released for holes 26-DH-1419 through 1436, as well as 1438, 1439, and 1441, with results pending for 49 additional drilled holes.
The reported intervals, based on core length with true thickness not determined, include the following:
- 26-DH-1421: 138.55 m @ 0.50 g/t Au from 14.85 m, incl. 40.70 m @ 1.26 g/t from 16.00 m
- 26-DH-1429: 174.00 m @ 0.29 g/t from 51.00 m, incl. 43.00 m @ 0.93 g/t from 51.00 m and 7.55 m @ 0.38 g/t from 138.30 m
- 26-DH-1432: 219.20 m @ 0.29 g/t from 44.00 m, incl. 28.00 m @ 0.96 g/t from 44.00 m and 4.00 m @ 1.16 g/t from 126.00 m
- 26-DH-1434: 241.00 m @ 0.30 g/t from 44.00 m, incl. 68.00 m @ 0.52 g/t from 44.00 m and 93.00 m @ 0.36 g/t from 192.00 m
- 26-DH-1422: 155.00 m @ 0.34 g/t from 161.00 m, incl. 86.07 m @ 0.43 g/t from 170.00 m
- 26-DH-1435: 258.20 m @ 0.29 g/t from 51.30 m, incl. 147.50 m @ 0.41 g/t from 162.00 m
- 26-DH-1438: 195.00 m @ 0.27 g/t from 44.00 m, incl. 87.00 m @ 0.39 g/t from 75.00 m
- 26-DH-1441: 99.86 m @ 0.33 g/t from 58.00 m, incl. 14.10 m @ 0.80 g/t from 139.90 m
- 26-DH-1427: 43.50 m @ 0.45 g/t from 5.50 m, incl. 12.10 m @ 1.01 g/t from 23.90 m
- 26-DH-1419: 46.93 m @ 0.30 g/t from 28.07 m
- 26-DH-1425: 69.90 m @ 0.24 g/t from 152.40 m, incl. 11.80 m @ 0.92 g/t from 210.50 m
- 26-DH-1430: 10.00 m @ 0.98 g/t from 212.00 m
- 26-DH-1436: 4.00 m @ 2.62 g/t from 78.00 m
- 26-DH-1433: 6.67 m @ 3.34 g/t from 416.00 m
- 26-DH-1439: 11.85 m @ 0.70 g/t from 16.60 m (table also shows an "including" 42.00 m @ 0.64 g/t from 118.00 m, which sits outside the parent interval)
- 26-DH-1420: no significant intercepts
On November 6, 2026, the company filed its 2026 Preliminary Economic Assessment (PEA) on SEDAR+. Section 24 of the filing outlines an "alternate project development plan" featuring a larger pit containing approximately 348 million tonnes of mill feed at 0.39 g/t Au for 4.4 million ounces from measured, indicated, and inferred material. This scenario is to be assessed within the feasibility study rather than adopted as the base case.
Additionally, Spanish Mountain Gold entered into an agreement to buy back 0.625% of the 2.5% Mickle Net Smelter Return (NSR) for $755,000 in cash, payable in stages to July 1, 2030. The deal includes a second closing for the vendor's additional interest for $5,000 and grants the company the right to buy down the remaining Mickle NSR to 0.6875% for $343,750.
Spanish Mountain Gold Ltd. (SPA) is a pre-economic feasibility-stage gold developer with 342.1 million tonnes at 0.42 grams per tonne of gold indicated and inferred resources (4.66 million ounces) across the Main and Phoenix zones, plus an additional 96.8 million tonnes at 0.32 grams per tonne of gold in the inferred category (1.01 million ounces). The company has filed a preliminary economic assessment projecting a US$2,156 million after-tax net present value at a 5% discount rate based on a US$3,600 per ounce gold price, supported by approximately 260 kilometers of drilling. At this stage, a single batch of infill assays typically does not alter net asset value unless it changes reserve-grade conversion, mine life, or the early-year grade profile.
The recent drilling serves as infill and resource-definition work for the feasibility study rather than discovery or step-out holes into a new system. The results present a mixed confirmation of grade, with hole 1421 performing above expectations while several headline holes fell below. The best previously reported intercept on the deposit was 26-DH-1414, reported on 8 October 2026, which returned 295.5 meters at 0.54 grams per tonne of gold, including 107.0 meters at 0.93 grams per tonne of gold, totaling 159.6 gram-meters. Prior to that, 26-DH-1390, reported on 27 July 2026, returned 252.3 meters at 0.82 grams per tonne of gold, including 93.5 meters at 1.32 grams per tonne of gold, totaling 206.9 gram-meters. Additionally, 26-DH-1337, reported on 10 March 2026, returned 282.5 meters at 0.70 grams per tonne of gold, including 116.8 meters at 1.20 grams per tonne of gold, totaling 197.8 gram-meters.
The best intercept in the current release yielded 69.3 gram-meters, representing 43% of the October anchor, 33% of the July anchor, and occurring at a lower grade. The primary gold discovery anchor, 25-DH-1299 reported on 1 December 2025, returned 139.82 meters at 0.82 grams per tonne of gold plus 45.54 meters at 1.67 grams per tonne of gold and drove the stock price from $0.12 to $0.27.
The stock has held roughly double its pre-Orca level, but recent drilling anchors have not been embedded in the valuation. The market sold the 8 October release outright, with the price moving from $0.27 on 7 October to $0.24 on 8 October. The stock has round-tripped from $0.40 on 21–22 September to $0.20 by 26 October and now sits at $0.23, approximately 43% below its 52-week high and roughly where it traded in January 2026. Because the recent drill anchors are not embedded and these are infill holes, the materially weaker gram-meters do not constitute a material negative. Equally, because the result is not better in grade-and-width substance than anything previously demonstrated on the property, the unpriced-positive rule does not apply.
The release provides the most complete evidence yet that the low-grade envelope is continuous across the deposit at infill spacing, with 20 of 21 holes mineralized. It also delivers one genuinely useful shallow high-grade block of 40.7 meters at 1.26 grams per tonne of gold from 16 meters, which supports the reduced-stripping thesis the company has been promoting since December 2025. The release does not change the resource grade, the mine plan, the capital expenditure, the permitting timeline, or the net present value.
The company also announced a royalty buyback, a small capital allocation of US$755,000 to retire 0.625% of a 2.5% net smelter return (NSR), with a buydown option to 0.6875%. This transaction is immaterial to value against the company’s holding of C$29.9 million in cash at 30 June 2026. The news represents incremental feasibility support with grade slightly soft relative to the deposit's own resource grade, dressed with a re-filed preliminary economic assessment and a small royalty transaction, with nothing here re-pricing the equity.
Spanish Mountain Gold Ltd. (TSX-V: SPA, OTCQB: SPAUF, FSE: S3Y) owns 100% of the Spanish Mountain Gold project in the Cariboo Gold Corridor of central British Columbia, located about 70 km from Williams Lake with paved highway access roughly 6 km away.
Resources (effective 19 May 2026): * Main deposit M&I: 342.0 Mt @ 0.42 g/t Au for 4,663 koz Au plus 7,219 koz Ag, at a 0.15 g/t cut-off * Main Inferred: 42.4 Mt @ 0.28 g/t for 382 koz * Phoenix deposit Indicated: 0.09 Mt @ 0.25 g/t (0.72 koz) * Phoenix deposit Inferred: 54.45 Mt @ 0.36 g/t (629 koz) * Consolidated M&I: 342.1 Mt @ 0.42 g/t (4,664 koz) * Consolidated Inferred: 96.8 Mt @ 0.32 g/t (1,011 koz)
A preliminary economic assessment (PEA) was filed on 6 November 2026, with economics first released on 21 September 2026. The plan outlines a conventional open pit and mill operation at 31,000 tpd with a 25.8-year life, producing 3.33 moz payable gold. Average long-of-mine production is estimated at ~129.5 koz/yr at US$1,450/oz AISC and 207 koz/yr at US$1,098/oz over years 1–5. Initial capital expenditure is US$1,050.4M, with a strip ratio of 1.8:1, long-of-mine gold recovery of 89% and silver 44%, utilizing dry-stack filtered tailings and coarse-particle flotation with gangue rejection. At US$3,600/oz, the project shows an after-tax NPV5% of US$2,156M (C$2,910M) and an IRR of 35.2%. At US$4,400/oz, the NPV5% is US$3,142M and the IRR is 46.3%.
Regarding financing, Spanish Mountain Gold sold a 1.5% NSR to Wheaton Precious Metals for US$55M. The first instalment of US$22.5M was received on 1 May 2026, with US$12.5M payable on completing 60,000 m of drilling and US$20M on EA approval. The feasibility study is fully funded, with BBA Engineering leading the work, targeting completion in H1 2028 with a build decision in 2028.
Prior-period context (not disclosed in today's release): cash stood at C$29.86M and total assets at C$148.3M at 30 June 2026 versus total liabilities of C$33.75M and equity of C$114.55M, i.e. book value C$0.22 per share and roughly 1.0x price-to-book at C$0.23. Six-month SG&A was C$2.58M, net loss C$2.59M, capex C$9.77M, and financing inflow C$32.9M (the Wheaton tranche). The Q1 2026 MD&A carried a going-concern flag before that financing landed; the June balance sheet removes the immediate pressure but not the funding requirement for a US$1.05B build.