Abasca Resources Completes Summer Drill Program at Loki Flake Graphite Deposit, Collects 10 Tonnes of Core for Pilot Plant Testing, and Appoints New Chief Financial Officer
Abasca completes its C$14M graphite program with zero assays, adding no new data to the project.
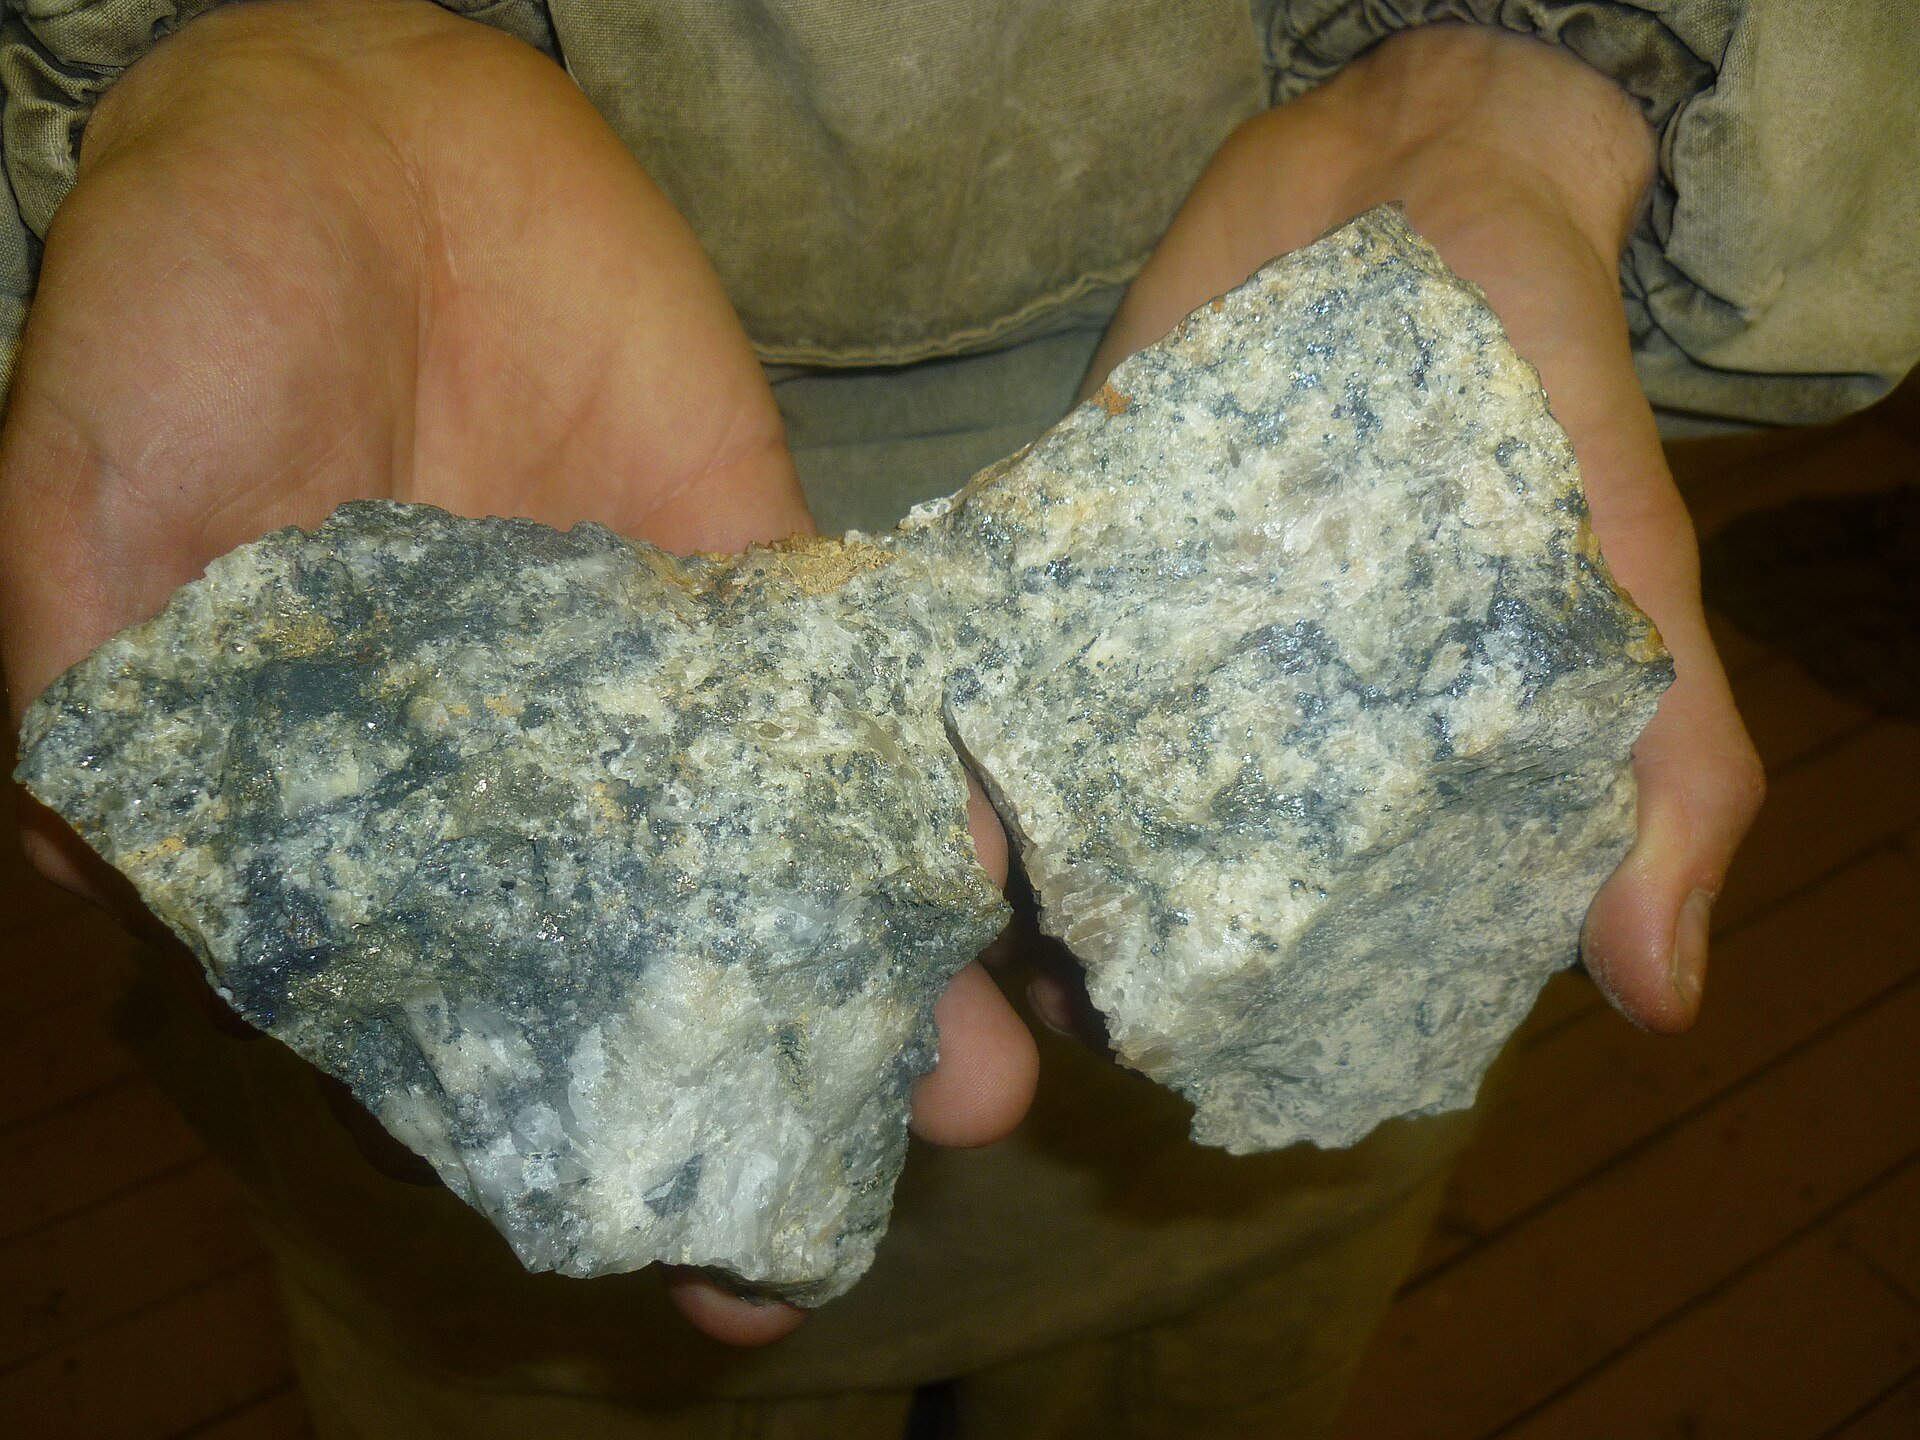
Abasca Resources Inc. (ABA) issued an operational and procedural update on October 28, 2026, announcing the completion of its summer drilling program at the Loki Flake Graphite Deposit, part of the Key Lake South Project in Saskatchewan. The company also reported a change in its financial leadership. The release did not contain assay results, grades, cut-offs, or true widths, serving instead as a status report on field activities and personnel.
The summer program at Loki concluded with 1,956 meters drilled across 16 holes, designated KLS-26-131 through KLS-26-145. Individual hole lengths ranged from 41 meters to 153 meters, with all holes collared at an azimuth of 215° and an inclination of -80°. Approximately 10 tonnes of PQ-diameter core were collected from across the length of the deposit. This material is intended for a pilot plant at SGS Canada in Lakefield, where it will be processed into flake concentrate for purification and battery-anode material testing.
The company referenced prior metallurgical results, noting that flotation concentrate has previously reached up to 97.0% C(t). Purified concentrate achieved 99.76% C(t) through NaOH and HCl leaching. These figures represent historical data rather than new findings. Additionally, environmental characterisation testwork is scheduled to be conducted and incorporated into a future Feasibility Study and Environmental Impact Assessment (EIA).
Geological information provided in the release was limited to a figure caption describing hole KLS-26-142, which identified "20.4 m of continuous graphitic metapelite within a total of 36.85 m zone." This statement was not an assay result.
Effective October 27, 2026, Lawrence Cheung, CPA, of Malaspina Consultants, was appointed Chief Financial Officer, replacing Erik H. Martin. Brian McEwan, P.Geo., continues to serve as Vice President of Exploration and Development.
The current 1,956-meter, 16-hole program is characterized as a bulk-sample and geotechnical exercise rather than a resource-growth initiative, with the company claiming no resource extension. This scale contrasts with previous programs, which included 5,925 meters in 23 holes during winter 2025, 6,210 meters in 27 holes during summer 2025, and 4,922 meters in 30 holes during winter 2026.
Abasca Resources Inc. (ABA) is a pre-revenue explorer and developer with a 22.8 Mt resource, a preliminary economic assessment (PEA), but no reserves, mine, or permits. The company carries an explicit going-concern flag, citing an accumulated deficit of C$20.9M per the fiscal year 2026 management’s discussion and analysis.
The recent release did not alter the scale, grade, or immediate odds of the project. The program was one-third the size of the 2025 summer program and focused exclusively on sample collection, yielding no new tonnes, strike extensions, or zones. No assays were reported. While the collection of samples for a pilot plant to produce purified, anode-testable concentrate represents a prospective de-risking step for the company’s flake graphite thesis, the release announced only that the sample was collected, not that the plant operated or what it produced. The value event remains the pilot-plant result, which is still ahead.
Market reaction to previous data has been muted. The market appears to be paying approximately C$14M for a project with a US$130M NPV, discounting the price deck, US$216M initial capex, financing, and permitting almost entirely. Against a market that already assumes nothing, a release containing no data cannot be viewed as positive.
For a C$14M explorer, the completion of an infill and bulk-sample program with zero assays and the appointment of a contract CFO is ordinary news flow. It neither advances nor damages the investment case; the thesis remains exactly where the 2026-08-19 PEA left it.
Structurally, Abasca Resources reported a FY-2026 net loss of C$5.55M and an operating cash outflow of C$8.60M. Cash stood at C$1.50M as of 2026-04-30, a position topped up by a C$2.25M flow-through placement on 2026-09-29. Shares outstanding increased from 120.2M on 2026-01-31 to 154.9M, representing approximately 29% basic dilution in nine months. With 18.4M warrants and 10.0M options outstanding, the fully diluted share count is 183.3M, a 52% increase versus January basic. At C$0.09, the fully diluted market cap is approximately C$16.5M. Against a US$216M initial capex, equity cannot build this asset alone; a partner, offtake prepayment, or government support is a precondition, each of which is dilutive or dilutive-equivalent.
Abasca Resources Inc. (TSXV: ABA) is a Saskatchewan-focused critical-minerals explorer whose sole material asset is the 100%-owned Key Lake South (KLS) Project. The property spans 23,974 hectares in the Athabasca Basin, located approximately 15 km south of the former Key Lake mine and current Key Lake mill. Highway 914 crosses the property, and grid power is available nearby.
The primary value driver is the Loki Flake Graphite Deposit. A pit-constrained mineral resource estimate effective April 23, 2026, identified 6.99 million tonnes at 8.27% Cg in the Indicated category, containing 0.58 million tonnes of graphite, and 15.83 million tonnes at 6.93% Cg in the Inferred category, containing 1.10 million tonnes of graphite, at a 2.30% Cg cut-off. The total resource stands at 22.82 million tonnes, containing approximately 1.68 million tonnes of contained graphite. This update converted 67% of the prior Inferred resource to Indicated, extending the strike to approximately 1,400 metres.
A preliminary economic assessment (PEA), announced on August 19, 2026, and filed on September 23, 2026, was prepared by Tetra Tech. The study outlines a 19-year open-pit operation processing 2,750 tonnes per day to produce approximately 66,500 tonnes per year of concentrate containing approximately 95% Cg. The project is projected to yield 1.2 million tonnes of payable graphite over its life with a 92.3% recovery rate and a 6.1:1 strip ratio. Capital expenditures are estimated at US$216 million initially and US$307 million in total. At a graphite price of US$1,450 per tonne and an exchange rate of 0.72 USD/CAD, the project shows an after-tax NPV8 of US$130 million and an internal rate of return (IRR) of 16.7%. The PEA projects cumulative after-tax free cash flow of approximately US$662 million. The analysis is unleveraged and excludes financing.
The company also holds uranium optionality, with more than 50 km of prospective conductors located along the strike of the past-producing Key Lake mine. There is currently no work programme or resource defined for this area. Additionally, the Thor Zone represents a parallel graphitic trend located a few hundred metres north. July 2026 drilling returned intercepts of 74.75–114.0 metres at 3.91–5.13% Cg. Drilling at Thor Zone has been deferred to winter 2027, according to the MD&A.
Management includes President and CEO Dawn Zhou, who holds an M.Sc. in Geology and is a CPA, and is the founder of Athabasca Potash, which was sold to BHP for US$341 million. VP of Exploration is Brian McEwan, a P.Geo. who previously worked on the NexGen Arrow delineation. The board includes Chair Dave Billard and VP of Engagement John Shmyr, who has experience in permitting. Insiders and associated corporations hold approximately 64% of the company based on the corporate presentation.
The capital structure, as presented, consists of 154.94 million shares, 9.98 million options, and 18.36 million warrants, resulting in 183.28 million fully diluted shares. The company carries no debt.