Atico Reports 2025 Fourth Quarter and Full Year Production Results
El Roble Turnaround Validated: 2026 Guidance Signals Cash Flow Recovery, But Debt Wall Looms
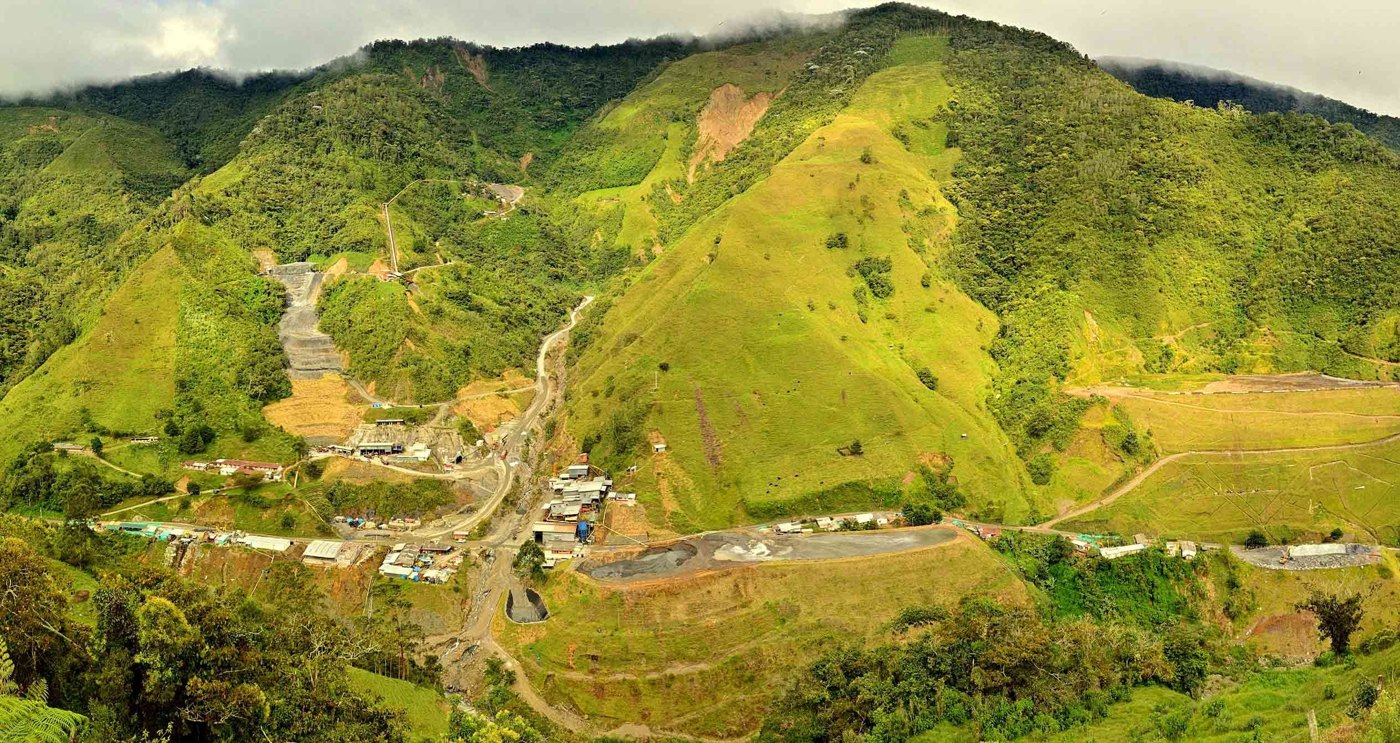
Atico Mining released its Q4 and Full Year 2025 production results on January 22, 2026. * Production Drop: Full-year 2025 copper production was 9.23M lbs, a steep 32% decrease year-over-year. Gold production dropped 12% to 8,013 oz. * Q4 Recovery: Q4 2025 showed improved momentum with 2.6M lbs Copper and 2,203 oz Gold, marking the best quarter of the year. * 2026 Guidance: Management forecasts a significant rebound for 2026: * Copper: 11.5M – 12.5M lbs (Approx. 25-35% increase over 2025). * Gold: 9,000 – 10,000 oz. * C1 Cash Cost: $1.50 – $1.60 per pound (highly competitive). * La Plata Project: A construction decision is targeted for Q2-Q3 2026 following permitting completion.
This release is positive as it confirms the operational "bottom" was likely hit in mid-2025. The company’s narrative of a "transitional year"—migrating mining operations to the upper parts of the El Roble mine—appears validated by the improved Q4 metrics. * Positives: The 2026 guidance suggests a return to historical production norms. With C1 cash costs projected at $1.50-$1.60, and assuming a prevailing copper price above $4.00, Atico should generate significant operating margins necessary to service its heavy debt load. * Negatives: The 32% drop in 2025 copper production undoubtedly strained cash flow during a critical period where the company faces arbitration payments and debt servicing. The company has no room for error in 2026; the projected production increase must materialize to fund liabilities.
Atico Mining is a Canadian-based operator focused on copper-gold projects in Latin America. * Flagship Asset (Producing): El Roble Mine (Colombia). A high-grade underground copper-gold mine. It has historically been a cash cow but suffers from a short mine life (currently projected to ~2027/2028). The company recently secured a critical 30-year mining title renewal in May 2025, removing an existential threat. * Development Asset: La Plata (Ecuador). A high-grade VMS project. It is currently in the permitting phase with a construction decision expected in 2026.