Denison Reports Readiness to Commence Construction of Flagship Phoenix ISR Project and Provides Capital Cost Update
Denison Signals Construction Readiness at Phoenix as Capital Costs Creep Toward $600 Million
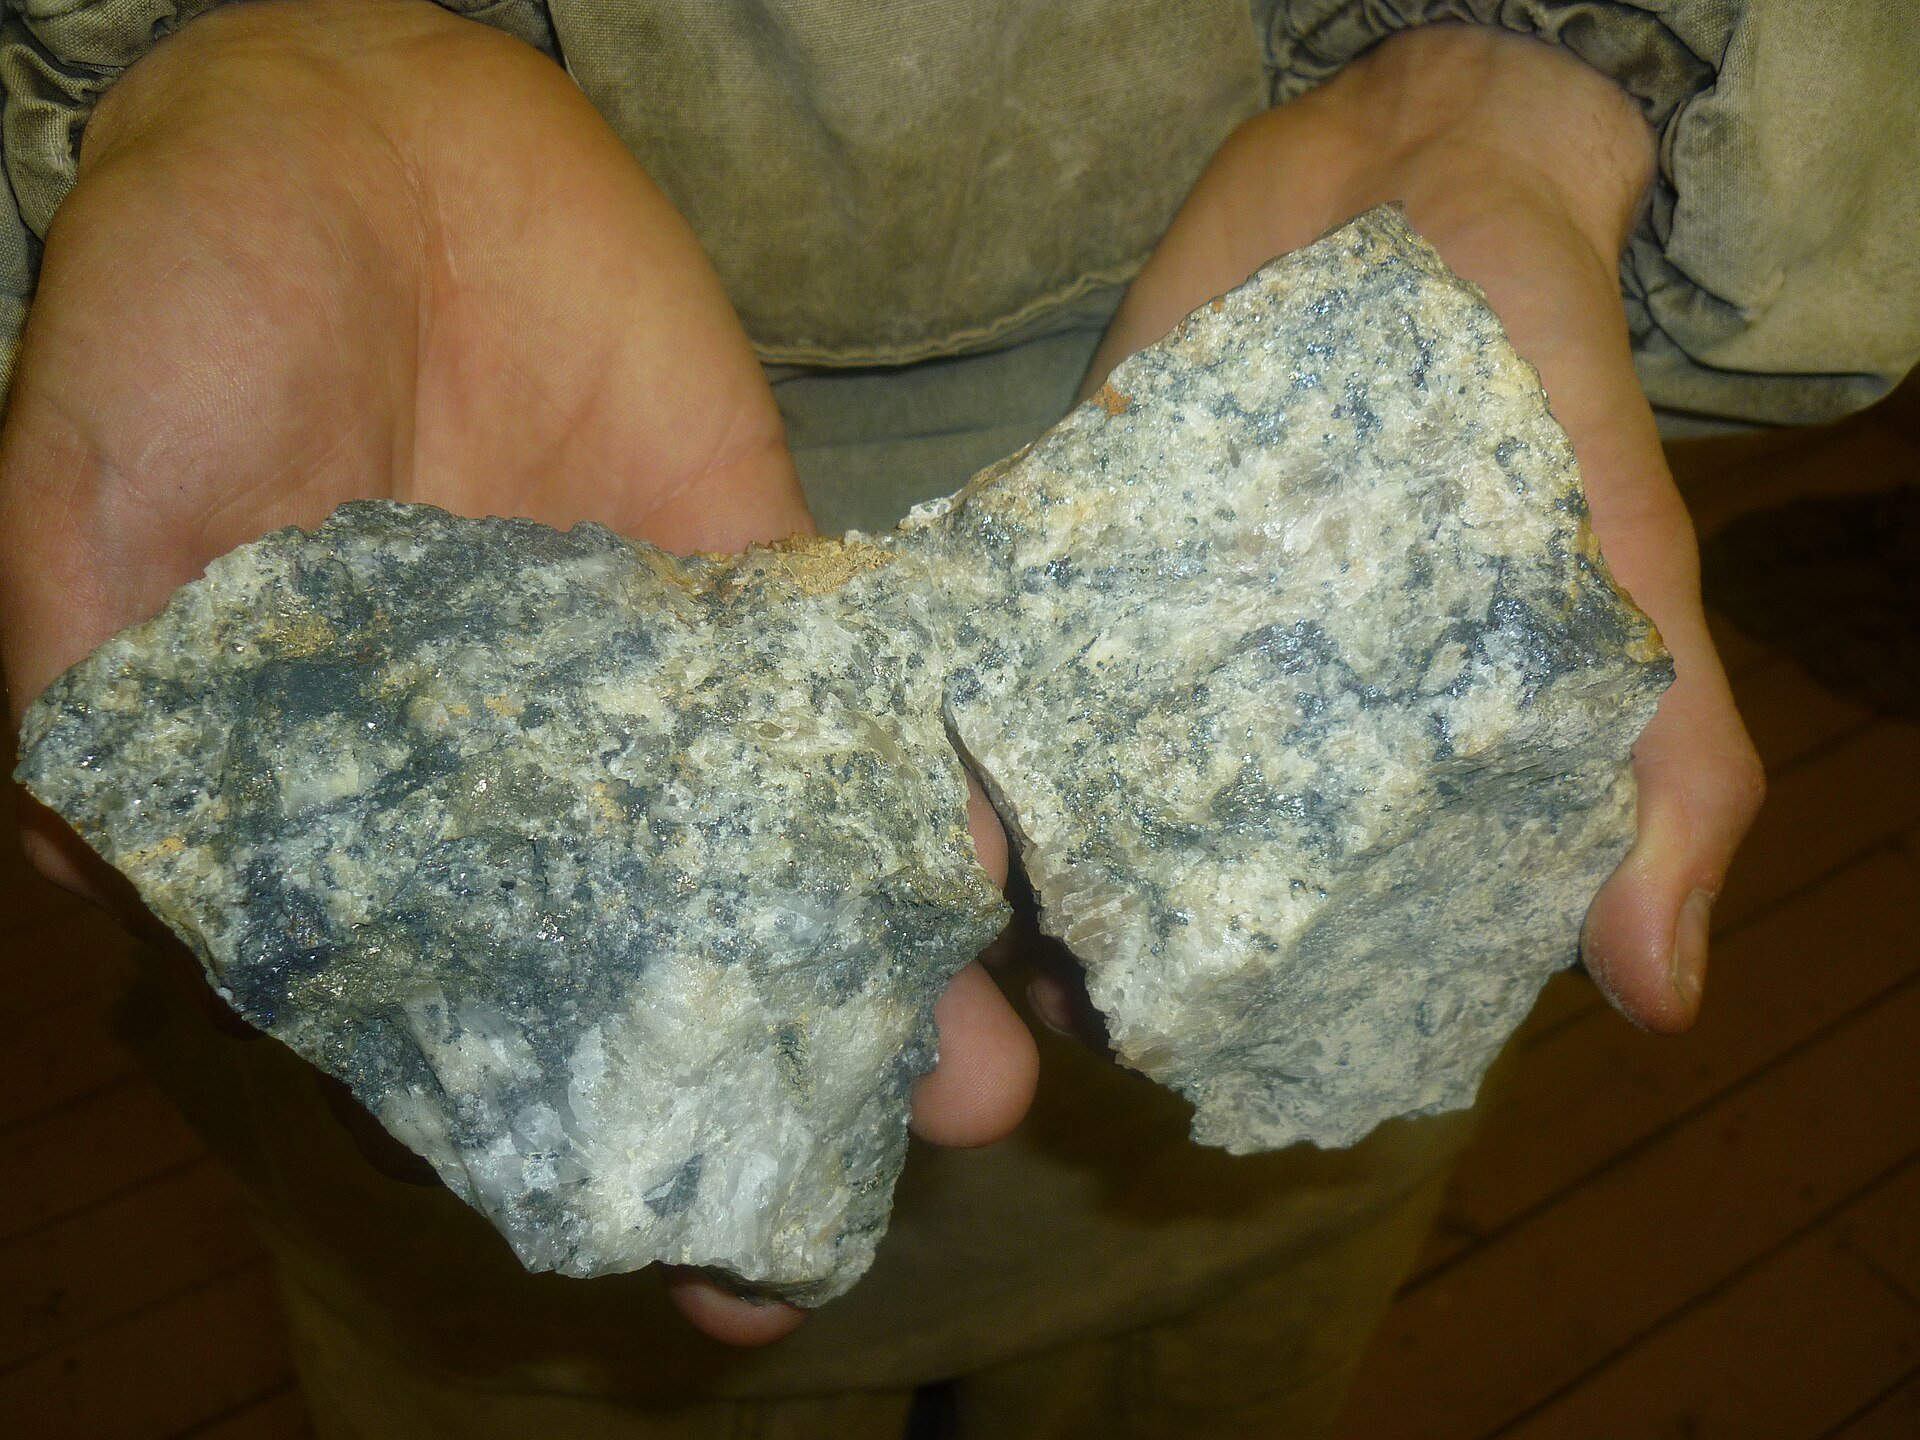
On January 2, 2026, Denison Mines announced it is ready to make a Final Investment Decision (FID) to begin construction at its flagship Phoenix In-Situ Recovery (ISR) project in Saskatchewan. Key highlights include the conclusion of the Canadian Nuclear Safety Commission (CNSC) public hearings in December 2025 and the maintenance of the mid-2028 production target. However, the company updated its initial capital cost (CAPEX) estimate to $600 million CAD, representing a 20% increase from the previous "inflated" 2023 feasibility study estimates. The company reports a strong liquidity position of approximately $700 million CAD in cash, physical uranium, and investments to fund this construction.
The impact is Material - Positive, as it marks the transition from a multi-year permitting phase to active mine construction. - Project De-risking: Moving to a "Construction Ready" status and concluding CNSC hearings are the final major regulatory hurdles for a uranium developer. The 87% engineering completion significantly reduces the risk of further technical design changes. - Cost Realism: While a 20% increase in CAPEX (to $600M) is a negative, it appears factored into the current balance sheet. The project still maintains an exceptional post-tax IRR of 73% at conservative uranium prices ($68-78/lb), suggesting robust economics despite inflation. - Balance Sheet Sufficiency: With $700M in available capital, Denison is one of the few developers capable of self-funding its flagship project without immediate equity dilution, though the margin for error has narrowed due to the cost increase. - Unresolved Legal Shadow: Missing from the "positive" tone of the latest release is an update on the November 2025 Judicial Review application by the Peter Ballantyne Cree Nation. This remains a material threat to the timeline if an injunction is granted.
Denison Mines is a leading uranium developer focused on the Athabasca Basin in Saskatchewan. Its flagship Phoenix Project (part of Wheeler River) is designed as the first large-scale In-Situ Recovery (ISR) uranium mine in Canada. The project is characterized by exceptionally high grades (11.4% U3O8) and aims to be among the lowest-cost producers globally. Denison also holds a 22.5% interest in the McClean Lake mill, which provides strategic processing infrastructure.